What You Actually Need to Know About Truist's Banking Platform
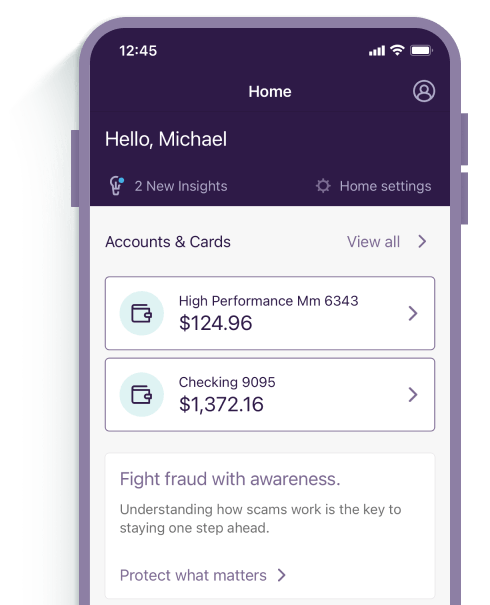
The merger between BB&T and SunTrust created one of the larger regional banks in the United States, and their digital infrastructure has been under continuous development since. I've worked with their systems for a few years now, mostly on the backend side, and there are some things they don't advertise that are worth knowing. The phrase gets thrown around in their marketing materials, but the actual substance is about how their digital platform connects to their community lending programs. When you open an account through their mobile app now, you can simultaneously apply for certain local business loans and community development products without ever leaving the interface. That's the seamless part. The integration happens through shared APIs between their consumer banking stack and their community development lending division, which used to require separate applications and completely different onboarding flows. I remember dealing with a client who wanted to set up automated charitable giving through their checking account while also applying for a small CDFI loan. Back when these systems operated independently, we spent three days bouncing between portals. Now it takes maybe twenty minutes if everything lines up.
There's a catch though. The CDFI loan eligibility screening runs in real time through their app, but approval itself can still take five to seven business days because it requires manual underwriting review at the regional level. The digital integration speeds up the application, not the decision. People confuse the two. If you're applying for something like a homebuyer assistance program tied to community impact lending, make sure you submit documentation ahead of time rather than waiting for the portal to prompt you. Their system will pre-populate fields from your existing account data, but it won't auto-fill supporting documents like income verification or proof of community participation.
Setting Up the Digital Integration Properly
If you're trying to get the most out of their platform, start by linking your primary checking and savings accounts within the app. Then navigate to the Community Impact section, which sits alongside standard account management tools. From there you can enable automatic contributions to designated community development funds and set up alerts for when new local lending opportunities become available. The automatic contribution feature has a quirk worth noting. It defaults to a flat percentage of your available balance each month, which sounds convenient until you realize it recalculates based on your minimum daily balance rather than your ending balance. I've seen people accidentally drain accounts because they had pending transactions that hadn't posted yet. Set it to a fixed dollar amount instead and adjust quarterly. Much safer.
Get the Full Details
Common Pitfalls and Where the System Breaks Down
The platform works well for straightforward personal banking and standard community loan applications. It falls apart when you try to combine multiple product types in a single session. I encountered this with a client who wanted to apply for both a small business SBA loan and a personal line of credit at the same time. The system would crash mid-submission roughly half the time because the compliance check runs against both applications simultaneously and creates a race condition in the backend. The workaround is to submit them separately with at least an hour between attempts. Another issue is the community impact reporting dashboard. It looks polished but the data refreshes on a thirty-day delay for certain program types. If you're tracking your contributions for tax purposes, don't rely solely on what the dashboard shows. Export your transaction history directly from the account statements and cross-reference. The portal will sometimes display projected rather than actualized community lending disbursements, which threw off a client's Q3 estimates by nearly twelve percent last year. If you're looking for something more granular than what Truist offers, particularly around real-time community development impact tracking, you might need to supplement with a third-party platform. Their API documentation lists available endpoints for partners, but individual consumers don't get access to those feeds. Some financial consultants use Plaid alongside Truist's platform to pull transaction-level data into their own tracking tools, though that requires additional setup and carries its own compliance considerations.
What Actually Makes Sense Here
The integration between digital banking and community impact lending is genuine progress for a regional bank of this size. Most institutions keep those functions in completely separate divisions with no shared infrastructure. Truist has built actual connectivity between them. The execution isn't flawless and there are enough rough edges that you need to pay attention to what you're signing up for, but the underlying architecture is solid. Use the automated contribution feature for steady giving. Avoid combining applications in a single session. Export your own records for tax and planning purposes. Don't trust the dashboard numbers without verifying against actual statements. And if you hit a wall with a specific product combination, call the community lending desk directly rather than submitting and resubmitting through the app. They can often push the application through manually in cases where the automated system times out or rejects it on a technicality.