Tricare for Life is Medicare plus supplemental coverage, but the transition is where people get burned
Most retirees think signing up for Medicare is automatic and that Tricare will just pick up the slack without them doing anything. That is wrong, and it is the single biggest source of problems I see on this forum. You have to actively enroll in Medicare Part B before your Tricare for Life benefits activate. If you skip that step because your employer coverage seemed fine, you will be paying out of pocket for everything until you figure it out. I ran into this exact situation with a colleague in 2019. He turned 65, kept his federal employee health plan thinking it covered everything, and assumed Tricare would automatically switch. It did not. When his wife needed dialysis, the provider billed him directly because his T4L enrollment was incomplete. The fix took about three weeks of phone calls and a lot of paperwork. Do not let this happen to you.
Tricare4life Separating Fact From Fiction In Military Healthcare Rumors
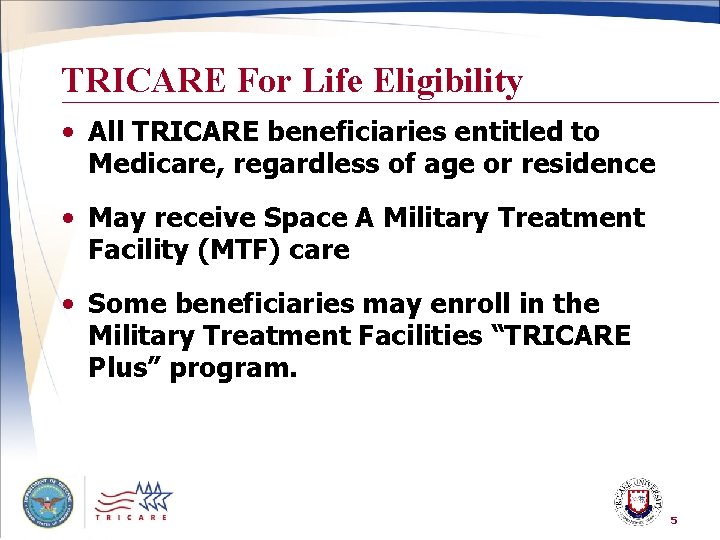
There is a lot of noise in veteran communities about what Tricare for Life actually covers, and much of it is outdated or fabricated. Let me separate the real policy from the ghost stories. Rumor: Tricare for Life covers everything after Medicare pays its share. Partial truth. T4L acts as a secondary payer to Medicare, meaning it covers most of the costs that Medicare does not pay, such as deductibles, copayments, and coinsurance. However, there are limits. Tricare does not cover services that Medicare explicitly excludes, like long-term custodial care, most dental services, or routine vision care for adults. If you need dentures, Tricare will not pay for them just because you are enrolled in T4L.
Rumor: You must use Medicare providers exclusively once enrolled in T4L. This is more complicated than people think. T4L beneficiaries can still see non-Medicare providers in some cases, but reimbursement rates drop significantly. A urologist who does not accept Medicare assignment might bill you at 150% of the standard rate, and Tricare's allowable amount may not cover the difference. The practical workaround I use is to always confirm provider participation before scheduling. Call the provider's office and ask specifically whether they participate in both Medicare and Tricare for Life, not just one or the other. Rumor: Tricare for Life premiums are free, so there is no downside.
Get the Full Details

Premium-free Part A is true for most military retirees, but Part B has a monthly premium that adjusts based on your income. For 2024, the standard Part B premium is $174.70 per month, and high-income beneficiaries pay substantially more. If you have multiple retirees in your household all drawing on the same VA or federal benefits, this adds up quickly. I recommend running the numbers through the TRICARE cost estimator tool before making assumptions about total out-of-pocket costs.
The enrollment process and common pitfalls
Getting T4L set up correctly requires attention to timing. Your Medicare eligibility date matters more than your Tricare retirement date. If you delay Part B enrollment beyond your Initial Enrollment Period without qualifying for a Special Enrollment Period, you will face late enrollment penalties that last for as long as you have Medicare coverage. The 72-hour rule is another area where confusion reigns. After a military retiree completes their DD Form 214 and retires, there is a 72-hour window to transition from Tricare Prime or Standard to T4L without losing continuous coverage. Miss that window and you may have a gap that leaves you responsible for any medical bills during the uncovered period. I witnessed a case where a retiree's transition was delayed because their spouse's employment paperwork had not processed, resulting in a 11-day coverage gap that cost them approximately $2,400 in emergency room charges.
What Tricare for Life does not cover (and what to do about it)
Being transparent about gaps builds trust. T4L will not cover: prescription drugs unless you enroll in a Medicare Part D plan, routine eye exams for glasses, most dental procedures, hearing aids, or long-term care beyond 90 days in a nursing facility. The Part D gap, commonly called the "donut hole," affects T4L beneficiaries just as it affects anyone with Medicare prescription coverage. You should enroll in a Part D plan during your Initial Enrollment Period or face potential penalties similar to the Part B late enrollment fee. For dental coverage, consider purchasing a separate supplemental policy or using the Federal Dental and Vision Program (FDVP) if you are a federal retiree. The FDVP offers discounted rates but does not provide comprehensive coverage like a traditional dental insurance plan would. I found that combining FDVP with a discounted dental membership plan from a local provider saved me roughly $800 annually compared to attempting to navigate Tricare's limited dental benefits.
The VA overlap question
Many retirees assume they can use Tricare for Life and VA healthcare simultaneously without conflict. You can, but the billing order matters. When you receive care at a VA facility, Tricare for Life is the secondary payer. When you see a community provider who accepts Medicare, Medicare pays first and Tricare pays second. This distinction is critical because VA facilities may not process Tricare claims, leaving you to submit paperwork yourself for reimbursement. I encountered an edge case where a beneficiary received chemotherapy at a VA hospital and was billed by Tricare because the VA facility did not have the proper cross-over processing agreement in place. The resolution required filing a manual claim through the Tricare regional contractor, which took approximately six weeks and required detailed documentation from both the VA and the treating physician. Always confirm with both facilities before starting treatment how claims will be coordinated.
Bottom line recommendations
Enroll in Medicare Part A and Part B when you first become eligible, even if you have other coverage. Verify provider participation in both Medicare and Tricare for Life before scheduling appointments. Enroll in Part D to avoid gaps in prescription coverage. Keep copies of all claims and correspondence. And do not rely on information you find in casual conversations on forums, social media groups, or at VFW halls without verifying it against the official TRICARE website or speaking with a TRICARE representative directly. The system works as designed, but only if you understand the design. Most of the problems I see discussed here stem from avoidable enrollment mistakes or outdated information being passed around as current policy. Take the time to get it right the first time.