Starting With the Obvious Thing First
TreasuryDirect is the U.S. Department of the Treasury's official platform for purchasing and managing direct-issue securities like savings bonds, T-bills, notes, and bonds. It is not a scam. It is a government website. It is also genuinely frustrating to use, and the reviews you see online mostly come from people who expected it to work like a modern fintech app. I have been managing savings bonds through this system for over a decade. I am not going to pretend it is elegant. What I can tell you is how it actually works, where it trips people up, and when you should consider alternatives.
Treasurydirect Is It Legit A Deep Dive Into Reviews And Your Guide
The legit part is straightforward. TreasuryDirect is run by the Bureau of the Public Debt, which is now the Bureau of the Fiscal Service under the Department of the Treasury. Every security you buy through it is backed by the full faith and credit of the United States government. There is no counterparty risk in the traditional sense. The money goes to the government, the government owes you the money, and they pay on schedule or at maturity. Period. The review complaints usually cluster around three things. The website design has not fundamentally changed since the early 2000s. Customer service response times are slow during peak periods. And the paperless system can create problems when you need physical documentation for a estate transfer or a loan application.
What You Actually Buy and How the Mechanics Work
Let me skip the basic definitions and go straight to the parts people get wrong. Savings bonds come in two main flavors: Series EE and Series I. EE bonds are bought at face value and double after 20 years if held. I bonds earn a composite rate that adjusts semiannually based on inflation. Both stop earning interest after 30 years. Both are subject to federal income tax, exempt from state and local tax. If used for qualified education expenses, the interest may be tax-free under certain income limits. Here is something most people do not realize: you can reinvest your I bond interest into a new I bond automatically at redemption. This is not obvious from the main dashboard. You have to set it up in your account preferences, and it only applies to bonds with interest that has not yet been redeemable for penalty purposes. If you miss this, you are leaving money on the table every six months when the rate resets.
Get the Full Details
T-Bills work differently. They are sold at a discount and mature at face value. A 52-week T-bill might cost you $970 and pay you $1,000 at maturity. The difference is your interest. These show up on your TreasuryDirect account just like bonds, but the purchase flow is separate. You place a competitive bid or accept a noncompetitive bid at auction. Noncompetitive bids are guaranteed allocation up to $10 million, which covers pretty much everyone reading this.
The Registration Problem Nobody Warns You About
When you open a TreasuryDirect account, you create a username and password, link a bank account, and verify your identity with your Social Security number, mailing address, and date of birth. The verification usually takes one to three business days. Sometimes longer if the system flags something unusual, like a name mismatch between your bank account and your government ID. I hit this once. My bank account was under my maiden name. TreasuryDirect had my current legal name. The system locked my account for manual review. I spent five business days on hold with customer service before they resolved it. The workaround was simple but not advertised: call them first, explain the name change, and send a scanned copy of your marriage certificate or court order through their Secure Message Center. Do not wait for them to lock you out. Fix it proactively if you have ever changed your name. Another registration quirk: you can designate a beneficiary using the payable-on-death feature. But if you die without updating your beneficiary after a life event, the bond goes to your estate and gets probated. That is slow. Get the beneficiary designation done before anything happens. The form is BD 401, available in your account under help documents.
The Paper Trail Issue
This is the biggest practical downside of TreasuryDirect, and it deserves its own section because it catches people off guard. Your bonds exist electronically. There is no physical certificate unless you specifically request one, which costs $1 per bond and takes six to eight weeks to arrive by mail. Most people never request paper certificates, which means they have no tangible proof of ownership beyond a website login. If your account gets frozen, hacked, or locked for some reason, you cannot walk into a bank or mail a certificate to a lawyer. You are entirely dependent on the TreasuryDirect system being operational. I learned this when I needed to prove bond ownership for a qualified tuition program distribution. My account was temporarily suspended due to a security flag. I could not access my holdings for four days. In that time, I had no way to generate a PDF statement fast enough to meet the deadline. The workaround: print your ownership summary from the account dashboard and notarize it. The IRS and most financial institutions will accept a notarized TreasuryDirect printout as valid proof. Keep a current copy in a fireproof box. Do this annually.
What the Reviews Get Wrong and Right
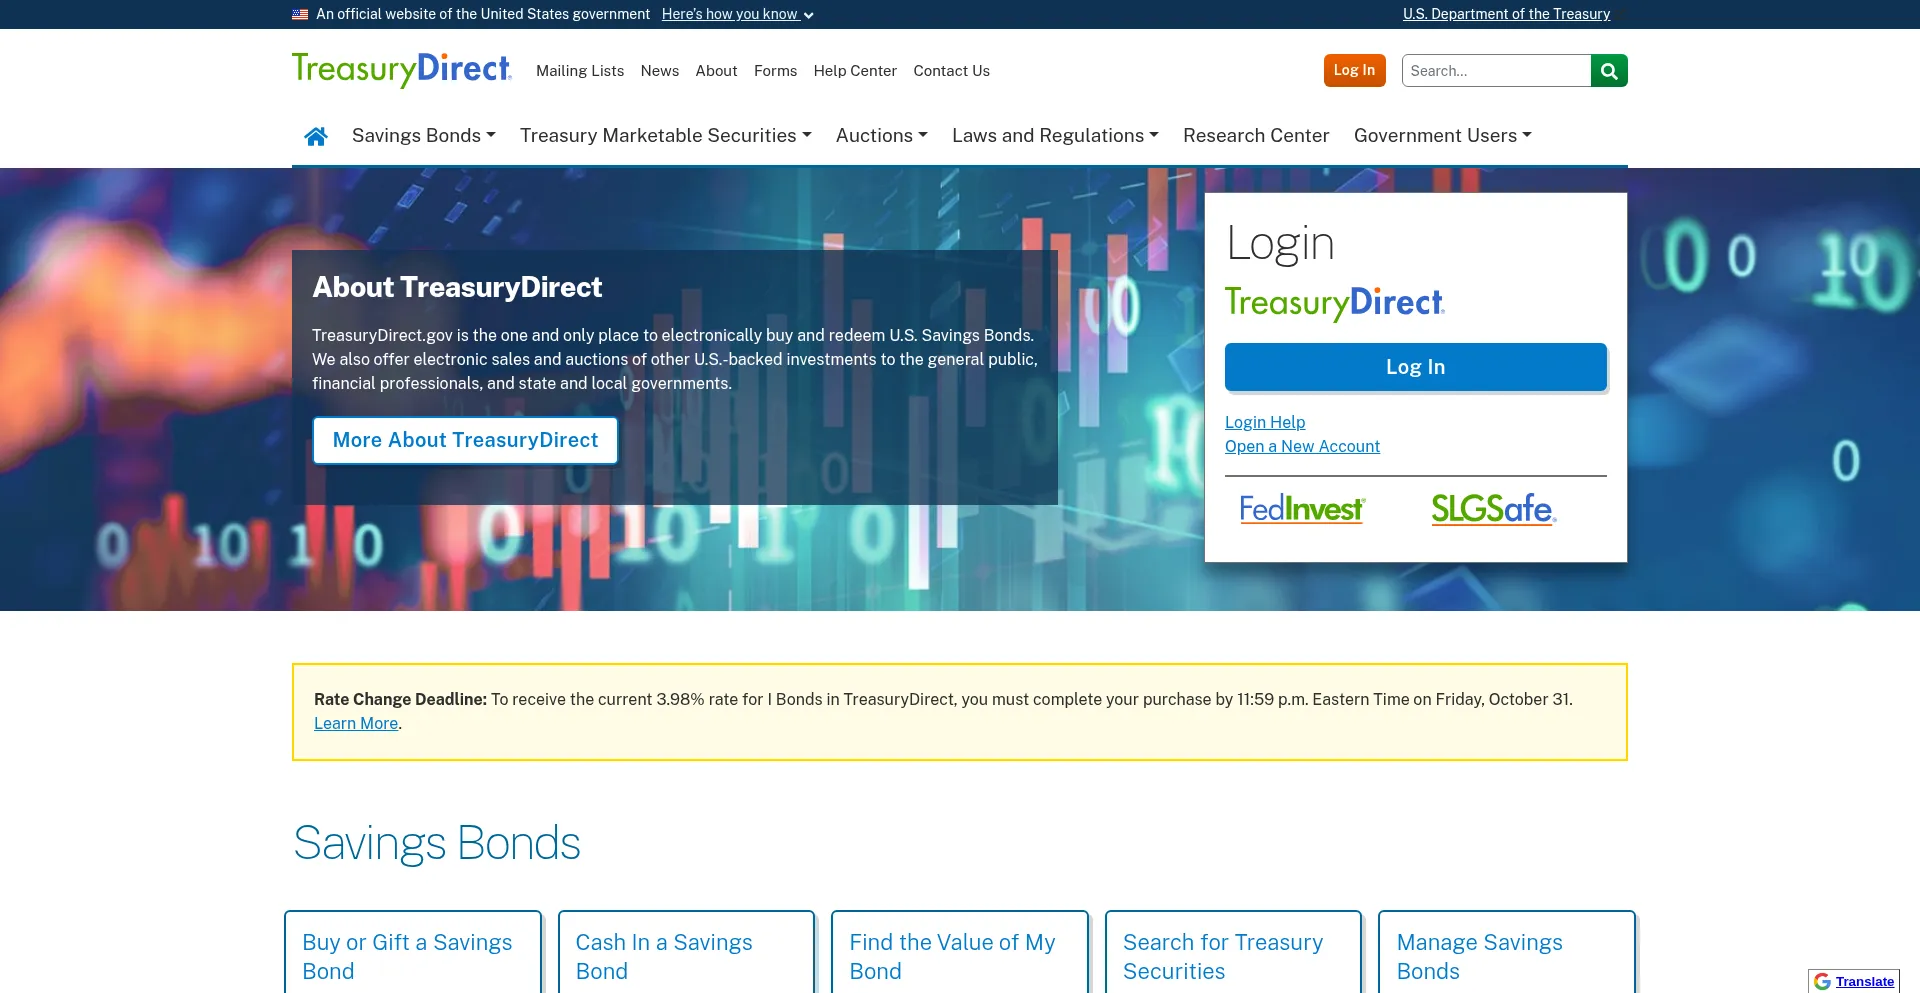
One-star reviews typically complain about the interface. Two-star reviews complain about customer service. Three-star reviews are usually from people who do not understand the tax implications. Four and five-star reviews come from people who know exactly what they are buying and have no expectations beyond that. The interface complaint is valid. The site is functional, not intuitive. Navigation is inconsistent. Search functionality is weak. You can find what you need if you know where to look, but you will not discover features you do not already know exist. The help section is surprisingly thorough, though written like government documentation from 2003. The customer service issue is real but seasonal. Call volumes spike in April around tax season and in October around the I bond rate announcement. Response times during those windows can stretch to two weeks for email and four hours for phone hold time. Outside of those periods, you can often reach a representative within 20 minutes. Plan your calls accordingly.
Purchase Limits and Strategies
EE and I bonds have annual purchase limits. For paper bonds bought with a tax refund, the limit is $5,000 per SSN per year. For electronic bonds bought through TreasuryDirect, the limit is $10,000 per SSN per year. You can buy both types simultaneously, bringing your total to $15,000 per person per calendar year. Married couples each get their own $15,000 limit, so $30,000 combined. Here is a nuance most guides miss: you can buy up to $5,000 in paper I bonds using your tax refund even if you have already maxed out your electronic I bond purchase for that year. The paper and electronic limits are separate. Use this if you are filing a refund and want to maximize your bond purchases. There is also a gifting limit. You can buy up to $10,000 in electronic bonds per year per individual as a gift. The recipient must have a TreasuryDirect account. You transfer the bonds to their account and they become the owner. This is a legitimate strategy for funding a child's future education or emergency savings, and it does not trigger gift tax reporting until you exceed the annual exclusion amount, which is $18,000 per recipient in 2025.
When TreasuryDirect Is the Right Tool and When It Is Not
TreasuryDirect is appropriate if you want zero credit risk, tax advantages, and do not mind a clunky interface. It is appropriate if you are buying savings bonds for long-term goals like a child's education or retirement supplementation. It is appropriate if you want to set up automatic purchases and forget about them for years. TreasuryDirect is not appropriate if you need liquidity. Savings bonds cannot be redeemed in the first 12 months without a five-month interest penalty. If you redeem between years 1 and 5, you lose the last three months of interest. After five years, there is no penalty. T-bills have their own maturity schedules and you cannot sell them early except through the secondary market, which is not accessible through TreasuryDirect for most individual investors. If you need easier access to your money, a brokerage account offering Treasuries may serve you better. Firms like Vanguard, Fidelity, and Schwab let you buy T-bills, notes, and bonds through their platforms with interfaces that actually work. The downside is that you pay a small spread or commission, and you do not get the same tax-exemption advantages on state and local taxes for bonds held in a taxable brokerage account. TreasuryDirect remains the only way to buy paper savings bonds with a tax refund and the most straightforward platform for series EE and I bond purchases with full federal tax deferral.
Security Practices You Should Actually Follow
Enable two-factor authentication. TreasuryDirect offers it through their mobile app. Do not skip this. I have seen accounts compromised through phishing emails that looked exactly like TreasuryDirect notifications. The fake emails use the same color scheme and logo. They ask you to verify your account by clicking a link and entering your credentials. The link goes to a fraudulent site. Once they have your username and password, they can transfer bonds to a different account or close yours. Keep your login credentials in a password manager. Do not reuse passwords from other sites. Do not write your password on a sticky note near your computer. These sound obvious but the account recovery process is so tedious that prevention is infinitely preferable to cure. Recovering a compromised account can take 30 to 60 days and requires mailing signed forms with notarized signatures.
The Bottom Line
TreasuryDirect is legitimate. It is the official U.S. government channel for direct-issue securities. It is also poorly designed, inconsistently supported, and unforgiving when you make mistakes. Use it for what it does well: long-term savings bond purchases with full government backing and favorable tax treatment. Avoid it if you need a smooth user experience or immediate liquidity. And for the love of whatever you pray to, set up two-factor authentication and keep your beneficiary designations current. The official website is treasurydirect.gov. There is no app download required. Everything is browser-based. Bookmark it. Do not search for it every time you log in, because you will eventually click a phishing link if you Google the URL.