Transferring From BCA to OVO: What Actually Works in 2024 and Beyond
Most people figure this out the hard way. You open the BCA mobile app, tap on the e-wallet transfer option, enter the OVO number, and then you're staring at a processing screen wondering if the money actually moved or if your phone just glitched. The whole flow isn't as smooth as the marketing makes it look, and the fees change often enough that by the time you read about them, they've already shifted again. Here's the straightforward breakdown of how the transfer actually works, what it costs right now, and which apps give you the least headache doing it.
Transfer Bca Ke Ovo Cek Biaya Admin Terbaru Aplikasi Yang Perlu Anda Tahu
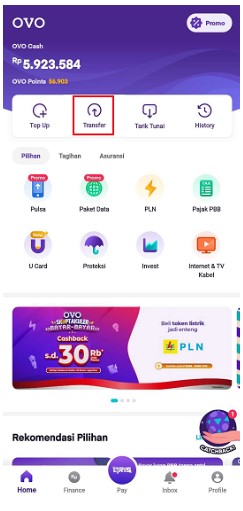
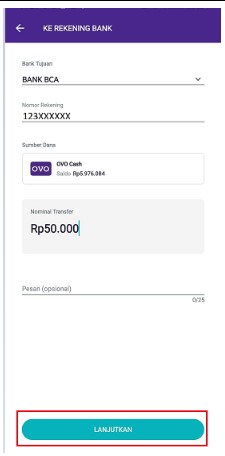
The primary route is through the BCA mobile app itself, either m-BCA or myBCA. Both support direct transfers to OVO via the Bill Payment and Transfer section, selecting OVO as the destination. The standard fee sits around Rp1,500 to Rp2,500 per transaction, depending on whether you're a regular account holder or a KlikBCA business user. Some accounts with certain promotional packages get it waived entirely for the first few months. Don't assume you know your fee tier without checking the actual confirmation screen before you hit submit every time. I learned this the hard way last year when I was trying to move about Rp500,000 from my BCA savings into OVO for an emergency payment. The app showed the transfer as successful, but the money didn't appear in OVO for over six hours. Turns out I'd selected the wrong transfer channel — I hit the "Realtime" option thinking it was instant, but the system routed it through BI-FAST instead of the Instant Transfer path. The money got stuck in a holding queue between BCA's settlement batch and OVO's reconciliation process. Workaround was simple: I called BCA customer service, confirmed the reference number, and within twenty minutes OVO credited it. The lesson is to always double-check the transfer channel label on the confirmation page before you walk away from your phone. The second route most people use is through the OVO app itself. You can initiate a top-up from within OVO by linking your BCA account. This method sometimes shows slightly different fee structures because OVO absorbs part of the processing cost to incentivize top-ups. During promotional periods, OVO has offered zero-fee top-ups from select banks including BCA, though these promotions come and go without much warning. Check the OVO homepage banners — the fee waiver information is usually there, buried under flashing animations you'd easily scroll past.
A third option that works well but gets overlooked is using mobile banking aggregator platforms like Flip or DOKU. These sit between your BCA account and OVO, charging a small convenience fee on top of the base transfer cost. The advantage is speed and sometimes better fee transparency. You can see the exact total deduction before confirming, which is more than you get from some of the direct bank routes where fees get tacked on at the last step without clear disclosure. Biaya admin — the admin fee — is the part most people get confused about. There are actually three different fee layers here. First, BCA charges its own outbound transfer fee. Second, OVO may charge a receiving fee depending on the top-up method. Third, intermediary platforms add their own markup. When you transfer directly through BCA to OVO, you're usually only seeing the BCA fee. But if you use an aggregator, that total fee can be 30 to 50 percent higher than the direct route. It matters when you're moving small amounts regularly. There's a common pitfall that trips up a lot of people: transferring to an OVO account that hasn't been fully verified. If the recipient OVO account only has a phone number registered but no KTP or full identity verification, the transfer will go through but the money goes into a restricted balance that you can't withdraw or spend freely. I've seen friends lose access to thousands of rupiah because they transferred to a newly created OVO account that hadn't completed verification. Always confirm the OVO account is fully verified before sending any meaningful amount. A quick way to check is to look at whether the account holder's name appears correctly on the confirmation screen before you finalize.
Get the Full Details
Another thing nobody mentions enough: the transfer limits. BCA typically caps e-wallet transfers at around Rp10 million per day for regular accounts, but this varies by account type and your personal risk profile. If you're trying to move larger sums, split it across multiple days or use a business account. OVO itself has tiered limits based on your verification level — basic accounts can hold far less than fully verified ones. Check your OVO limit in Settings before you try to top up a large amount, because getting rejected mid-transfer is frustrating and wastes your time. For the most current fee information, don't rely on third-party blogs. Those articles are usually three months out of date by the time you read them. Instead, check the official BCA website's fee schedule page or open the m-BCA app and navigate to the tariff section. The numbers are right there, updated whenever the bank changes them. Similarly, the OVO help center has a fees page that lists current top-up charges by bank. These sources update faster than any article someone writes about them. The timing of your transfer also affects whether it actually reaches OVO quickly. Transfers initiated during banking business hours — roughly 8 AM to 4 PM on weekdays — process through the real-time channels and hit OVO within minutes. Transactions submitted late at night or on weekends often queue up for the next business day's processing cycle. This isn't always obvious from the app, which may show a generic "processing" status regardless of when the money will actually land. If you need the funds in OVO urgently, do the transfer during weekday business hours and verify the confirmation shows a real-time processing indicator.
One more practical note about receipt and record-keeping. Both BCA and OVO generate transaction records, but they don't always align perfectly. BCA's app will show your debit with a reference number. OVO's app will show the credit with its own internal ID. Keep both screenshots if you're doing anything that requires proof of payment — employment reimbursements, business expenses, or large personal transfers. I've had to produce both records when a transfer discrepancy came up, and having them side by side made the resolution much faster.