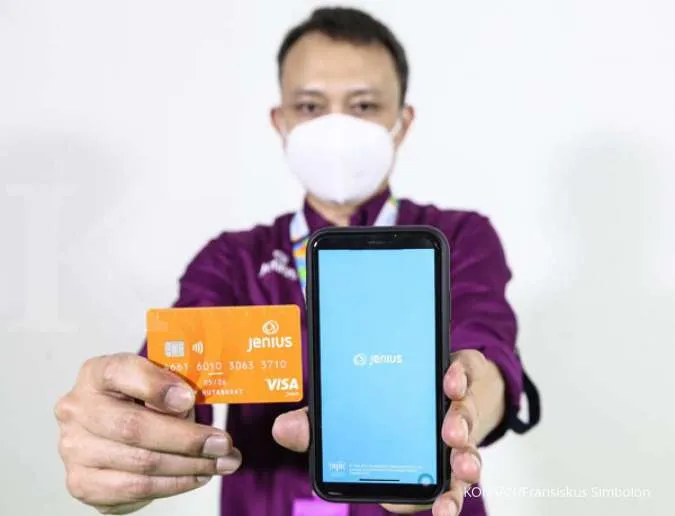
Using Jenius Abroad: What Actually Happens
You've landed in Bangkok or Bali, you need to pay for a ride or grab dinner, and your phone is your wallet. That's where Jenius comes in, but the app wasn't exactly designed for cross-border use, so things work a bit differently than you might expect. I've been using this setup for about three years across Southeast Asia and Europe, and the learning curve is steeper than the marketing material suggests. The core mechanic is simple enough. You open the app, select "Pay" or "Top Up," and scan a QR code or enter a merchant terminal. Jenius connects through their partnership network, usually via Visa or Mastercard networks, and processes the transaction in the local currency. The conversion happens on the spot at whatever rate Jenius is quoting at that moment. It's not the best rate you'll find, but it's passable for small purchases. The first thing most people mess up is not understanding how the currency conversion works. When you swipe or tap your card abroad, you're not using your Rupiah balance directly. The app pulls funds from your account, converts them at their internal rate, and sends the foreign amount to the merchant. That rate includes a margin. I've seen it range from 1.5% to 3% depending on the currency pair and the time of day. Checking the exact rate before you commit to a purchase is something you should get into the habit of doing. Tap the transaction preview screen and look for the conversion details. It's buried but it's there.
Another detail people overlook is the daily transaction limit. Jenius imposes limits based on your account verification level. A basic verified account might only allow you to spend around 5 million Rupiah per day on international transactions. If you're traveling with a group and splitting bills, or if you need to cover a hotel deposit, you'll hit that wall fast. The workaround is to pre-fund your account before you leave and make sure you understand your limit tier. You can check this in the app under account settings, though the information isn't always prominently displayed. I ran into a specific problem last year in Manila. I was trying to pay at a mall merchant terminal, and every time I entered my PIN, the transaction would timeout. The terminal accepted the card details fine, but the authorization kept failing. What I eventually figured out was that the terminal was routing through a network path that Jenius doesn't always support reliably in that region. The workaround was straightforward: I switched to paying at the register instead, where the cashier manually keyed in the card details rather than using the chip reader. That path seemed to use a different routing and went through without issues. It's not a solution I recommend relying on everywhere, but it saved me from standing awkwardly at a checkout counter for twenty minutes. There's also the issue of ATM withdrawals. You can use your Jenius-linked debit card at ATMs abroad, but the fees add up quickly. Jenius charges a flat fee per withdrawal, and then the local ATM operator slaps on their own surcharge. In Japan, for example, I've seen ATM fees hit 1,500 Yen on top of the conversion margin. If you're going to withdraw cash, do it in larger amounts less frequently rather than small withdrawals every time you need money. One 50,000 Yen withdrawal costs you the same flat fee as three separate 17,000 Yen withdrawals, but the latter three times your ATM surcharges.
Online bookings are another area where things can go wrong. I once tried to book a train ticket on a European website and the payment was declined. Not because I didn't have funds, but because the transaction was flagged by Jenius's fraud system. International online transactions, especially from unfamiliar merchant domains, trigger their security algorithms. The fix was calling customer service, which I did through the in-app chat feature. They unblocked it within about ten minutes, but the delay meant I missed the booking window. Always carry a backup payment method when you're booking travel online from abroad. A secondary card or even cash for deposits is not optional if you want to avoid this scenario. One counter-intuitive thing about using Jenius internationally is that keeping a small balance in the foreign currency account, if your tier supports it, can sometimes be cheaper than converting on the fly. The on-demand conversion rate includes that margin I mentioned, but pre-converting when rates are favorable locks in your cost. The problem is timing the market, which most people don't do well. A practical middle ground is to convert a set amount before you travel, enough for your first few days, and then let the rest convert as needed. That way you're not stuck without local currency if the app has an outage, and you're not over-converting at potentially bad rates either. The biggest bottleneck with this whole setup is connectivity. Jenius needs an active internet connection to process transactions, and roaming data can be unreliable or expensive. I've been stranded at coffee shops with no signal and a full cart of items because my transaction couldn't go through. Having offline payment options or knowing which merchants accept cash as a fallback is essential. In practice, I keep about 20% of my expected spending in local cash at all times. It's a small buffer that has saved me more than once.
Get the Full Details

If you're relying heavily on card payments abroad and you're doing this regularly, you might want to look at alternatives like Wise or Revolut. Their conversion rates are noticeably better, often closer to the interbank rate with lower fees. Jenius is convenient if you already have the account set up and don't want to manage another app, but for frequent international travelers, the cost difference adds up over time. I use both. Jenius for quick small purchases where convenience matters, and a dedicated travel card for larger transactions where the rate matters more. The app itself has gotten better over the years. The transaction history is clearer now, and they've added more explicit currency conversion displays. But the fundamentals haven't changed. You're trading convenience for slightly worse rates and occasional routing hiccups. If that's acceptable for your travel style, it works fine. If you're spending significant amounts regularly, the math starts to favor other options.