The Payment Infrastructure at Tractor Supply Matters More Than You Think
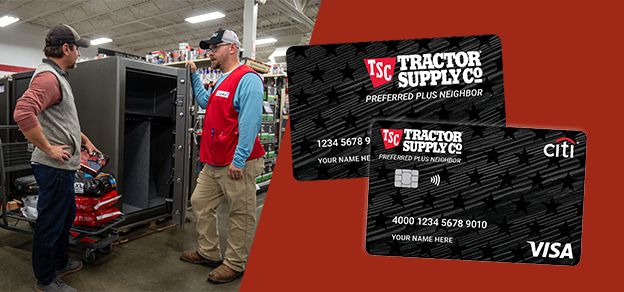
I have spent years watching supply chains move at farm speeds, which means I know how much time gets lost when purchasing equipment breaks down. The checkout process at Tractor Supply is not glamorous, but it sits at the center of how farmers and ranchers acquire things ranging from replacement tractors to feed-grade hardware. Understanding the mechanics of Tractor Supply Payment Options Revolutionizing Farming Ecosystem With Convenient Checkout is useful for anyone who runs operations out of rural locations where waiting around for financing approvals costs more than the equipment itself. Tractor Supply operates a hybrid payment environment that merges in-store point-of-sale systems with an online fulfillment network. When you purchase something in person, the terminal accepts standard credit and debit cards alongside their own branded store card and a PayFlex financing arrangement. The online portal supports the same methods plus gift cards and promotional financing tied to seasonal equipment sales. What makes this worth examining is the reconciliation layer between those two channels. The store card, often called the TSC Credit Card, functions as both a traditional revolving credit line and a discount vehicle. It is issued through Comenity Bank, and the approval timeline typically runs two to five business days for a first-time applicant. Existing cardholders face no such delay. The PayFlex option sits on top of that as a deferred interest product, and the mechanics of that are where most people get tripped up. Deferred interest means that if you do not pay the full balance within the promotional window, the interest charges apply retroactively to the original purchase date, not just the remaining balance. This is not a trick specific to Tractor Supply. It is a standard feature of retail installment plans, but it catches people off guard because the marketing language usually highlights the zero-percent window without drawing equal attention to the retroactive clause.
Where the System Shows Its Teeth
Let me walk through a scenario that is not theoretical. I was outfitting a small cattle operation with fence posts, wire, and a replacement water tank. The tank had to be special-ordered through the online system because the local store had none in stock. The purchase total pushed past the threshold where standard credit would have triggered a credit limit concern. I chose the store card and qualified for a promotional financing window. The order confirmation came through, but the delivery window listed seven to ten business days, which is standard for BOPIS or home delivery of bulky items. The problem arrived when the fencing materials were available for immediate pickup at the store but the tank was still in transit. Tractor Supply's system does not split shipments automatically unless you request it during checkout. I ended up making two separate trips because the initial order bundled everything under a single tracking number. The workaround was calling the store directly and asking them to hold the in-stock items at the pickup counter while the special-order piece came in. They agreed, but only if I kept the original order intact. The alternative would have been canceling the entire order and reordering, which resets the fulfillment clock entirely. That is the kind of operational friction that matters when you are trying to run a working ranch on a Tuesday afternoon. This is where the broader idea of Tractor Supply Payment Options Revolutionizing Farming Ecosystem With Convenient Checkout becomes relevant. The convenience is not just about swiping a card faster. It is about whether the payment method integrates smoothly with the fulfillment logic. When they launched features like Buy Online Pickup In Store and the mobile app with digital wallets, the intent was to compress the time between decision and possession. That compression works well for consumables and small hardware. It works less well for mixed orders containing bulky special-order items, which is a significant portion of what livestock operations purchase.
Gift Cards and Promotional Financing: The Edge Cases
Gift cards at Tractor Supply carry no fees and can be applied toward any purchase, including special orders. They function as a hard currency within the system, which makes them useful for budgeting seasonal expenses. The limitation is that you cannot use gift cards to satisfy the minimum purchase required for certain promotional financing offers. If you are financing a $500 tillage part through a deferred-interest plan, the system requires a card on file that meets the promotional threshold. A gift card alone will not qualify you for that window. This is by design and it is consistent across most retail financing programs, but it is worth knowing before you assume your balance will cover the full requirement. Promotional financing also interacts poorly with returns. If you purchase an item with deferred interest and then return it partially, the promotional clock does not pause. You are still responsible for clearing the original balance within the agreed timeframe, or the retroactive interest applies to the remaining amount. I have seen this bite people who returned defective equipment without realizing the financing terms were locked to the transaction date, not the return date.
Get the Full Details

The Tech Stack Behind the Checkout Experience
Tractor Supply runs a distributed POS architecture that ties together approximately 2,000 stores with an e-commerce backend. The integration between the two is driven by SAP-based inventory management, which feeds real-time stock levels into the online ordering system. When you select a payment method online, the authorization passes through a third-party gateway before committing to fulfillment. In-store checkouts route through a different path that does not always share the same validation rules. This mismatch occasionally causes issues when you attempt to apply an online-promoted discount at a physical register, or vice versa. The TSC app has become the primary interface for many repeat customers. It stores payment methods, tracks orders, and provides access to digital coupons. The app does not always sync with in-store promotions in real time. I have walked into a store with a coupon displayed in the app only to find the register system could not locate it because the promotion had already expired offline. The workaround is straightforward: print the coupon or show the barcode on your phone and ask the cashier to look it up manually. Most clerks will accommodate this, but it adds a step that defeats the purpose of digital convenience.
What Does Not Work Well and When to Pivot
The payment system at Tractor Supply is functional but not seamless. The biggest weakness is the lack of automatic partial shipment logic for mixed orders. If you need five items and three are in stock while two are special-ordered, the system holds everything until the special items arrive unless you intervene. This is not a payment issue in the narrow sense, but it is a fulfillment issue that payment routing decisions affect directly. Another gap is the absence of real-time financing pre-qualification on the website. You can check your credit score through third-party tools, but Tractor Supply does not offer a soft-pull pre-approval widget. That means you enter the checkout flow without knowing whether your financing application will be approved, which is inconvenient when you are trying to budget a seasonal purchase. For operations that need financing clarity before committing to a purchase, the alternative is to contact the store directly and request a manual estimate. Store managers can sometimes pull preliminary terms based on your purchase range and past relationship with the location. This is not a formal pre-approval, but it gives you a working number. It is also worth noting that for large equipment purchases above $1,000, contacting the agricultural equipment department directly may yield better financing terms than the standard retail checkout flow, since those transactions sometimes fall under different promotional brackets.
Practical Recommendations for Routine Purchases
If you are buying consumables like feed, tack, or small hardware, the fastest path is in-store with the TSC card or a standard debit transaction. The checkout flow takes roughly three to five minutes per transaction, and you walk out with the items immediately. For larger equipment orders, plan ahead by placing the order online and selecting pickup or delivery at your convenience. If you are using financing, verify the promotional terms before completing checkout and confirm whether the purchase qualifies for deferred interest or a flat discount rate. Keep receipts organized by category, especially if you are tracking expenses for tax purposes at year-end, because the online and in-store systems generate different receipt formats that do not always merge cleanly in a single export. The broader shift toward integrated payment and fulfillment options is real. Tractor Supply has moved from a purely in-store model to a hybrid that mirrors how e-commerce retailers operate. The convenience gains are measurable for routine purchases, but the system still contains friction points around mixed orders, financing transparency, and cross-channel promotion synchronization. Knowing where those pinch points sit lets you work around them instead of being slowed down by them.