Financing Farm Equipment Through Tractor Supply's Citibank Card
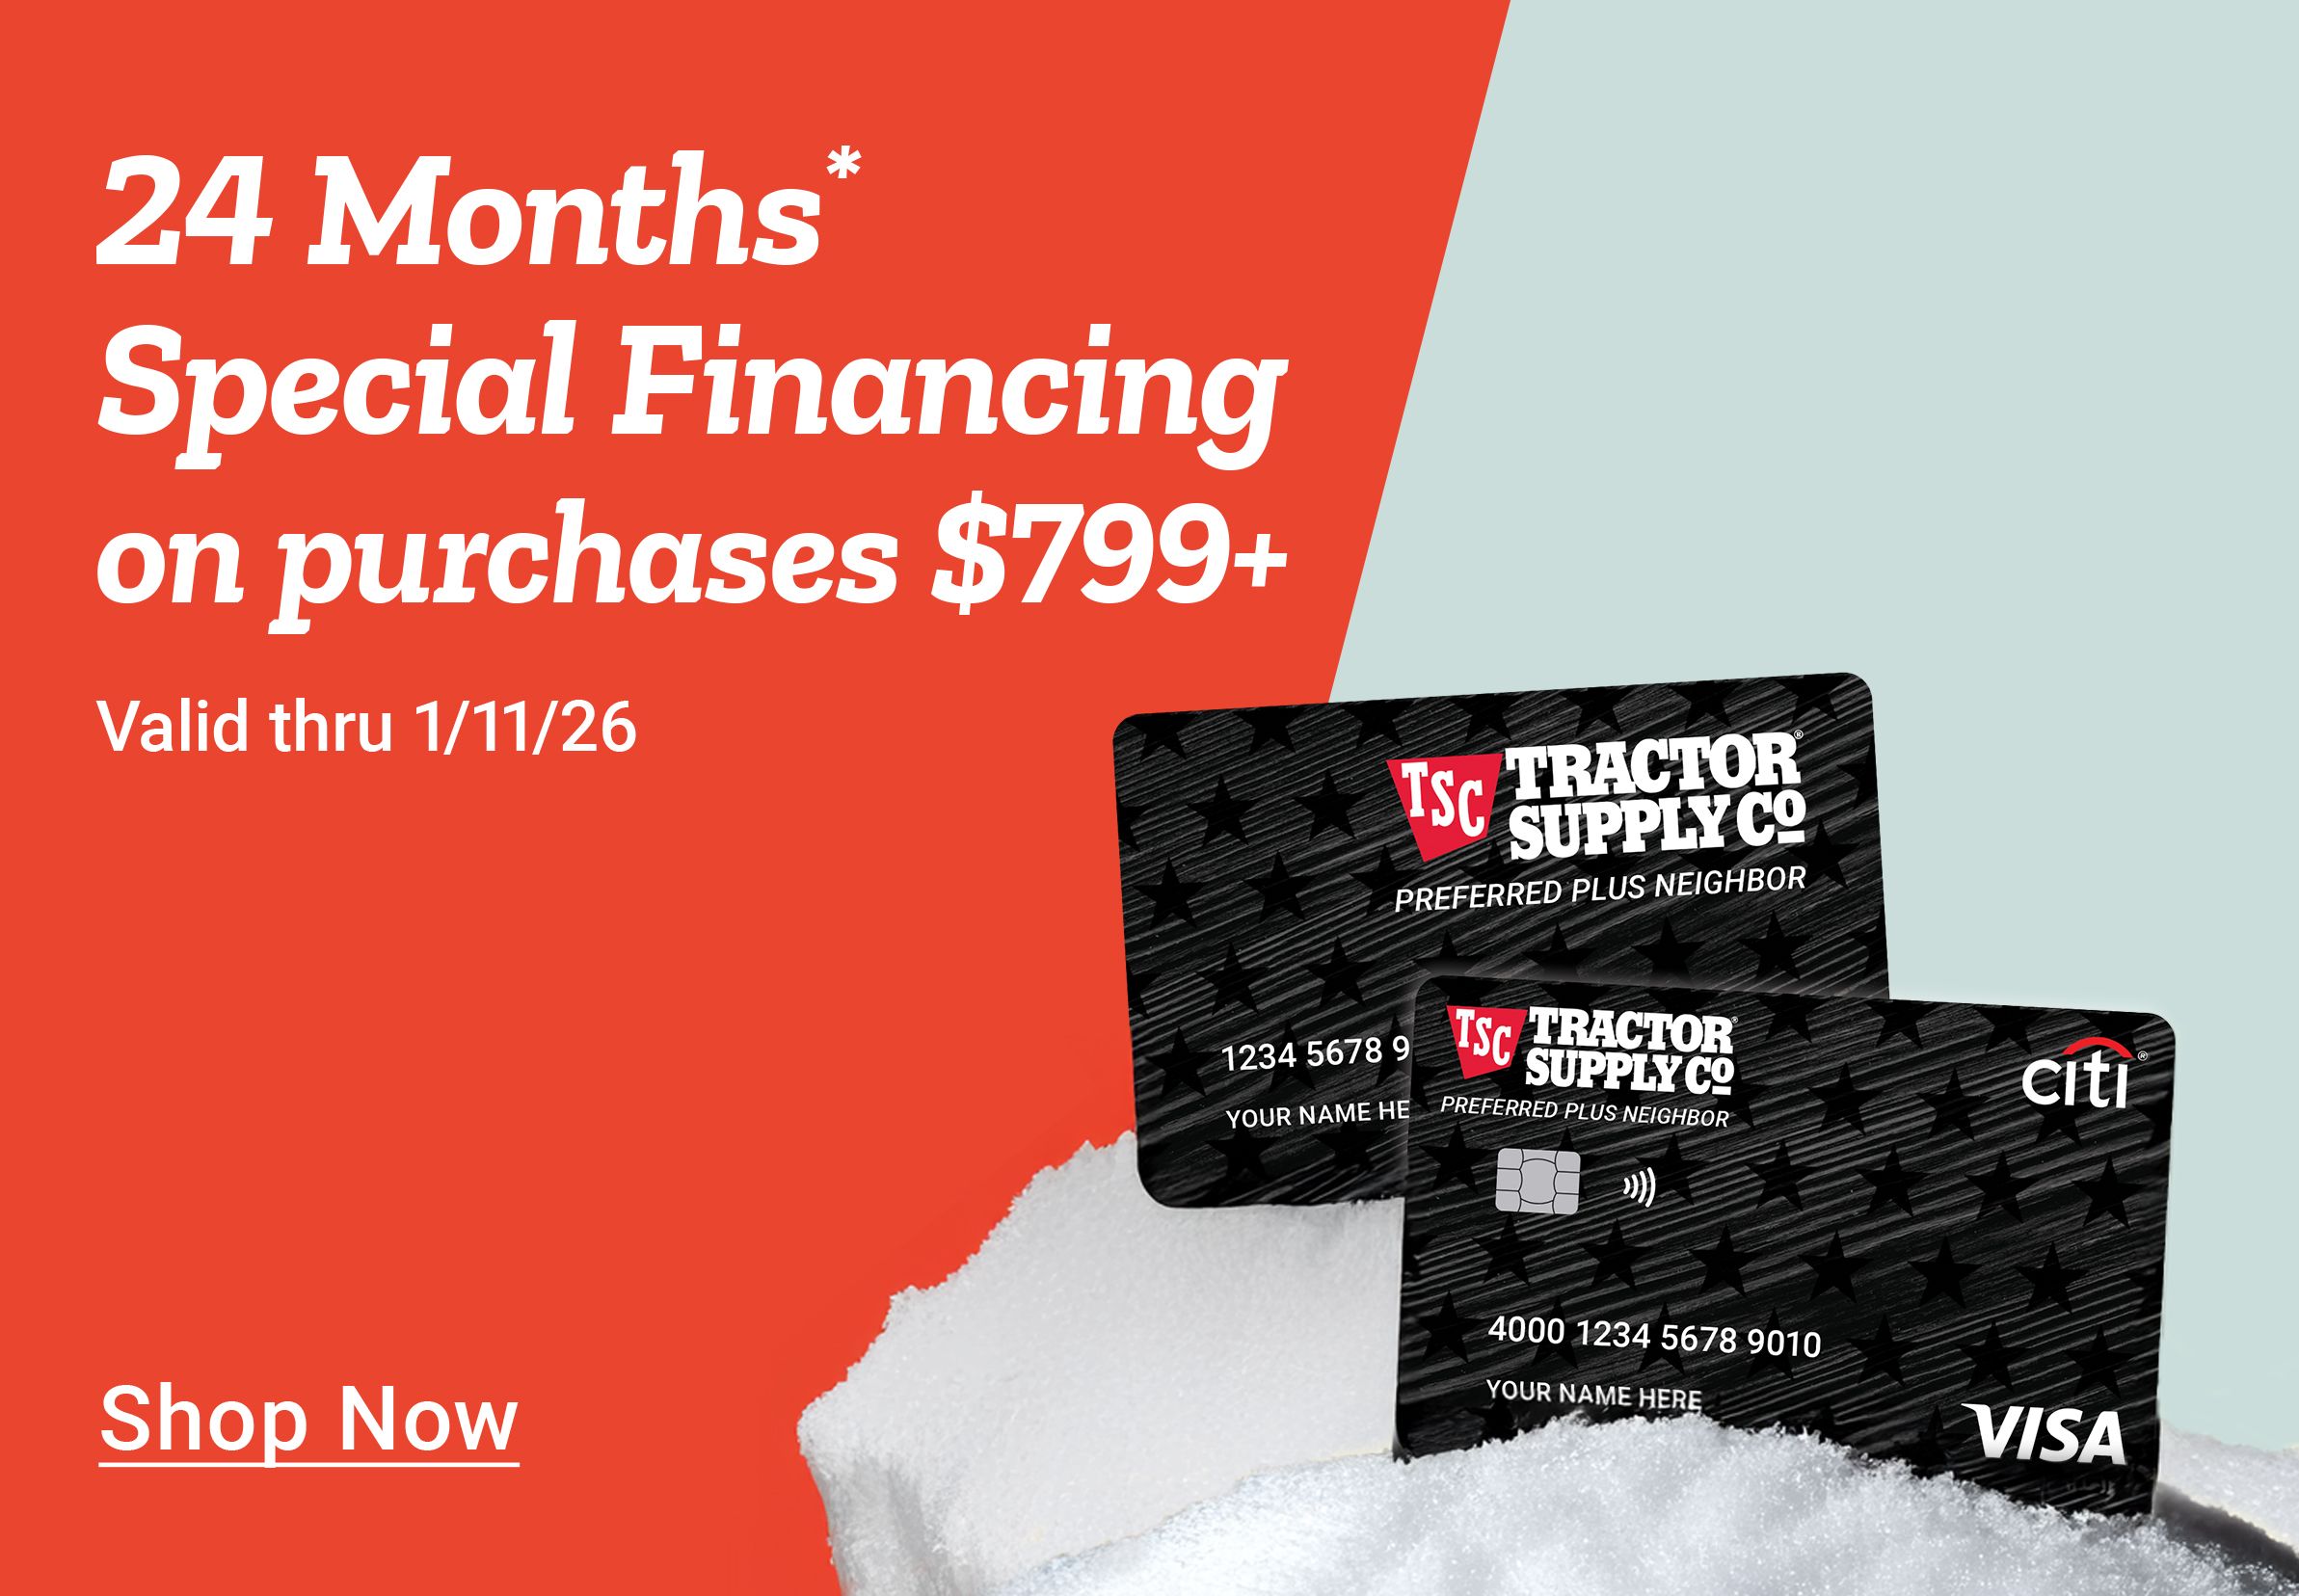
The Tractor Supply Co. Credit Card is issued by Citibank, N.A. and it is one of the more common ways people finance equipment and supplies at Tractor Supply stores. I have applied for it, used it, and watched people do the same thing repeatedly over many years. Most of them get it right. Some of them miss things that end up costing them money. How the card actually works. You apply online or in-store at a Tractor Supply location. It is a store-branded credit card, meaning it is only usable at Tractor Supply and on their website. The approval process is usually fast. Many people get a decision within minutes, and if approved, they receive either an immediate card number or a physical card in the mail within a week or two. The credit limit is set based on your creditworthiness and income, same as any other retail card. The standard rate is around 29.99% APR on purchases, which is on the higher end for retail credit cards. However, Tractor Supply frequently runs promotional financing offers. The most common one is deferred interest on purchases of a certain amount over a set period, like 6 or 12 months. If you pay off the full balance before the promotion ends, you do not owe any interest. If you even miss a payment or carry a balance past the deadline, all the interest from the original purchase date gets backdated and charged at once.
I learned this the hard way with a well pump system. I put a $1,847 pump setup on the card during a 12-month deferred interest promotion. I made every payment on time. Then I switched banks mid-year, missed one payment window by three days because the due date shifted on my calendar, and the entire deferred interest clause kicked in. They charged me roughly $350 in back interest on the full purchase amount. Three missed days turned a manageable payment plan into a bill that could have been handled with a personal loan at a much lower rate. Never underestimate how aggressive deferred interest clauses are. What the card is good for. It works best for smaller, short-term financing needs where you can pay it off within the promotional window and you are confident in your payment discipline. If you are buying feed, fencing materials, or tools and you know you can clear the balance in six months, the deferred interest offer is genuinely useful. It saves you money compared to paying full price upfront while keeping your cash available for other things. It is also worth noting that Tractor Supply occasionally offers exclusive discounts for cardholders. These are not always advertised prominently. Sometimes you get a percentage off your first purchase, or a discount on certain brands of equipment. If you already shop at Tractor Supply regularly, even without a financing need, the card can accumulate savings over time just through those recurring discounts.
What it is not good for. Do not use this card for large purchases you cannot pay off within the promotional period. That deferred interest clause is the single most dangerous part of this card. I have seen people finance tractors, ATVs, and major renovations through it, then get stuck paying 29.99% APR on a balance they cannot move quickly enough. At that rate, a $3,000 purchase can cost you significantly more than $3,000 if you are only making minimum payments. Minimum payment calculations on Citi retail cards are typically 1% of the balance plus accrued interest, which barely touches the principal. Another issue is that this card reports to all three major credit bureaus, so it does factor into your credit utilization ratio. If you run up a large balance relative to your credit limit, it can temporarily lower your credit score. This matters if you are planning to apply for a farm loan or mortgage in the near future. A sudden spike in revolving debt can be a red flag for lenders. The application process. You can apply at tractor supply.com or inside any Tractor Supply store. The online application asks for your Social Security number, annual income, employment status, and housing information. There is a soft credit check initially, but approval triggers a hard inquiry on your credit report. Multiple applications in a short span will compound the damage to your score.
Get the Full Details
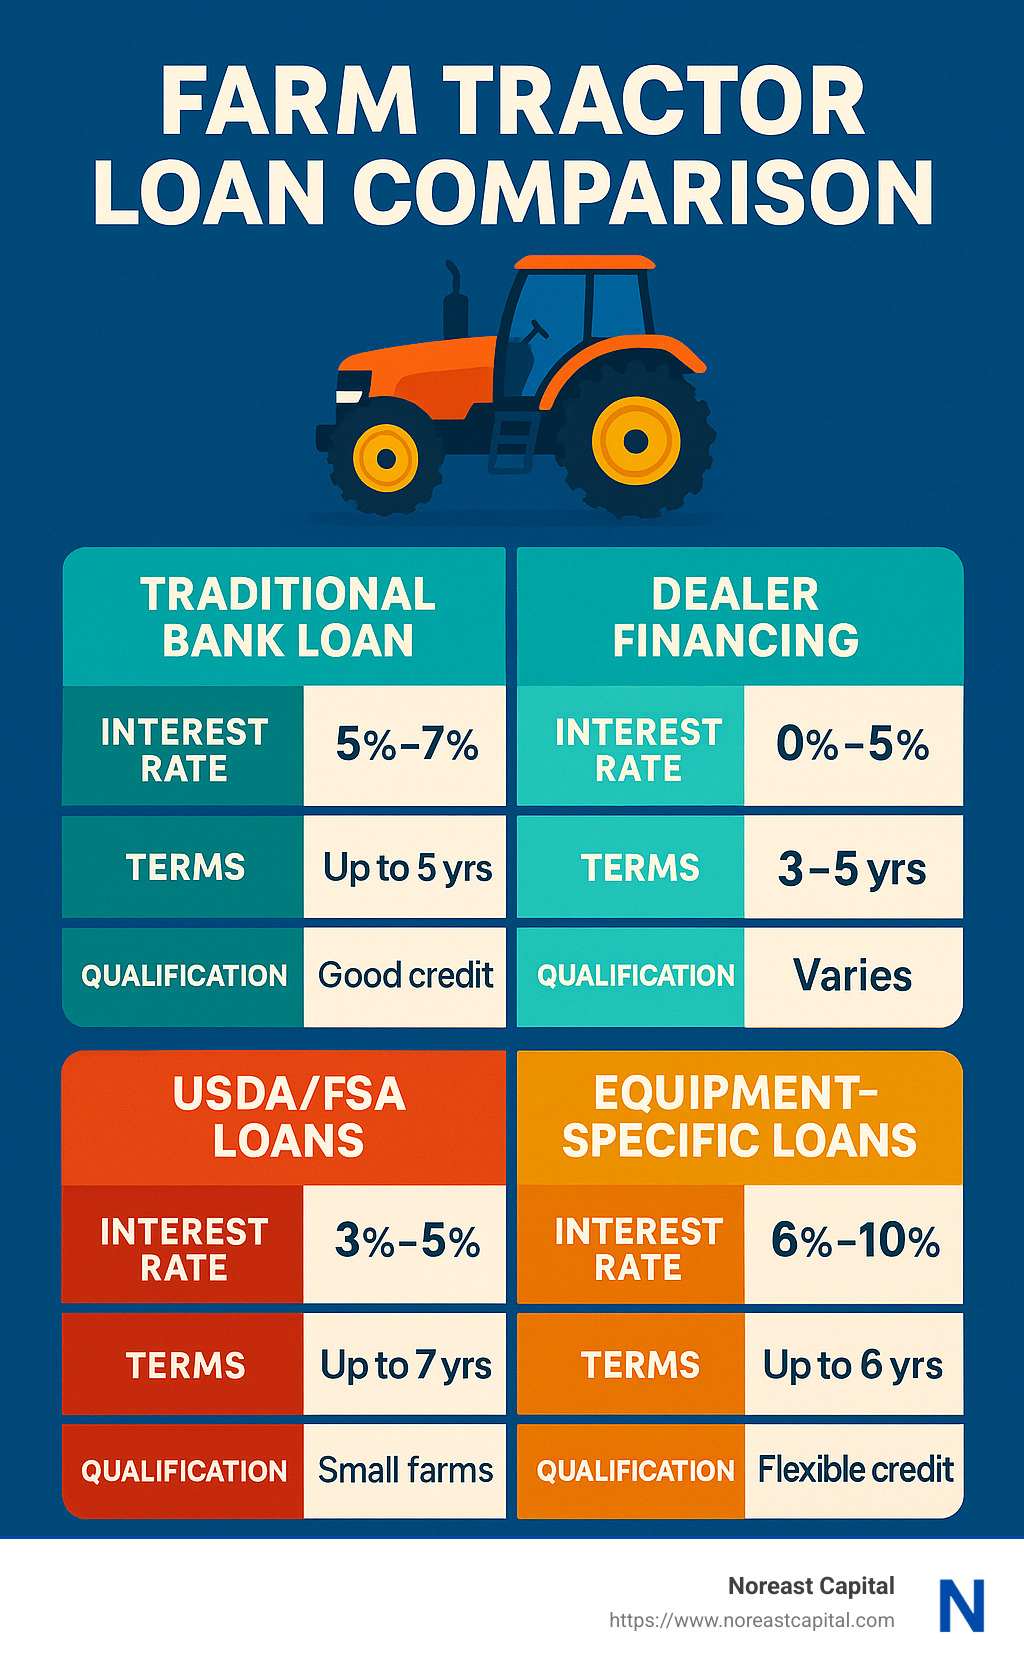
If you are applying in-store, a representative can sometimes pull up instant decisions from their system. This is not always the case. Sometimes you still get a mailed decision that takes several days. The in-store process also gives you the option to look at what you are buying and see if there is a promotional financing offer available at the point of sale, which is helpful for planning purposes. Alternatives worth considering. If you have good credit and are financing a larger purchase, a personal loan from a credit union or online lender will almost always have a lower rate. For example, a $2,500 personal loan at 8% APR over 24 months costs roughly $112 in total interest. The same balance on the Tractor Supply Citi card at 29.99% APR over 24 months costs over $400 in interest, assuming you are even paying it down steadily. The math is not close for anything beyond small, quickly paid-off purchases. A home equity line of credit is another option for farmers who own their property and have equity built up. The rates are substantially lower, and the interest may be tax-deductible in some cases. This only makes sense if you have sufficient equity and the discipline to not treat a HELOC like an unlimited credit card.
Things most people overlook. The card does not offer rewards on purchases. You get no cash back, no points, no travel miles. The only value proposition is the financing offers and the occasional discount. If you are someone who maximizes rewards cards for everything else, this card stands out as a pure utility tool rather than a rewards vehicle. Another overlooked detail is the billing cycle timing. If you make a large purchase right after your statement closes, you typically have until the next statement due date, which could be 30 to 45 days away, to pay it down without interest under a promotional offer. Understanding your statement cycle is important for maximizing the window you have to pay off deferred interest purchases. Customer service for this card is handled by Citibank, not Tractor Supply. If you have an issue with a payment, a dispute, or a billing error, you deal with Citi's support structure. Their phone lines can be lengthy, and resolving billing disputes requires patience. Keep detailed records of every payment and every interaction, including dates, times, and the names of representatives you speak with.
Bottom line on whether this makes sense for you. If you are buying something under a few thousand dollars and you can realistically pay it off within the promotional period, the Tractor Supply Citibank card is a reasonable option. It is convenient, the approval is quick, and the deferred interest offers are legitimate if you follow through. If you are financing something substantial or your financial situation is unstable, the high APR and aggressive deferred interest terms make this a risky choice. Look elsewhere.