Accessing Your Tractor Supply Citi Account
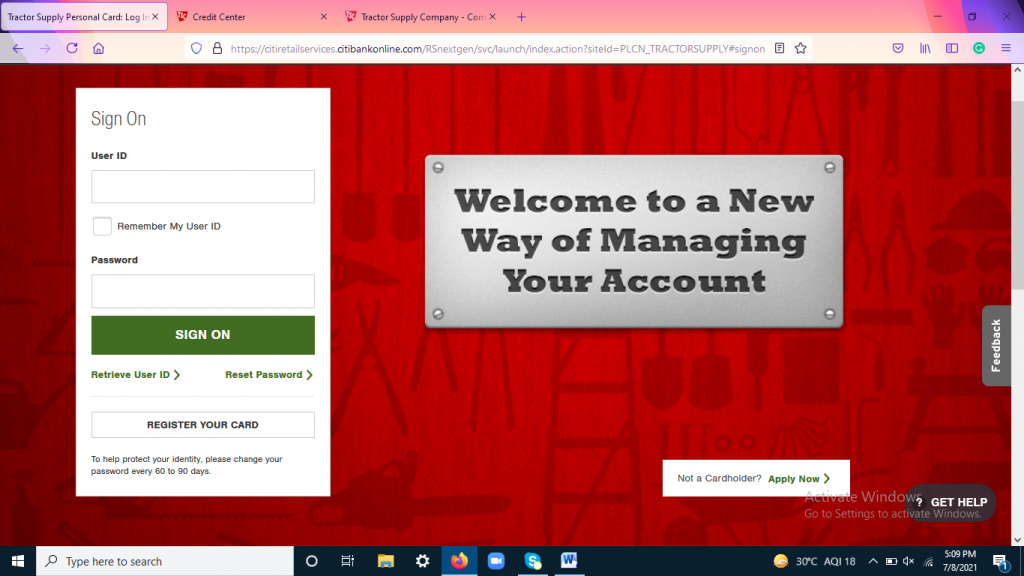
I've been dealing with this portal for about four years now, since my first application came through during a farm equipment purchase. The setup has changed a few times but the core flow stays the same, and there are enough edge cases that trip people up if you don't know what to expect. The portal lives at citi.com/tractor-supply. You can also reach it through the main Citi mobile app if you've already linked the card there. Start by clicking Sign In. If you're a new user, select Register Now below the login box. You'll need your 16-digit card number, your Social Security number, and the zip code on file with the account. That zip code has to match exactly what Citi has registered. I learned this the hard way — when I moved to a new state, I kept trying to log in using my old address, and the system rejected me three times in a row before locking the account for 24 hours. The workaround was calling customer service at the number on the back of my card, verifying my identity over the phone, and having them update my address on their end before I could register again. Takes about 10 minutes on the phone but costs you a full day of being locked out.
Once registered, you create a username and password. Citi requires a password with at least one uppercase letter, one number, and one special character. They also enforce a 90-day rotation now, which most people hate but honestly keeps your account safer than the old policy where passwords never expired. After you sign in, you'll land on the dashboard showing your current balance, minimum payment due, and credit limit. The statement date and payment due date sit at the top right. Clicking My Account Details takes you to a page where you can view transaction history going back 18 months, request duplicate statements, and set up payment preferences.
Understanding Your Financing Options
The Tractor Supply Citi card operates as a store card, which means it's tied specifically to Tractor Supply purchases both in-store and online. This is important because the rewards structure and promotional financing work differently than a general-purpose credit card. Standard APR sits around 26.99 percent variable, which is steep but typical for store cards. The real value comes from periodic promotional offers. Every few months, Citi runs 12-month special financing on purchases over a certain threshold — usually $299 or more. These get pushed to you via email or appear as banners on the portal after you log in. Here's something most people miss about these promotions: the deferred interest clause. If you don't pay off the full balance before the promotional period ends, they don't just charge you the promotional rate. They retroactively apply the standard APR to the entire original purchase amount from the day you bought it. So a $1,200 tractor purchase at 26.99 percent over 12 months would suddenly owe you $324 in interest if you're even one day late on the final payment. I've seen this bite people repeatedly during holiday seasons when balances carry over.
Get the Full Details
The auto-pay enrollment is worth setting up immediately after registration. Go to Payments, select AutoPay, and link your checking account. Even enrolling for minimum payments prevents late fees, which run $41 for the first violation and $42 for subsequent ones. Missing a single payment also gets reported to the three credit bureaus, which drops your FICO score by 60 to 80 points depending on your starting range.
Common Problems and Workarounds
The biggest friction point I keep encountering is the security question system. Citi asks you to create three security questions during registration, and you must answer all three correctly every time you call support or reset your password. I chose questions where I knew I'd remember the answers, but my wife once tried to use her phone to reset the password and got locked out because she didn't know my third security question answer. She had to wait until I came home to finish the reset. It's a minor inconvenience but it adds up when you're in a hurry. Another issue that comes up occasionally: the portal sometimes shows a truncated transaction description for merchant categories. A purchase at a feed store might show up as just a generic merchant code instead of the actual store name. This isn't a system error, it's how Citi categorizes smaller merchants. If you need the exact transaction details for expense tracking or tax purposes, call the number on the back of the card and ask for an itemized transaction record. They'll email it to you within two business days, though it sometimes takes up to five during peak periods. For people managing multiple Citi accounts — the Pet Citi card, the Air Citi card, etc. — each one registers separately on the portal. You can link them under the same login, but you have to add each card individually after your first registration. The process is straightforward but easy to forget, and I've lost count of how many times someone has asked me why their other Citi card doesn't show up. They simply never added it.
What the Portal Can't Do for You
Be aware that the online portal and mobile app don't support every function. You can't dispute a charge, close the account, or request a credit limit increase without either calling customer service or sending written correspondence through their secure message center. The dispute process requires you to submit documentation through the app or by mail, and resolution typically takes 45 to 60 days depending on how complete your evidence is. If you're trying to refinance existing Tractor Supply debt onto this card, you'll need to apply for a balance transfer through the portal, but approval isn't guaranteed. Balance transfers carry a 3 percent fee minimum $5, and promotional rates for balance transfers differ from purchase promotional rates. I've noticed the portal sometimes doesn't display the balance transfer offer clearly alongside purchase offers, which can lead to confusion about which promotion applies to which transaction type. Read the fine print on any promotional banner before assuming it covers balance transfers. The portal does a decent job of giving you visibility into your account, but it's not going to walk you through the financial decisions. Understanding how deferred interest works, keeping track of your statement dates, and setting up auto-pay are the things that matter most, and once you have those in place, the portal is just a window into the data rather than a source of friction.