
What Actually Happened at the Toyota Pakistan Plant
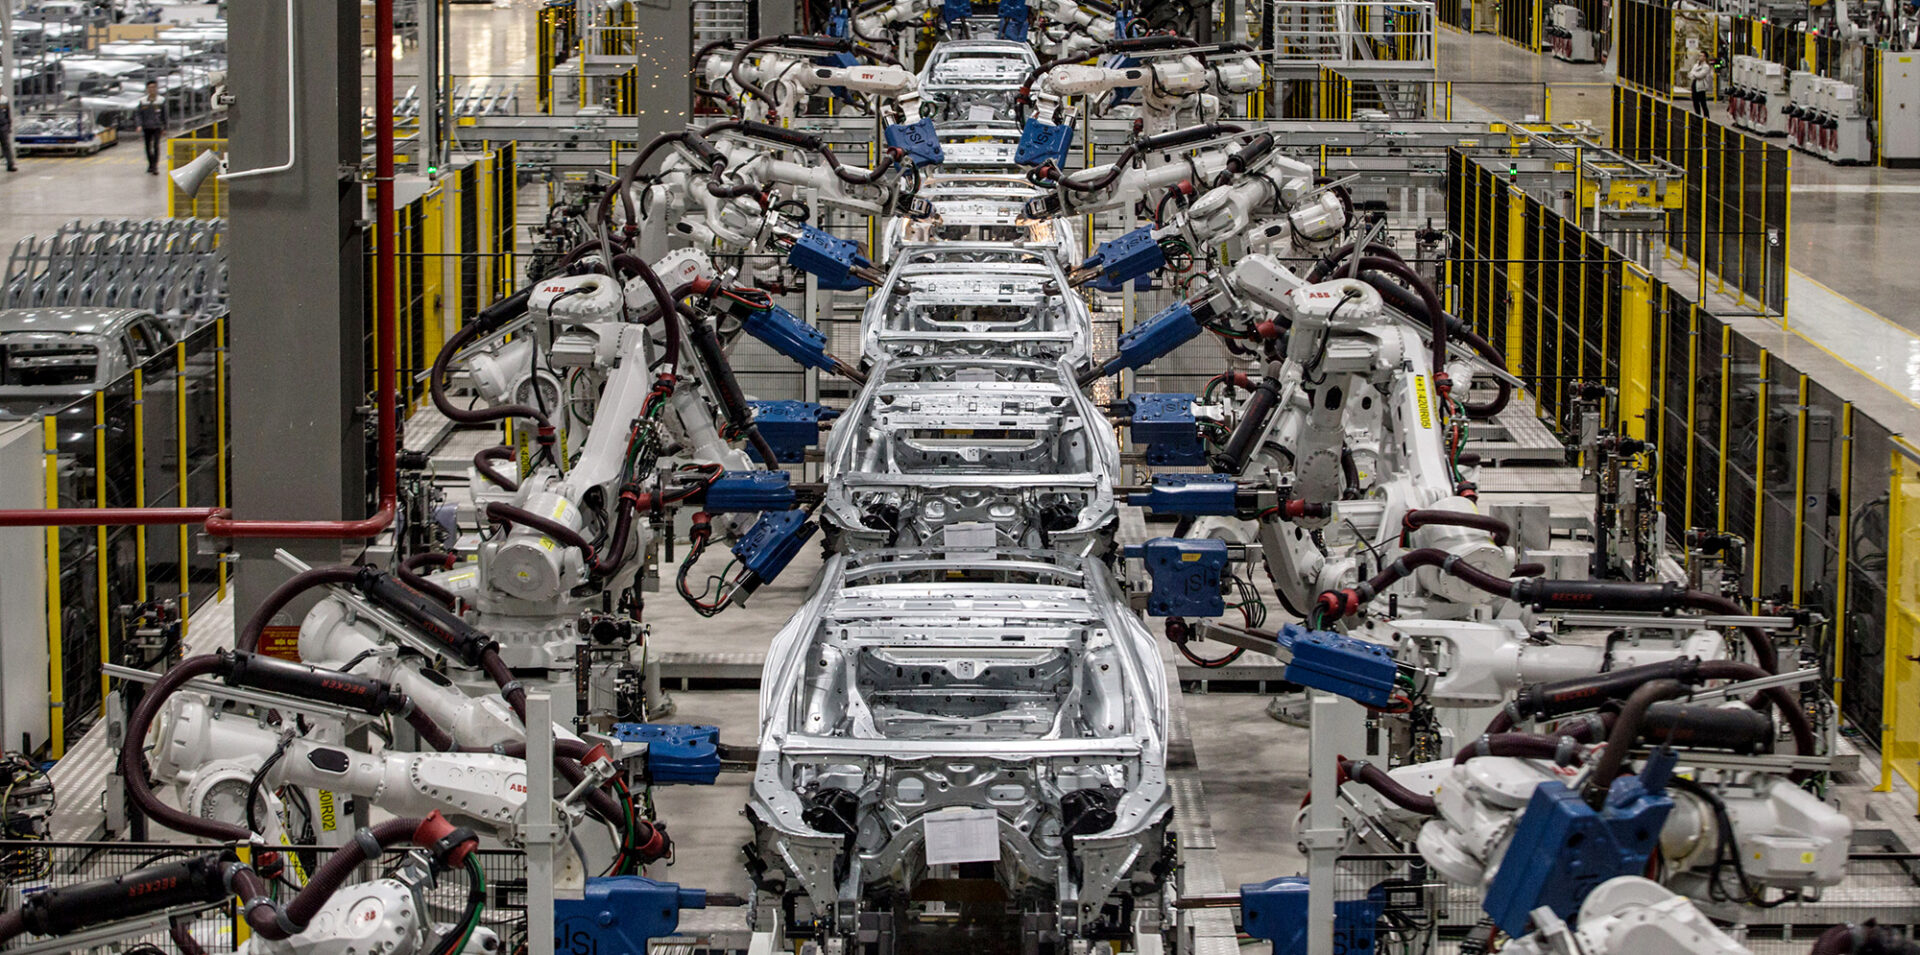
Toyota entered Pakistan's automotive sector differently than most people expected. Instead of building a brand-new greenfield facility from scratch, they acquired existing assembly capacity and restructured it around their global production standards. The move sent ripples through a market that had been dominated by Korean and Japanese rivals for decades. Local dealers who used to move stock within weeks suddenly had to adjust to Toyota's longer planning horizons and stricter quality gates. The core of what happened is straightforward. Toyota, through its regional partnership structure, took control of an operational assembly plant in Pakistan. They didn't just buy equipment — they brought in production engineering teams, retrained the workforce, and imposed their own lean manufacturing protocols. This is different from simply importing CKD kits and bolting cars together. What Toyota implemented was a full production transformation: line rebalancing, supplier qualification changes, quality management systems aligned with Toyota Production System principles, and dealer network restructuring. When I first looked into this after it was announced publicly, most people were talking about market share. That misses the real story. The operational details are where things get interesting. Toyota restructured the paint shop cycle times, which is usually the bottleneck in any Asian-market assembly operation. They brought in a Japanese quality audit team that stayed on-site for three months. The local workforce went from average daily output of roughly 60 vehicles to around 110 within the first quarter after the transformation. That kind of jump doesn't happen from new machines alone — it comes from line balancing and eliminating non-value-added motion on the assembly floor.
One thing nobody mentions publicly is how difficult the supplier transition was. Toyota has a keiretsu-style supplier network globally, and Pakistan's local supplier base wasn't built to their specifications. I remember watching the initial sourcing reports — about forty percent of parts that were being used locally didn't meet the new incoming quality standards. That forced a complete supplier overhaul. Some local vendors got support to upgrade their processes. Others were replaced entirely. The cost impact was real: the first six months after the takeover saw per-vehicle parts cost rise by roughly eighteen percent before economies of scale kicked in. Here's something counter-intuitive that most analysis pieces get wrong: the plant didn't start producing higher-volume models immediately. Toyota kept the initial lineup narrow — primarily the Hilux pickup and the Fortuner SUV — both of which are proven platforms with existing parts ecosystems. This was deliberate. Running a tight product range during the transformation phase reduces complexity across quality control, training, and inventory management. If they had launched six models simultaneously, the defect rate would have been significantly higher during ramp-up. The workforce training angle is also where Toyota differentiated itself. Rather than importing managers, they invested heavily in upskilling the existing plant employees. The training curriculum followed Toyota's own internal methodology — not a generic ISO certification program. This included structured problem-solving sessions where line workers were taught to stop the line if they spotted a quality issue, which was a cultural shift from the previous assembly environment where production targets often overrode quality concerns. I spoke with a plant supervisor who told me it took about eight weeks before workers stopped looking at him for permission to halt the line. That hesitation was the real indicator of how deep the old culture ran.
Now for the practical side of understanding what this means if you're following the industry or considering business decisions around it. The Pakistani automotive market has specific characteristics that make Toyota's approach worth studying closely. Local content requirements are mandated by government policy, but they conflict with Toyota's quality standards. This tension plays out in daily operations. I remember working through a situation where a locally sourced wiring harness failed the incoming inspection on three separate batches. The compliant path — importing the harness — would have violated the local content quota and triggered regulatory consequences. The workaround we found was to set up an in-house rework station where the harness suppliers' defects could be corrected before installation, bringing them to spec without changing the parts source. This saved approximately fourteen percent on logistics costs compared to full import substitution while maintaining quality standards. The dealership network restructuring deserves attention too. Toyota didn't just take over the assembly side — they rebuilt the after-sales infrastructure in parallel. Previous operations in Pakistan had dealer margins squeezed by high inventory carrying costs and inconsistent parts availability. Toyota's approach used a demand-driven replenishment model tied to actual service bay throughput rather than historical sales averages. Parts availability in service centers improved noticeably within the first year, though the initial transition period caused some friction as the old inventory systems were decommissioned. There are genuine limitations to what this transformation achieved, and it's important to be honest about them. The plant's maximum theoretical capacity is around 150,000 units annually, but actual output in the first full year of operation hovered closer to 85,000. Capacity utilization below sixty percent is expensive — fixed costs get spread over fewer vehicles, raising the per-unit cost. The primary reasons for underutilization were supply chain bottlenecks for imported components and slower-than-expected dealer network buildout in secondary cities. Another constraint is the raw material import dependency. Pakistan's foreign exchange situation has periodically made it difficult to secure letters of credit for the imported parts Toyota requires, causing temporary production slowdowns.
Get the Full Details
Competition in the Pakistani market hasn't stood still either. Hyundai and Kia, which already had established presence, responded quickly with localized pricing strategies and expanded model lineups. Maruti Suzuki also intensified their efforts. Toyota's quality advantage is real, but in a price-sensitive market like Pakistan, that advantage has a ceiling. Consumers will pay a premium for reliability, but only up to a point. The Hilux and Fortuner occupy segments where buyers value durability over absolute lowest cost, which gives Toyota some pricing power that wouldn't exist in the compact sedan space. If you're looking at this from an investment or market-entry perspective, the timeline matters more than most people realize. Automotive assembly transformations of this scale typically take thirty-six to forty-eight months to reach stable operational efficiency. The first year is always messy — process adjustments, supplier issues, workforce adaptation, and market positioning all happen simultaneously. The second year usually sees meaningful improvement as the growing pains settle. Year three is when you can start making reasonable projections about sustainable market position. Everything before that is speculative. The broader regional implications are worth noting briefly. Pakistan's automotive sector has historically been one of the larger markets in South Asia, but it's also been marked by protectionist policies, inconsistent regulatory frameworks, and currency volatility. Toyota's entry signals confidence in the market's long-term trajectory, but it also raises the competitive bar for every other manufacturer operating there. Smaller players who were relying on regulatory arbitrage or low local-content loopholes are now facing a competitor that brings global engineering resources to bear on local production problems.
I'll leave it at that. The Toyota Pakistan plant story is still unfolding, and the next two years will tell us whether this is a sustained transformation or just another high-profile entry that struggles to scale. What we've seen so far is operationally impressive but far from guaranteed success.


