
How Toyota Financial Services Actually Works When You Buy a Car
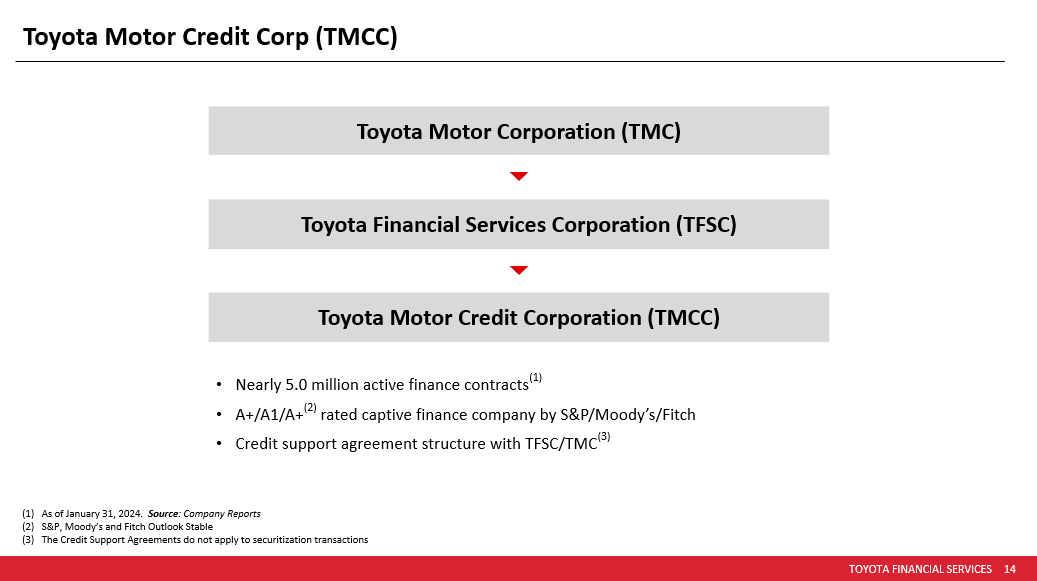
Most people walk into a dealership and get handed a Toyota Financial Services application without really understanding what that company is or how it fits into the purchase. TFS is Toyota Motor Credit Corporation's lending arm, the captive lender that finances the majority of new Toyota and Lexus vehicles sold in the US. It exists to capture the interest margin the manufacturer would otherwise hand to a bank or credit union. Here is what actually happens when you use it, stripped of the sales script.
Toyota Financial Services Tfs Explained The Ultimate Guide To Toyotas In House Financing
You do not apply through a website and get a decision the same day like you would with a credit union pre-approval. The process runs through the dealer's DMS system. The salesperson enters your information, pulls your credit, and submits to TFS's automated underwriting queue. Approval typically comes back in 3 to 15 minutes during normal business hours. If the system flags anything unusual, it routes to a manual review desk and you are waiting 24 to 48 hours instead. I learned this the hard way on a 2022 Tacoma purchase. The deal looked solid on paper. My credit was 742, I had 18 percent equity in my trade, and I wanted 72 months at a rate the finance manager quoted as "under four percent." The system came back with a decline within four minutes. Not a "please provide additional documentation" soft decline. A hard declination. The finance manager looked at me like I had personally offended the algorithm. The issue was not my credit score. It was a collection account from six years ago, a $340 medical debt that had been turned over to a third-party agency and never resolved. It sat on my report as open. TFS's automated overlay rules for their promotional subprime rates simply flag any open collection above $100. The solution was not to argue. It was to call the agency, negotiate a pay-for-delete, get it in writing, and have the dealer resubmit with the updated report. The rate offer changed from the promotional tier to the prime tier. I paid 5.74 percent instead of 3.89 percent. The monthly payment went up about $38. The whole addendum took two business days.
That is the practical reality most guides skip. TFS does not have a single rate sheet. It has tiered approval matrices that shift based on credit profile, loan-to-value ratio, and sometimes even the specific model you are buying. Their best rates are frequently attached to selective model promotions that require scores of 720 or higher and down payments of at least 10 percent. Miss either threshold and the system quietly drops you into a different bracket.
Get the Full Details
What Makes TFS Different From Other Lenders
Captive lenders like TFS have access to manufacturer subvention. This means Toyota can temporarily pay part of your interest rate to move inventory or hit quarterly sales targets. The promotional 1.9 percent or 2.9 percent APR offers you see are rarely profitable for TFS. They are loss leaders subsidized by the dealer group's volume rebate from Toyota Motor Sales. Once the promotion expires, those rates vanish. The current new-vehicle promotional landscape as of mid-2024 sits closer to 3.9 to 5.9 percent for well-qualified buyers on select models. Another structural difference is how TFS handles trade equity. Most banks cap your loan amount at the vehicle purchase price minus your down payment. TFS will roll positive equity from your trade into the new loan up to certain LTV limits, but they also allow negative equity to be financed within constrained thresholds. This is useful when you owe more than your car is worth, but it is also where people get trapped. If you stretch to the maximum negative equity allowance across two or three consecutive loans, you will be underwater for the life of the finance term. I have seen it repeatedly. The gap insurance question comes up constantly. TFS sells gap coverage as part of their F&I products, usually bundled into the loan. The cost runs roughly $400 to $700 depending on loan size and term. An independent policy from your auto insurer typically covers the same exposure for $200 to $350 annually. If you are financing a camry or rav4 and plan to keep it for six years, buying gap separately is almost always cheaper. If you are leasing, TFS includes it by default and you cannot opt out.
The Process Breakdown
You walk in with a negotiated purchase price. The sales team hands you to the finance manager. The FM pulls your driver's license, proof of insurance, and recent pay stubs. They run a hard credit inquiry through one of the major bureaus and submit to TFS. If approved, they present a credit agreement with your rate, term, monthly payment, and any add-on products. You sign. The deal gets sent to TFS's funding desk, which wires payment to the dealer typically within one to three business days. You drive away with the paperwork a week later. If you bring your own pre-approval from a credit union, the dealer is required to match or beat it under the Equal Credit Opportunity Act. In practice, this rarely works the way people expect. The credit union approval came with one rate and one set of terms. TFS may match the rate but will structure the loan differently, often adding mandatory products or adjusting the term to hit a cleaner monthly payment number. The final cost comparison is what matters, not the headline APR. I once watched a customer bring a 4.2 percent credit union pre-approval for a 2023 Highland. The TFS rate match came in at 4.19 percent, which looked better on paper. But TFS required a $699 document prep fee and rolled a $599 paint protection package into the financed amount. The credit union loan had zero fees. The TFS loan added $1,500 to the principal and carried a slightly higher annual percentage rate once you include the fees. The credit union was actually cheaper by about $87 over the life of the loan. The customer signed the TFS paperwork anyway because the monthly payment was $22 lower. That $22 felt good until the third year when they realized they were paying interest on money that covered products they did not need.
When TFS Makes Sense and When It Does Not
Using TFS is sensible when you qualify for an active manufacturer subvented rate on a new vehicle, you have clean credit with no collections or charge-offs, and you want the convenience of handling everything in one building. The paperwork is shorter. The funding is faster. The promotional rates, when available, are genuinely competitive. It makes less sense if you have a blemished credit report, if you are buying a used vehicle outside the CPO program, or if you are comfortable waiting 48 hours for a credit union decision. Credit unions routinely offer lower rates on used cars because they are not subsidizing inventory movement. Their underwriting is also more relationship-based. A loan officer who knows your deposit history and direct deposit pattern can sometimes approve a borrower that TFS's automated overlay would reject. The biggest mistake I see is people treating TFS as the only option they evaluate. They negotiate the car price, then immediately cede all financing decisions to the finance manager. That is when add-on products inflate the cost by $2,000 to $4,000. Get a pre-approval from your bank or credit union first. Use it as leverage, not as a threat. The finance manager will still try to sell you things, but you now have a concrete alternative to reference when they say your rate cannot be improved.

TFS itself is not a bad product. It is a corporate lending engine designed to maximize manufacturer profitability while providing acceptable terms to prime borrowers. Understanding where the engine overlaps with your needs and where it grinds against them is what separates a reasonable purchase from an expensive one.


