Picking Travel Insurance for the Philippines
I spent three weeks in the Visayas last year and had to deal with a medical evacuation from Cebu after twisting my ankle on a hike. The insurance paperwork alone took six hours and multiple phone calls across time zones. After that, I learned enough about the insurance landscape here to know which policies actually work and which ones are just marketing fluff. The standard international travel policy covers you reasonably well in Manila. But take that same policy to Palawan or the Sulu Archipelago and suddenly there are gaps you didn't know existed. Many providers classify the Visayas and Mindanao as "high risk" zones, which means your coverage automatically downgrades unless you specifically add a rider for those provinces. Here's the thing nobody tells you: most policies exclude pre-existing conditions without giving you the option to declare them at purchase. I learned this when my regular prescription medication cost nearly $400 out of pocket in a Boracay clinic because the insurer decided "ongoing treatment" wasn't covered. If you take any daily medication, read the exclusions section before you buy. Not after.
Top Travel Insurance In The Philippines Your Essential Guide To Stressfree Trips
When I say this guide is essential, I mean it practically. Philippine travel insurance has a few quirks that trip up foreign visitors every single day. The biggest one is the hospital network issue. Private hospitals in Metro Manila like St. Luke's and Makati Medical Center will treat you fine if you have direct billing authorization. But step outside the National Capital Region and the network shrinks dramatically. By the time you reach Cagayan de Oro or Iloilo, only two or three hospitals per city have direct claim arrangements with major insurers. Medical expenses. Trip cancellation. Emergency evacuation. Baggage delay. These four categories make up 90 percent of what you'll need, and they're also where most people under-insure themselves. The average emergency room visit at a decent private hospital in Manila runs between $150 and $400 for a basic consultation. A broken bone X-ray plus cast with follow-up visits can easily hit $1,200. Most basic travel policies cap medical coverage at $50,000 total, which sounds like a lot until you're in a situation where repatriation to your home country is recommended. Air ambulance from the Philippines to Singapore or back to your home country typically costs between $15,000 and $50,000 depending on distance and medical intensity required.
Trip cancellation coverage varies wildly. Some policies reimburse only non-refundable expenses you can prove with receipts. Others offer a flat benefit regardless of actual costs. I've seen people claim on policies that explicitly required itemized receipts for every reservation, then get denied because their booking confirmation didn't show an explicit refund policy. Always confirm the cancellation terms before you commit.
Get the Full Details
Reading the Fine Print Like a Local
Philippine insurers and international carriers writing Philippine policies both have their own definitions of "adventure sports" and "high-risk activities." Paragliding in Baguio, scuba diving in Coron, and horseback riding in Bohol are all routinely excluded from standard policies. I've watched people get stranded in El Nido after a diving accident because their policy defined "recreational diving below 18 meters" as an exclusion trigger, and the certification they carried from PADI didn't override that clause. Water sports riders exist. They cost more, usually 30 to 50 percent higher premium, and some insurers require you to hold a recognized certification before they'll even consider the addition. If your itinerary includes any diving, jet-skiing, white-water rafting, or trekking above 2,500 meters, add the adventure rider upfront. Don't wait until you're already in the province trying to file a claim from a hotel with spotty WiFi.
The Evacuation Question
This is where the real money lives and dies. Standard emergency medical evacuation covers transport to the nearest adequate facility. That sounds reasonable until you're on a small island where "the nearest adequate facility" is a two-hour boat ride to the mainland, and the adequate facility itself is two hours by road from the dock. The insurance company approves ground transport, you wait six hours for an Ambulance from a private service that doesn't have mountain-capable vehicles, and by then your condition has deteriorated enough that they authorize air evacuation instead. That delay cost me an additional night in an ICU that wasn't covered because the initial ground transfer was approved separately from the final decision. The workaround: choose a policy with worldwide emergency evacuation rather than just regional. Some policies restrict evacuation to within the Southeast Asia zone unless you pay extra. The extra premium is usually under $50 on a typical two-week policy, and it makes a real difference when you're dealing with island geography. Also check whether the policy includes a 24/7 assistance hotline based outside the Philippines. When I had my accident, the local office in Manila wasn't operational until 9 AM. The international hotline was reachable at 3 AM my time and coordinated the entire evacuation while the local office was still closed.
Common Pitfalls That Cost Me Money
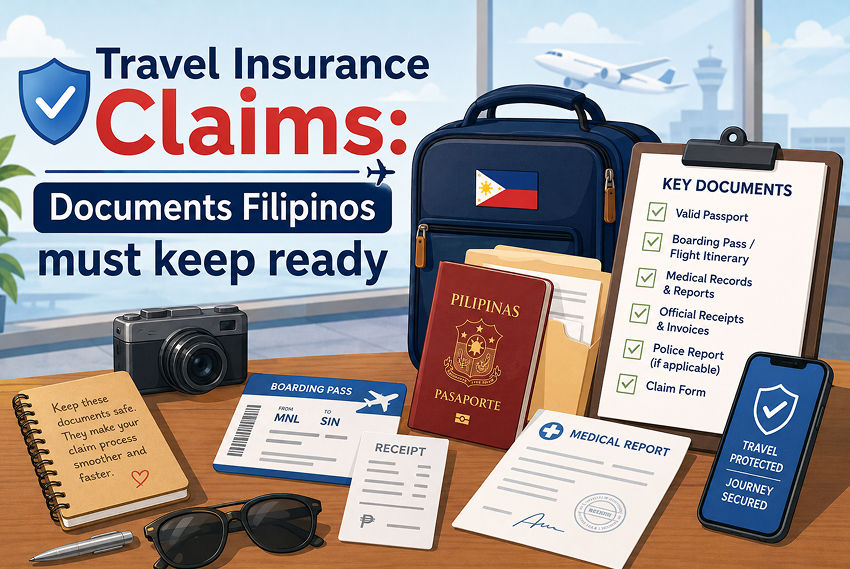
Purchase timing matters more than most people realize. If you buy insurance after you've already booked flights and hotels, your trip cancellation coverage kicks in immediately. But if you bought the insurance before booking, some policies have a waiting period of 10 to 14 days before cancellation coverage activates. I lost $800 on a cancelled tour in Siargao because I'd purchased the policy two weeks early and the cancellation fell inside that window. The insurer called it "pre-existing itinerary uncertainty." Age brackets affect pricing nonlinearly. A policy for a 65-year-old costs roughly double what a 55-year-old pays for the same coverage. A 75-year-old might pay triple. Some insurers have hard age cutoffs at 70 or 75. I recommended a family member over 70 on a policy that covered up to 65 and he had to buy a completely separate senior-specific plan that had lower medical limits but higher premiums. Check the maximum insured age before you assume standard policies apply. Claim documentation in the Philippines is stricter than elsewhere. Foreign insurers expect everything in English. Local hospital receipts often come in Filipino or Tagalog with abbreviations that claims adjusters reject. I learned to photograph every document at the point of care, request English translations on the spot, and carry a small dictionary app for common medical terms. Two of my early claims were delayed for three weeks because the hospital receipt used abbreviations the insurer couldn't verify.

Comparison of Major Providers for Philippine Coverage
I didn't test all of them, but here's what I found across the policies I've actually used or researched thoroughly. World Nomads covers adventure sports natively for most activities including diving and trekking. Their Philippines medical network is decent in Manila but thinner outside. Premium is higher than average but the breadth of coverage justifies it for active travelers. Processing time for straightforward claims averages 10 to 14 business days. Allianz Travel Care has solid direct hospital billing in Metro Manila and Cebu. Their emergency assistance hotline is responsive. The trade-off is aggressive pre-existing condition screening that can void coverage if you don't declare everything at purchase. I knew someone who didn't mention a mild heart murmur and the policy was denied when they needed cardiac workup in Davao.
AXA Travel Surakasa is a locally underwritten policy that processes claims in Philippine pesos and handles local hospital paperwork more natively. The downside is lower maximum coverage limits compared to international equivalents. Good for domestic travelers or short trips where you're mostly staying in urban areas. Travel Guard (AIG) offers flexible add-ons and solid medical limits up to $100,000. Their claims process is online-driven, which works well if you have reliable internet. Their weakness is slow response times on evacuation authorization during peak season. I've seen approval timelines stretch to 48 hours during typhoon season when multiple evacuations were happening simultaneously.
What to Do Before You Buy
List every activity you plan to do. Every single one. Then check whether each one is covered under the base policy or requires a rider. Don't assume "travel insurance" covers your actual itinerary. It usually doesn't. Check the maximum single claim limit per incident, not just the aggregate annual limit. A $100,000 annual limit sounds generous until a single hospitalization eats through it and you're left with nothing for the rest of the trip. Confirm the assistance company's phone number and operating hours. Verify they have a physical office in the Philippines if possible. Call the number before you travel to test responsiveness. This sounds extreme, but I did it before my third trip and the test call took four minutes to get through to a live person who understood exactly what I was asking about.
Keep digital and physical copies of your policy document. Store the PDF in cloud storage and email it to yourself. Print at least one copy and keep it in your carry-on, not your checked luggage. I've been at immigration counters in NAIA where officials asked to see proof of insurance and having it readily available saved me from being turned around.
When Insurance Won't Help You
Natural disasters. The Philippines sits on the Pacific typhoon belt and experiences regular seismic activity. Most policies exclude claims arising from known natural disasters at the time of purchase. If a typhoon warning is already active when you buy your policy and then get cancelled, you won't be covered for that cancellation. Some policies have a "known event" exclusion that kicks in 14 to 30 days before a named storm. I learned this the hard way when Super Typhoon Kristine was named two days before my policy's effective date and my entire trip was cancelled. The insurer cited the named storm exclusion and denied the claim entirely. Pre-existing conditions you don't declare. Be honest at purchase. The declaration process takes five minutes and protects you from denial later. Lying about a condition isn't worth losing the entire claim over a $20 premium difference. Acts of war or civil unrest. The southern Philippines, particularly parts of Mindanao, have areas with active security concerns. Standard travel insurance excludes war zones and government travel advisories. If you're traveling to areas with Level 3 or Level 4 advisories, you need specialized political risk coverage, which is a different product entirely and significantly more expensive.
Alcohol or drug-related incidents. Policies routinely deny claims when the incident involves intoxication. This isn't a philosophical stance by insurers. It's a measurable risk factor that affects their pricing models. Don't test whether your policy will cover an emergency that occurred while you were impaired. It won't.

The Bottom Line
Philippine travel insurance works when you understand its limitations and plan around them. The geographic reality of an archipelago of over 7,000 islands means evacuation logistics are fundamentally different from continental travel. Medical infrastructure concentrates in Metro Manila and a handful of larger cities. Between those points, coverage gaps exist whether you acknowledge them or not. Buy the right policy before you leave home. Declare everything. Add adventure riders for your actual itinerary, not the one you wish you had. Keep copies of your documentation. And when something goes wrong, start the claims process immediately and document everything you can. The difference between a smooth claim and a two-month headache often comes down to whether you contacted the assistance hotline within the first hour of the incident. I still think about that three-week trip to the Visayas. The ankle injury was minor. The insurance ordeal was not. Now I know better and I share that knowledge so you don't have to learn it the same way I did.