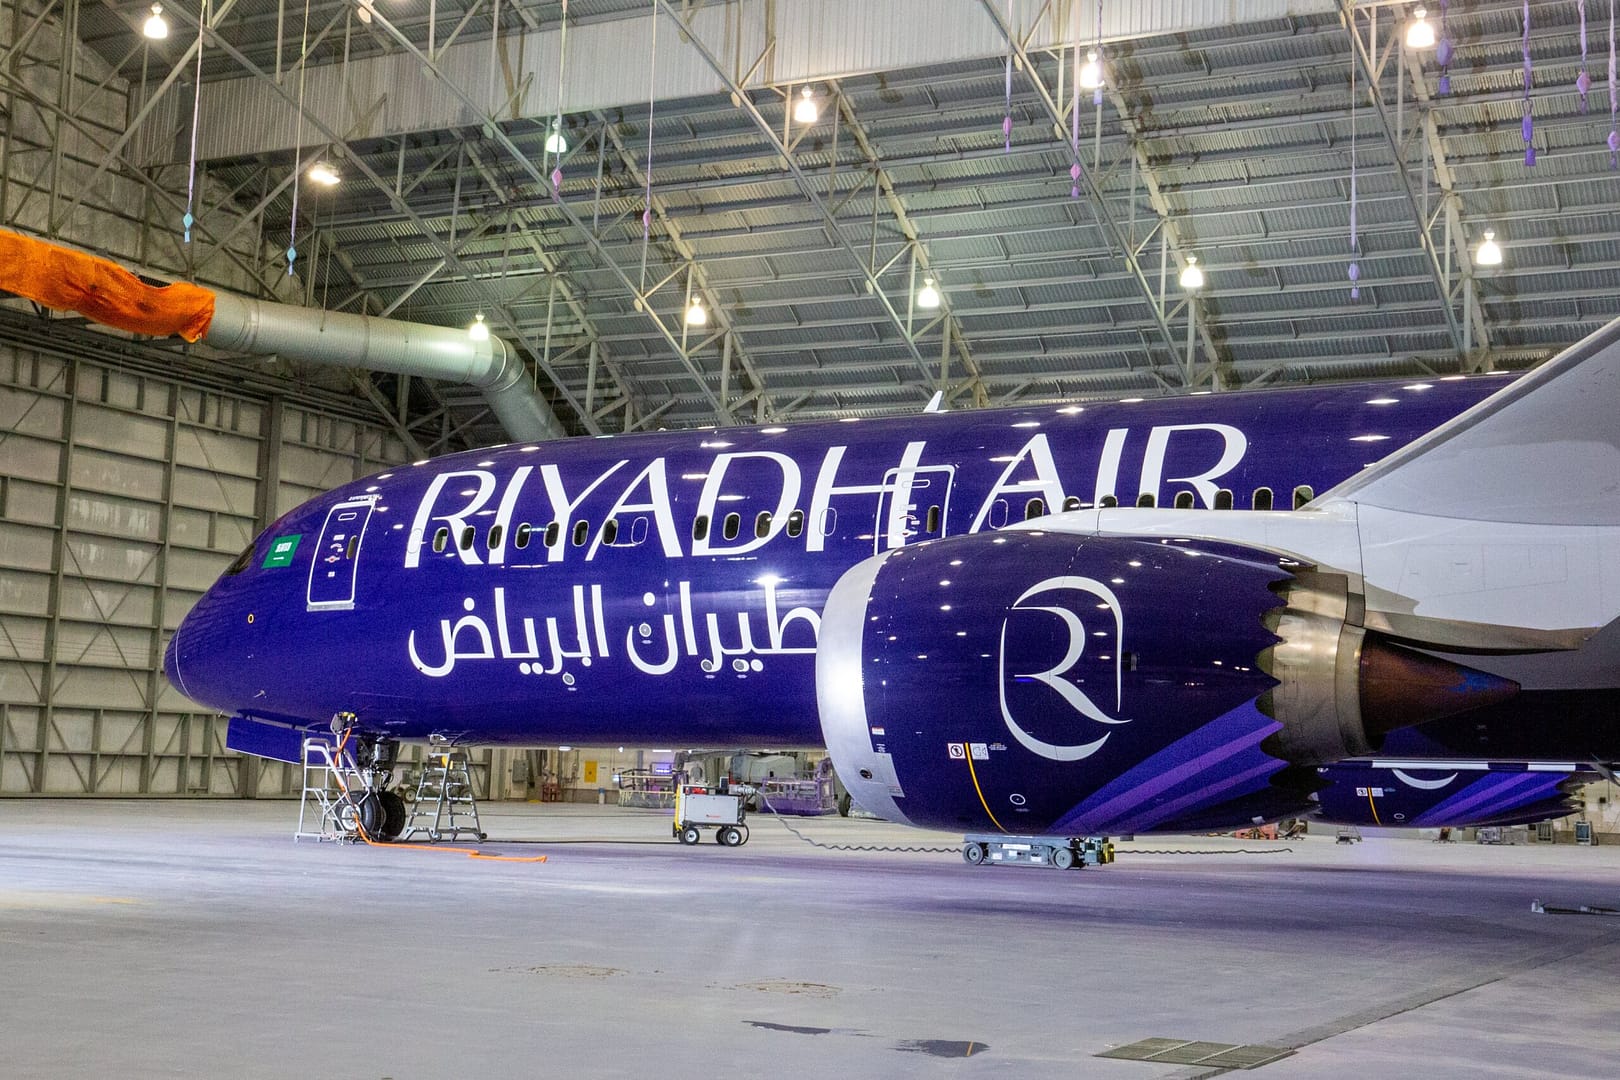
The Saudi Aviation Market Is Bigger Than People Realize
Saudi Arabia has been building out its aviation sector aggressively since the Vision 2030 rollout. You've got Saudia, the flag carrier, going through some massive transformation right now. Then there's Flynas, the low-cost carrier that's been expanding its regional routes aggressively. These are the ones everyone knows about, but the real picture is a lot more crowded and complicated than that. I've spent years tracking this sector, mostly because the contracting and procurement side of things here operates differently than anywhere else I've worked. One thing that trips people up constantly: a lot of these companies don't publicly list their full fleet or route data the way Western carriers do. Saudia, for example, reports its fleet through IATA standard filings, but the actual operational numbers they share internally with partners are often higher. During a procurement review a few years back, I hit a wall trying to verify the exact number of A330neos on order versus in service for a major MRO contract. The workaround was pulling the data directly from Saudi Civil Aviation Authority registration records, which takes about three business days to process but gives you the hard numbers. That's where most people get stuck — they rely on third-party aggregator sites that haven't been updated since last year. Saudia remains the dominant player. They're currently modernizing their fleet with Boeing 787s and Airbus A350s, though the delivery schedules have slipped a couple of times due to supply chain issues. If you're looking at partnerships or contracts, their maintenance division operates through a joint venture structure that adds layers of complexity you need to navigate carefully.
Flynas is the largest low-cost carrier based in the Kingdom. They started with ATR turboprops and have moved up to Boeing 737s. Their route network covers the GCC heavily, with growing presence in Egypt and Jordan. The economics here are tight — LCC margins in this region are thin, and fuel hedging decisions they made in 2022 cost them significantly when prices dropped. Saudia Engineering (part of the Saudia group) is the MRO backbone. They handle line maintenance, heavy checks, and component repair for the carrier itself plus some third-party work. The facility at King Khalid International Airport in Riyadh is the main hub, with additional capabilities at King Abdulaziz Airport in Jeddah. They recently added engine overhauls to their scope, which changes the competitive landscape for independent MRO providers in the region. Sabre Airlines is another name worth knowing, though smaller. They operate regional flights under contract, mostly government and Hajj-related charters. The charter side of Saudi aviation is massive and largely invisible unless you're operating in it.
PAL Technologies (formerly part of the broader Middle East aviation services space) has been involved in ground handling and some technical services. The market here is fragmented, and company structures change frequently due to consolidations and government privatization pushes. The Saudi Flight Training Academy and similar institutions are also significant players, producing pilots and technicians for the expanding fleet. If you're entering this market as a vendor or service provider, understanding the local training pipeline matters more than most outsiders realize. Several carriers have reported difficulty sourcing experienced Avionics technicians specifically, not general mechanics. Falcon Aviation Services handles a lot of the private and VIP aviation side in the Kingdom. They're based out of Riyadh and serve the royal family, government officials, and corporate clients. This segment grows steadily and isn't as transparent as commercial operations.
Get the Full Details
Riyadh Air is the new entrant everyone's talking about. Launched as part of Vision 2030 diversification, they're building a full-service carrier from scratch with a digital-first approach. Fleet commitments include A330s and 787s, though timelines keep shifting. They're recruiting heavily right now and signing deals across the board — from IT systems to ground handling agreements. Whether they succeed operationally remains to be seen, but the investment level is real and it's creating demand across the supply chain. One counter-intuitive point that catches people off guard: being "the top aviation company" in Saudi Arabia doesn't mean much if you don't have a proper local sponsorship structure. The regulatory environment requires specific licensing tiers depending on what you're doing — whether it's carrying passengers, providing MRO services, or handling cargo. Foreign companies that skip this step either partner with a local entity at unfavorable terms or get locked out entirely. I watched one European MRO firm waste eight months and roughly $200,000 in legal fees trying to operate without proper Saned and GACA registration before finally bringing in a local sponsor. The other thing nobody warns you about is the seasonal demand spike. Hajj and Umrah periods create operational pressures that most outside consultants completely overlook. Airlines scale up temporarily with wet-leased aircraft and additional crews, then contract down. If you're building a business case or projecting revenues, the annual average numbers smooth over reality too much. The June-to-September window can generate 40 to 60 percent of annual passenger volume for carriers with strong Hajj routes.
If you're sourcing from this list, my recommendation is to start with GACA's official carrier registry rather than any third-party compilation. It's updated quarterly, it's free, and it's the only source that won't mislead you on current operating certificates. The process is online but the interface isn't intuitive — you need to know which license category to search under. Take it from someone who's done this too many times: verify everything against the primary source before making any decision.
.jpeg "Saudi Arabia Opens Skies to Charter Operators with Latest Aviation Tender")