Understanding Large-Cap Valuation Without the Buzzwords
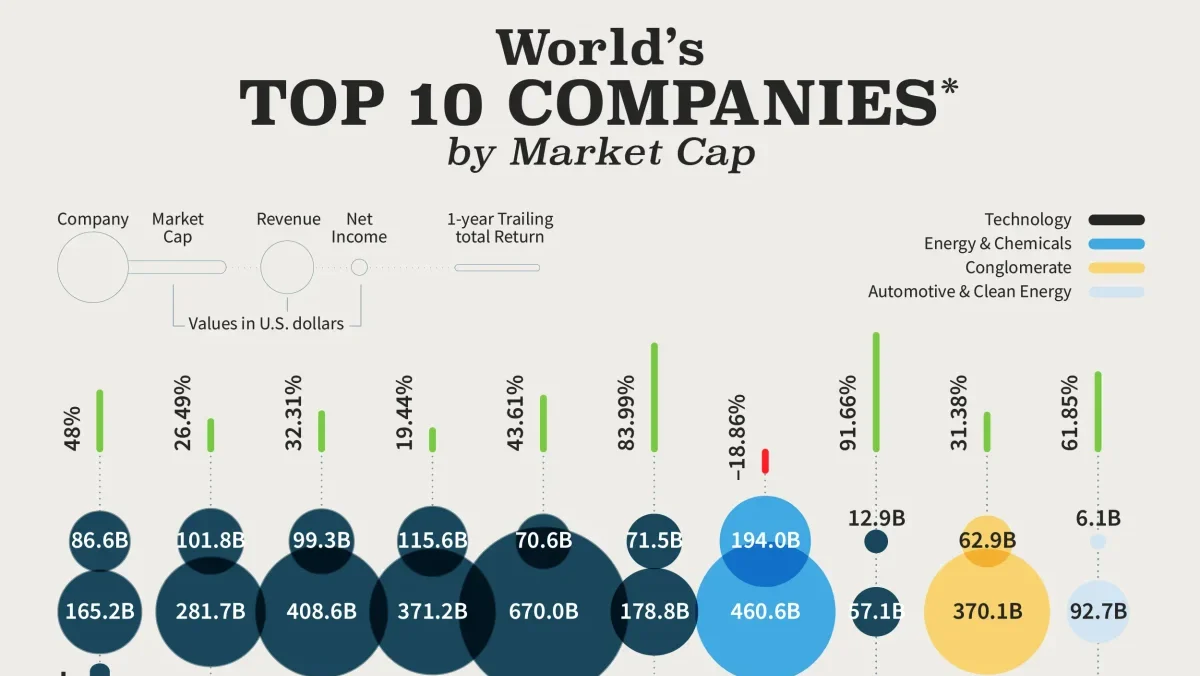
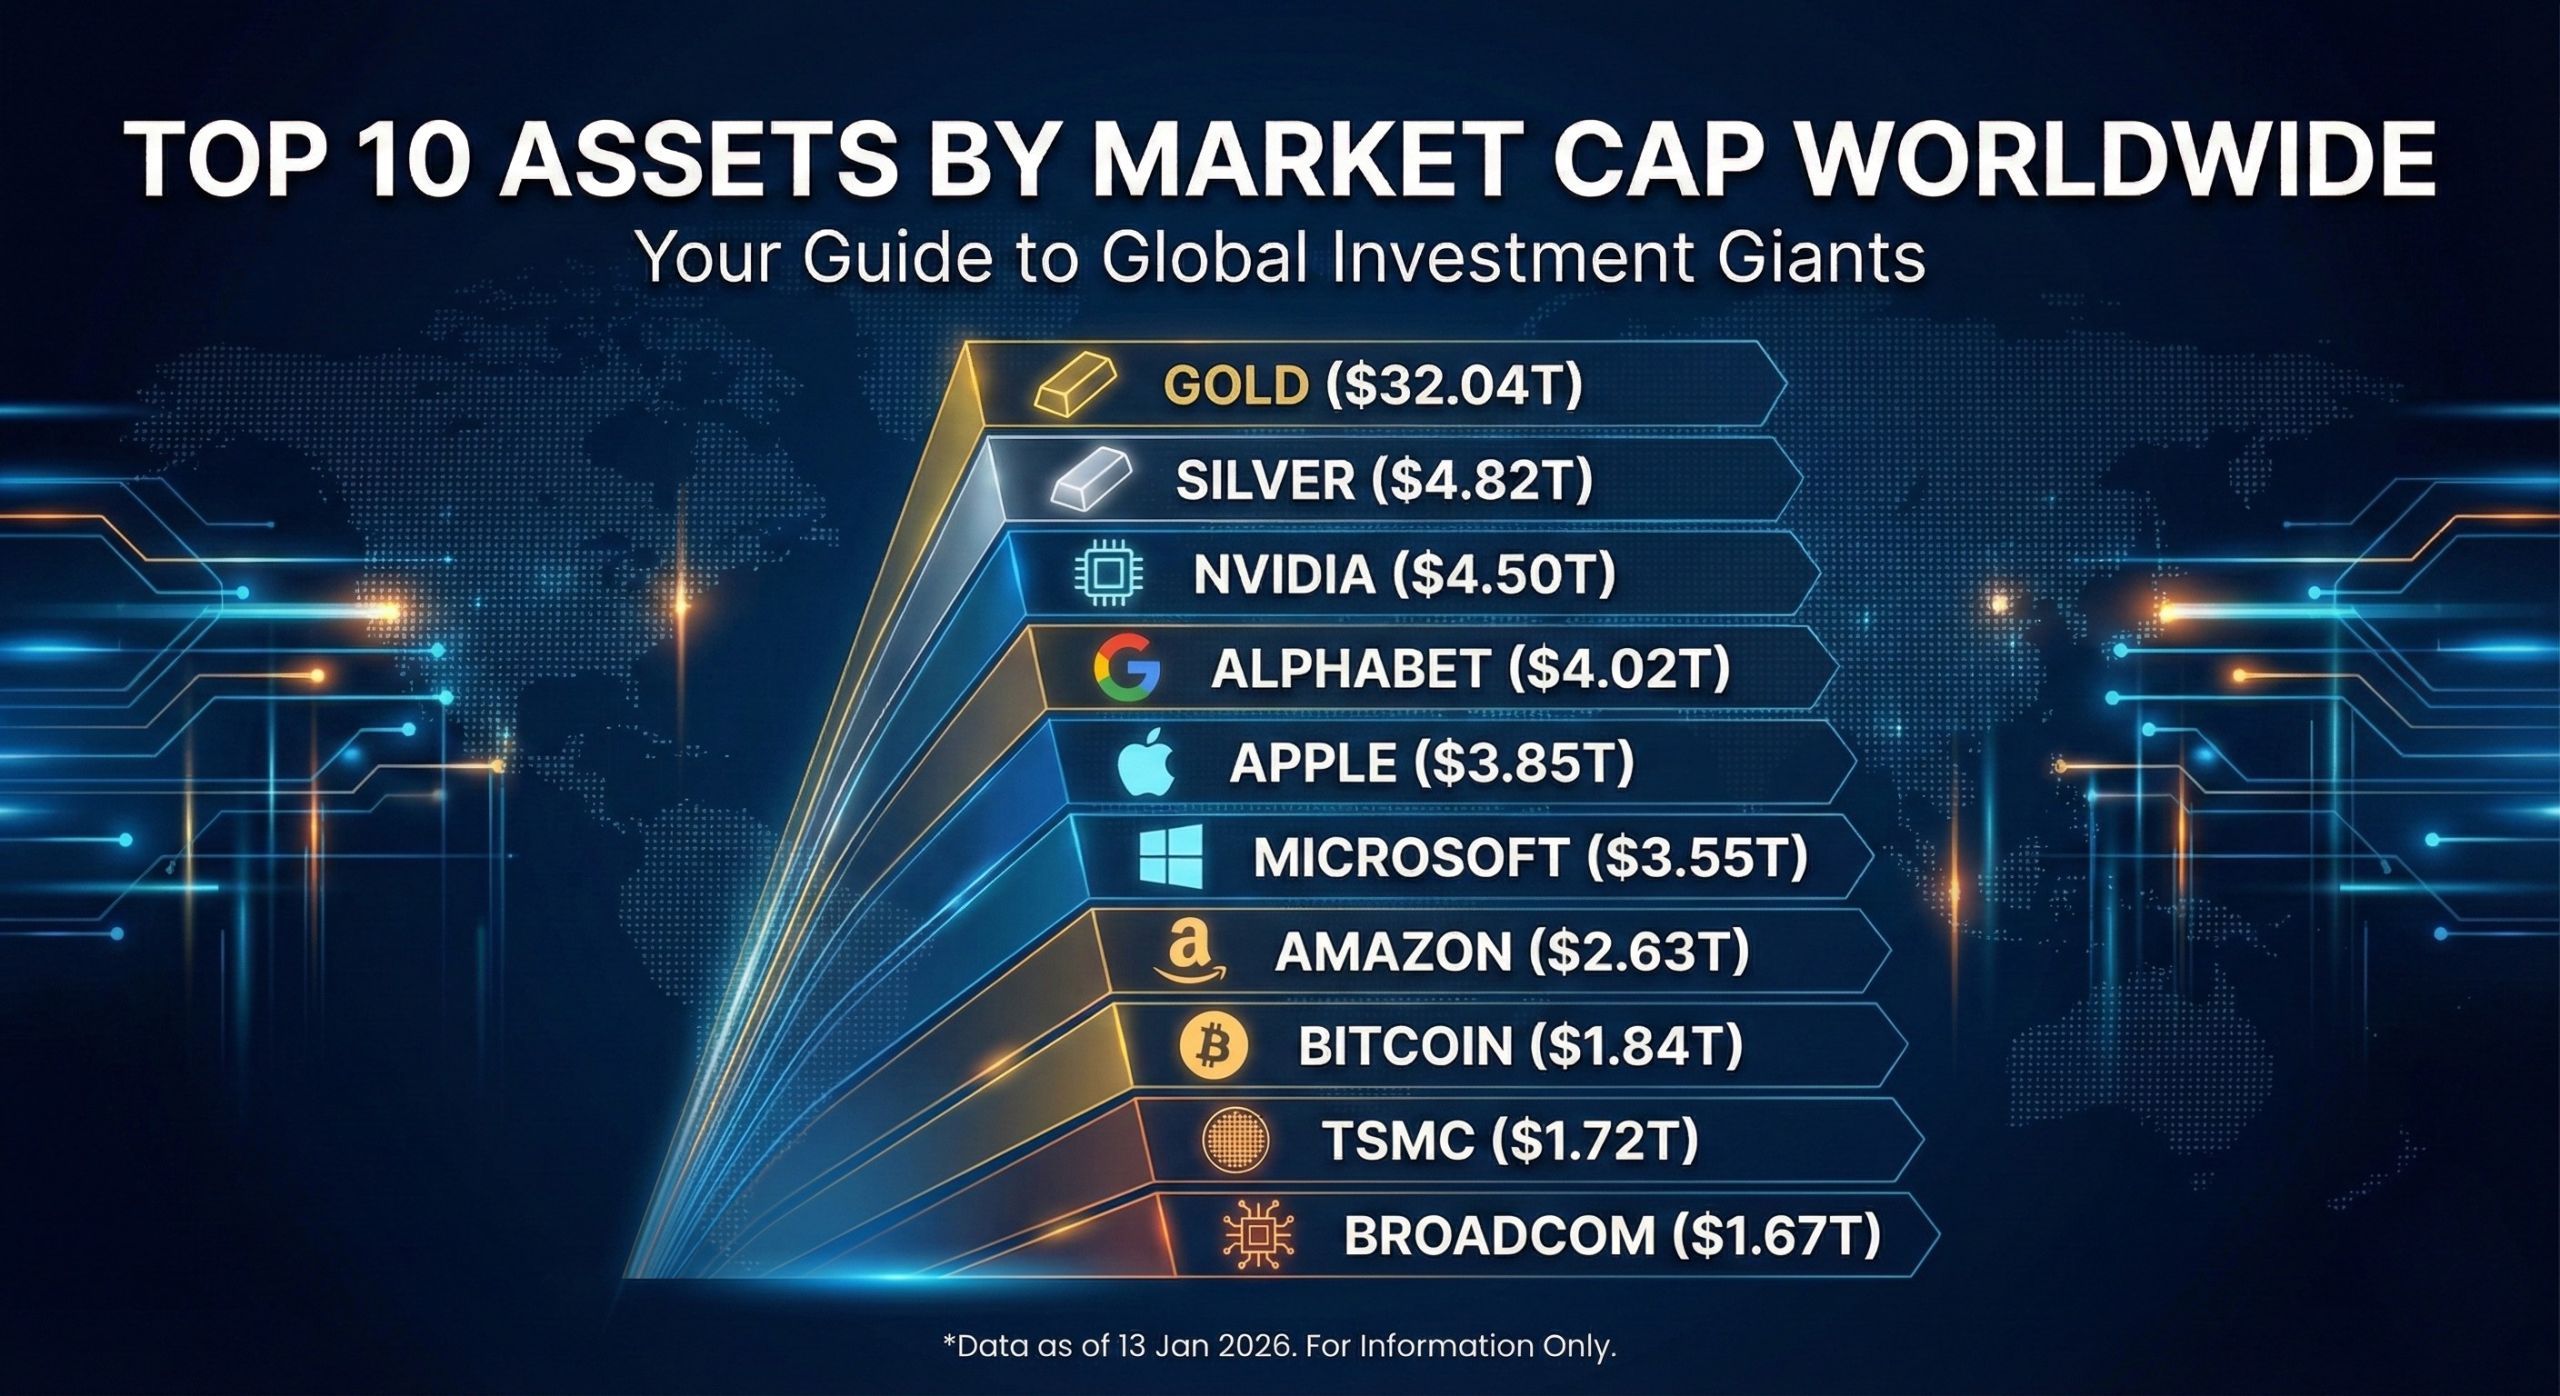
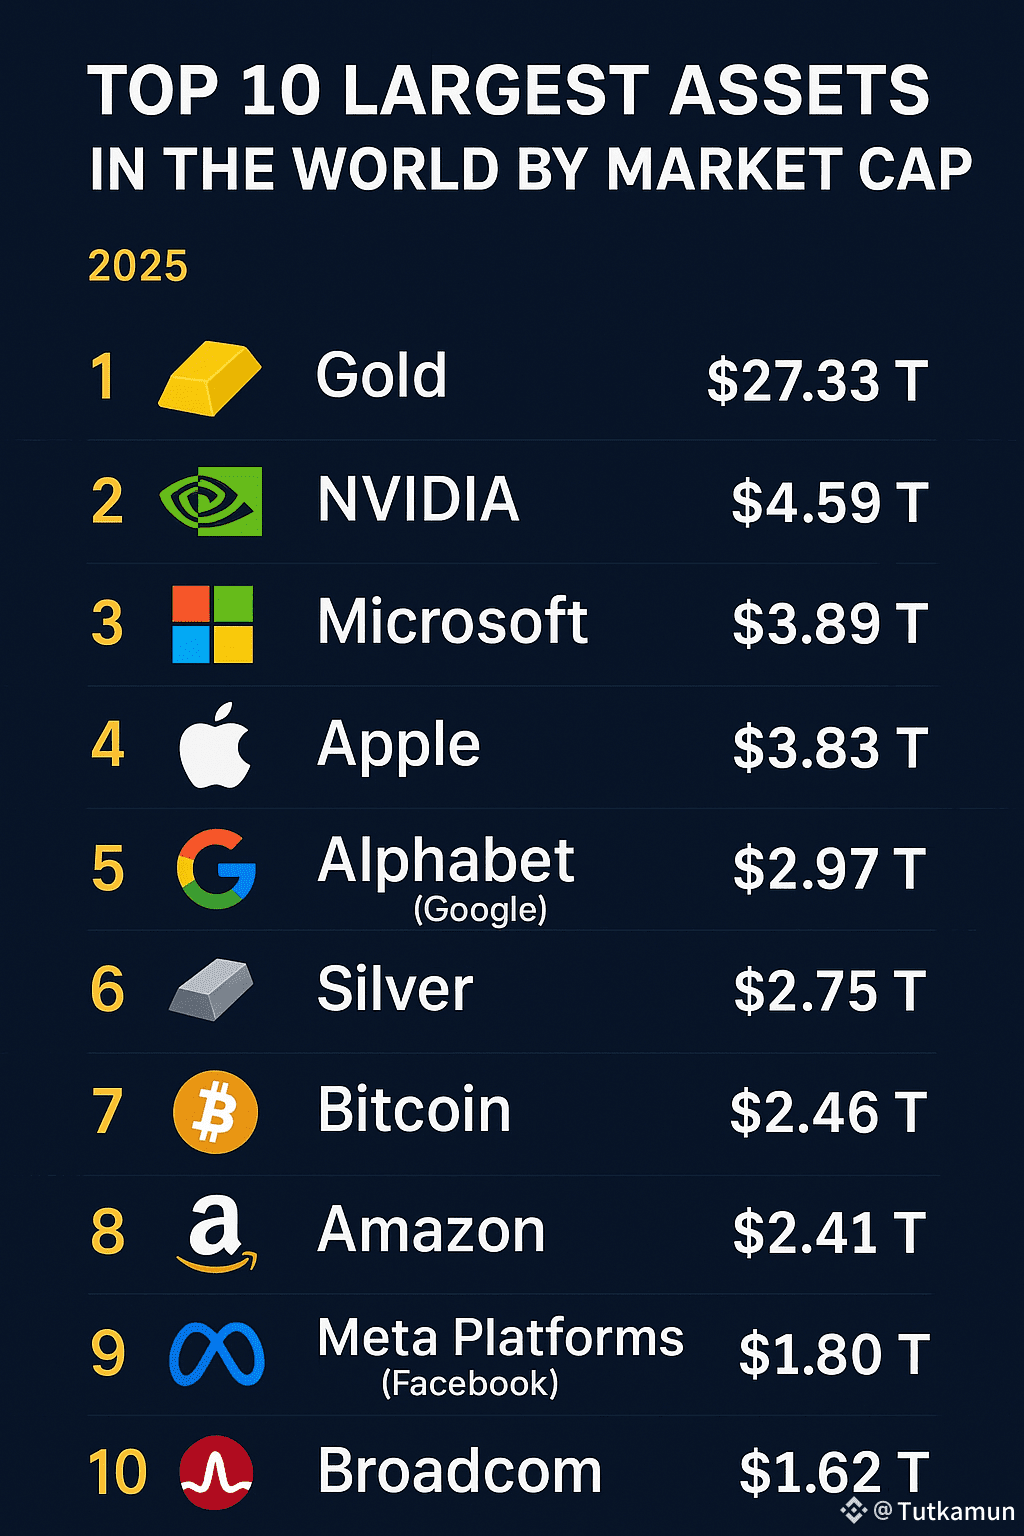
I've been working with market-cap data for over a decade, and the most common mistake I see people make is treating market cap as if it's an absolute measure of value. It's not. It's a snapshot of total equity value at a specific point in time, calculated by multiplying share price by total shares outstanding. That's it. Nothing more profound than that. The ranking of the largest public companies shifts constantly. Apple, Microsoft, NVIDIA, Saudi Aramco, Alphabet—they cycle through the top spots depending on which sectors are in favor. Right now, the composition looks fairly normal. Big tech dominates, energy holds steady, and a handful of financial institutions round out the list. But this isn't permanent. It changes quarterly.
Top Market Cap Assets In The World A Look At The Largest Public Companies
Here's how I actually verify these rankings when I need reliable data. Most people just google it and trust whatever comes up first. That works sometimes. More often, you'll land on a site that's using stale data or a different methodology than what you need. I pull directly from financial data platforms like Bloomberg Terminal or the SEC's EDGAR database. For quick checks, Yahoo Finance and MarketWatch are acceptable if you note the timestamp. The specific numbers change by the minute during trading hours anyway. Let me walk you through the calculation process since everyone claims to understand it but few actually work through an example correctly. Say you have a company with 2 billion shares outstanding and a current price of $150 per share. The market cap is $300 billion. Now factor in that some of those shares might be treasury stock—shares the company bought back and retired. Those don't count toward market cap. You need to use the float-adjusted shares or the total outstanding shares figure from the latest 10-K filing. I learned this the hard way in 2021 when a client asked me to compare two companies and I used the wrong shares-outstanding figure. The resulting spread was off by approximately $40 billion. Embarrassing, but it taught me to always triple-check that number. There are a few nuances that beginner analysts consistently miss. First, market cap doesn't account for debt. A company with a $500 billion market cap and $200 billion in debt is structurally different from a company with the same market cap and zero debt. If you're doing any serious comparison work, you need enterprise value, which is market cap plus total debt minus cash and equivalents. This matters enormously when comparing companies across sectors. A utility company and a tech company might have similar market caps, but their debt structures are completely different, and enterprise value reveals that gap immediately.
Second, foreign-listed companies create conversion headaches. A Japanese company listed on the Tokyo Stock Exchange trades in yen. Its market cap in dollars depends entirely on the exchange rate at the moment of calculation. I once spent three hours tracking down why a ranking list didn't match my own analysis. The issue was a 4 percent yen fluctuation over two days. The company jumped eight positions on the global list purely from currency movement, not from any fundamental change. Always note the date and the exchange rate when you're citing cross-border market-cap figures. Third, and this is the one most people skip: market cap weights distort index performance. The S&P 500 is a float-adjusted market-cap-weighted index, which means the ten largest holdings can represent nearly 35 percent of the entire index. When NVIDIA moved into the top three by market cap, it suddenly became a much larger driver of S&P 500 returns than it was six months earlier. This isn't theoretical. I watched a pension fund manager get burned on this in early 2024. He assumed diversification across 500 stocks meant moderate exposure to any single name. The math didn't work out that way. One practical tip for anyone actually tracking this data: set up a simple spreadsheet that pulls the top 20 companies by market cap weekly. Use a script or a subscription to a data feed so you aren't manually updating every Monday morning. I built mine using Python and the yfinance library, and it takes about twelve minutes to run each week. The output gives me a clean ranking with the date stamp, the share count, the price, and the calculated market cap. Having that historical record lets you spot trends. Is a company's market cap growing because earnings improved or because the stock price ran ahead of fundamentals? The spreadsheet answers that question without requiring deep analysis every single time.
Get the Full Details

There are real limitations to relying solely on market cap as your primary metric. It tells you nothing about profitability. A company can have a large market cap and be losing money every quarter. It also amplifies momentum, which means bubbles get categorized as legitimate large-cap holdings simply because price keeps climbing. During the dot-com era, companies with absurd valuations sat at the top of market-cap lists for years before the correction hit. Market cap is descriptive, not predictive. It measures what the market has assigned in total value, not whether that value is justified. If you want a more complete picture, combine market-cap ranking with revenue, net income, and free cash flow. The largest companies by market cap are usually the largest by revenue too, but not always. Some high-valuation, low-revenue companies in biotech or speculative tech sectors can sit in the top twenty by market cap while generating minimal earnings. Context changes everything about how you interpret those numbers. The most useful application of market-cap data is in portfolio construction. If you're building a large-cap index fund, you're already getting the top market-cap companies by design. If you're constructing an active portfolio, knowing which companies dominate by market cap helps you understand what the broader market is implicitly betting on. It's a sentiment indicator as much as a sizing metric. When energy stocks suddenly fill five of the top ten spots, something is happening with oil prices and investor positioning that deserves investigation.
I don't recommend using market cap rankings as a standalone investment signal. They're a starting point for research, nothing more. The data is freely available from multiple sources. What separates people who use it effectively from those who don't is whether they add the layer of debt analysis, currency awareness, and historical trend tracking on top of the raw ranking numbers.