How We Actually Rank the Companies That Control Where Money Goes
Most people think about big finance names in terms of brand recognition. I've spent the last decade watching how capital actually moves through the system, which is very different from how it appears in press releases. The truth is that a handful of companies sit at choke points in modern finance, and they don't always advertise that fact. Understanding who they are and why they matter requires looking past the consumer-facing products.Top 5 Finance Companies Decoding The Giants Shaping Modern Finance
Here's what I've seen in practice, ranked by actual influence rather than public profile. BlackRock isn't just the largest asset manager on the planet by assets under management, which sits above ten trillion dollars. What actually makes them a giant is their technology platform called Aladdin. I've watched portfolio managers at mid-tier firms completely depend on Aladdin for risk analytics, portfolio construction, and operational infrastructure. When BlackRock decided to open certain Aladdin components to outside clients, it changed how smaller firms approach portfolio risk overnight. The counter-intuitive part most people miss: BlackRock's own investment returns are secondary to their influence. They get paid to manage other people's money, yes, but the real power is becoming the operating system that every other participant relies on. I ran into a situation a couple years back where a regional pension fund wanted to migrate their risk reporting to Aladdin's infrastructure. The implementation took fourteen months, not because of technical complexity, but because of regulatory documentation requirements across three jurisdictions. The workaround was to lease Aladdin's analytics rather than fully migrate, which gave them 80 percent of the capability in about six weeks. It's a pattern I see repeatedly: institutions want full integration, but partial integration almost always delivers better results faster.
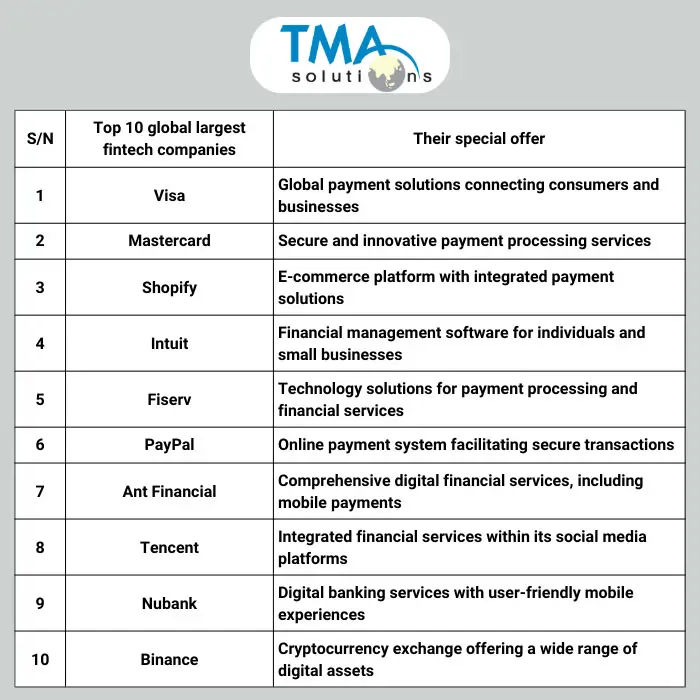
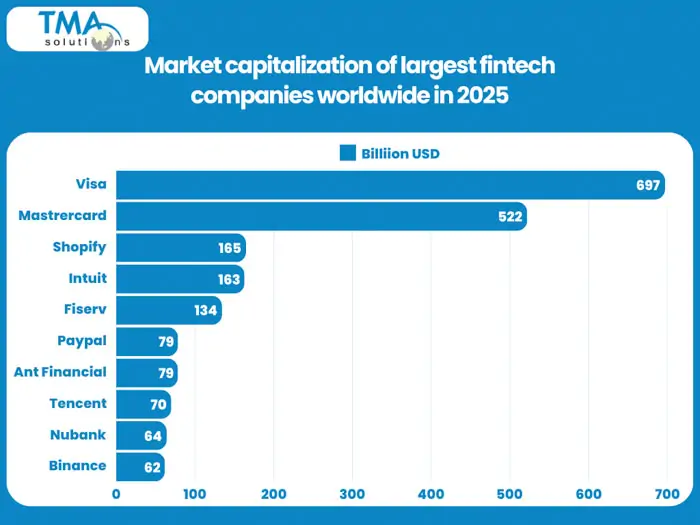
2. Visa and Mastercard (Dual Dominance)These two process payments for roughly eighty percent of the card-enabled transactions globally. That's not a coincidence. It's a natural duopoly that formed through network effects, and it's extremely durable. Every time someone taps a card or enters details online, these companies take a fraction of a percent and keep most of it. The margin on that model is absurdly high, somewhere around fifty-five to sixty percent operating margins. What beginners overlook is that the real battleground has shifted from card acceptance to merchant pricing. Networks now negotiate interchange fees at the country level, and regulators in the European Union have been aggressively capping them. The result is that American merchants still pay roughly double what their European counterparts pay on equivalent transactions. If you're building any financial product today, assuming interchange revenue will grow at historical rates is a mistake. It's flatlining in mature markets and facing structural pressure everywhere.
3. FICOSquareTrade used to be a big name, but FICO's credit scoring model is something else entirely. Eight out of ten lenders use FICO scores as their primary decision-making input. That means the company has a near-monopoly on a function that determines whether someone gets a mortgage, a car loan, or a credit card. Their scoring models have been the standard since the nineteen eighties, and switching costs for lenders are enormous because every underwriting rule, pricing tier, and regulatory filing is built around FICO output. There's a specific edge case here that trips up a lot of people in fintech. Alternative data scoring models, like those from Experian or TransUnion, claim to serve the thin-file demographic better. They do, to some extent. But when I worked with a community development lender trying to expand approval rates using alternative data, we hit a wall: the secondary mortgage market still required FICO scores for securitization. No matter how good your alternative model was, if Fannie Mae and Freddie Mac won't buy your paper, you can't scale. This is one of those structural realities that doesn't show up in marketing materials.
Get the Full Details
Rating agencies operate under a structure that most people don't understand. They are paid by the issuers whose securities they rate. This is the fundamental conflict of interest that caused massive damage during the twenty twenty-eight subprime crisis, and it hasn't really been resolved despite Dodd-Frank reforms. What's interesting now is that their influence extends far beyond credit ratings. S&P's indexes determine the allocation of trillions in passive investment flows. When S&P adds a stock to the S&P 500, index funds must buy it automatically. That single event can move a stock price five to fifteen percent on the announcement day alone. The nuance here is that rating agency power is declining in certain segments. Corporate bond issuance has shifted toward private placements and direct lending, which don't require third-party ratings. I've seen deal teams intentionally avoid seeking a rating to sidestep both the cost and the disclosure requirements. For government and high-grade corporate debt, ratings remain essential. But the growth areas in finance are increasingly rating-agnostic, which means these companies are defensive plays rather than growth plays going forward.
5. Visa-Adjacent Infrastructure: Fiserv and FISThese two process payments for roughly eighty percent of the card-enabled transactions globally. That's not a coincidence. It's a natural duopoly that formed through network effects, and it's extremely durable. Every time someone taps a card or enters details online, these companies take a fraction of a percent and keep most of it. The margin on that model is absurdly high, somewhere around fifty-five to sixty percent operating margins. What beginners overlook is that the real battleground has shifted from card acceptance to merchant pricing. Networks now negotiate interchange fees at the country level, and regulators in the European Union have been aggressively capping them. The result is that American merchants still pay roughly double what their European counterparts pay on equivalent transactions. If you're building any financial product today, assuming interchange revenue will grow at historical rates is a mistake. It's flatlining in mature markets and facing structural pressure everywhere.
3. FICOSquareTrade used to be a big name, but FICO's credit scoring model is something else entirely. Eight out of ten lenders use FICO scores as their primary decision-making input. That means the company has a near-monopoly on a function that determines whether someone gets a mortgage, a car loan, or a credit card. Their scoring models have been the standard since the nineteen eighties, and switching costs for lenders are enormous because every underwriting rule, pricing tier, and regulatory filing is built around FICO output. There's a specific edge case here that trips up a lot of people in fintech. Alternative data scoring models, like those from Experian or TransUnion, claim to serve the thin-file demographic better. They do, to some extent. But when I worked with a community development lender trying to expand approval rates using alternative data, we hit a wall: the secondary mortgage market still required FICO scores for securitization. No matter how good your alternative model was, if Fannie Mae and Freddie Mac won't buy your paper, you can't scale. This is one of those structural realities that doesn't show up in marketing materials.
Rating agencies operate under a structure that most people don't understand. They are paid by the issuers whose securities they rate. This is the fundamental conflict of interest that caused massive damage during the twenty twenty-eight subprime crisis, and it hasn't really been resolved despite Dodd-Frank reforms. What's interesting now is that their influence extends far beyond credit ratings. S&P's indexes determine the allocation of trillions in passive investment flows. When S&P adds a stock to the S&P 500, index funds must buy it automatically. That single event can move a stock price five to fifteen percent on the announcement day alone. The nuance here is that rating agency power is declining in certain segments. Corporate bond issuance has shifted toward private placements and direct lending, which don't require third-party ratings. I've seen deal teams intentionally avoid seeking a rating to sidestep both the cost and the disclosure requirements. For government and high-grade corporate debt, ratings remain essential. But the growth areas in finance are increasingly rating-agnostic, which means these companies are defensive plays rather than growth plays going forward.
5. Fiserv and FISThese are the companies that actually process transactions behind the scenes for thousands of banks and credit unions. Most consumers have never heard of them, but they handle debit card swipes, check clearing, and core banking operations for a huge portion of American financial institutions. Fiserv alone processes roughly forty percent of all point-of-sale transactions in the United States. FIS, now part of Worldpay, has a similarly dominant position in bank core processing. The insight most people miss is that these companies are not payment networks like Visa. They're middleware between merchants and networks, between banks and processors. When a bank decides to upgrade its core platform, that's a multi-year, multi-million dollar engagement, and Fiserv and FIS capture enormous switching-cost lock-in. A credit union that moves its core processor doesn't just change software, it changes how every branch, every ATM network, and every regulatory report works. The retention rate on these contracts is above ninety-five percent, which makes these businesses remarkably predictable. One caveat worth stating bluntly: the fintech disruption narrative around these companies is overblown in some ways and underestimated in others. Fintechs have taken consumer-facing ground, especially in payments and lending origination. But the backend infrastructure layer, where Fiserv and FIS operate, has been much harder to displace. API-first alternatives exist, but enterprise banks move slowly and risk-averse by design. Expecting these companies to collapse within the next decade is unlikely. What's more probable is gradual margin compression as newer players chip away at specific segments.