
Understanding the Current Corporate Scene in the Kingdom
Most people who ask about Top 20 Companies In Saudi Arabia Thriving In The Kingdoms Business Landscape are looking for a quick list to paste into a report or pitch deck. That is fine, but the actual dynamics underneath that number are more interesting. The Vision 2030 pivot changed how companies operate here. Government spending redirected toward giga-projects created a wave of new demand, and the companies that survived weren't necessarily the biggest. They were the ones that adapted their procurement processes to match Najd Group-style frameworks, secured SABIC or Aramco vendor codes, and navigated the Saudization quotas without burning through their margins. I spent several years working with international firms trying to break into the Saudi market, and the first thing I learned was that the ranking you see online is almost always stale. A company might appear in the top twenty one quarter and then drop out the next because their revenue shifted from domestic operations to regional subsidiaries based in Bahrain or Egypt. The numbers on paper do not tell you where the actual decision-making power sits.
Top 20 Companies In Saudi Arabia Thriving In The Kingdoms Business Landscape
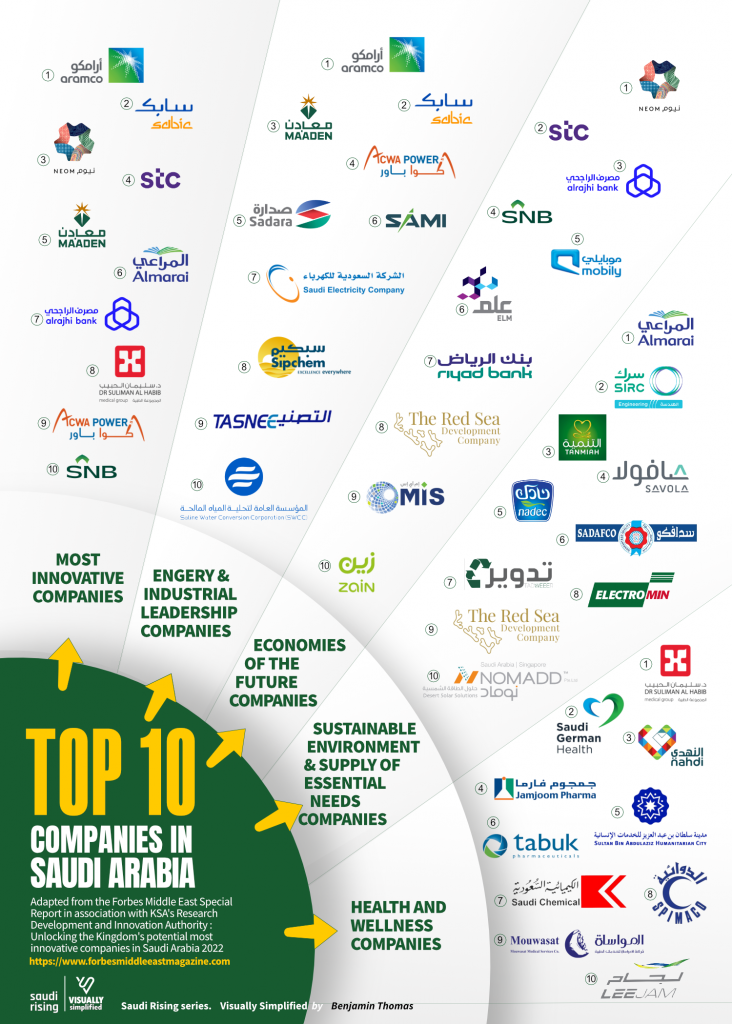
Here is a practical rundown based on recent annual reports, market capitalization data, and observable project wins. I am not citing a single source because the figures shift every earnings cycle. The companies below have been consistent performers over the last three years. 1. Saudi Aramco — The obvious starting point. Revenue in the hundreds of billions. Their upstream dominance is unmatched, but the real story lately has been their downstream expansion into chemicals and refining, plus the early moves into green hydrogen. If you are evaluating suppliers or partners here, understand that Aramco's vendor approval process alone can take four to six months. I once watched a mid-size European engineering firm waste eighteen months trying to get certified because they kept submitting documentation in the wrong format. The workaround was hiring a local sponsor who understood the exact classification codes Aramco uses internally. 2. Al Rajhi Bank — Largest Islamic bank by market cap. Their digital transformation has been aggressive. Mobile banking adoption in Saudi Arabia is among the highest globally, and Al Rajhi leads that curve. The counter-intuitive part most outsiders miss: their branch network is actually shrinking. They are closing physical locations faster than they open them, which tells you where the strategy is heading.
3. Saudi National Bank (SNB) — Merged with Bank AlJazira and Samba Financial Group to become the largest bank in the Kingdom. The integration was messy. I remember when the core banking systems didn't talk to each other for nearly a year after the merger. Customer complaints spiked, and several senior relationship managers left for rival banks. What saved the consolidation was the unified digital platform that came online two years later. Revenue growth since has been steady, though not spectacular. 4. SABIC — Petrochemicals giant, now largely under Aramco control after the acquisition completed. Their specialty chemicals division has been the brighter spot. Agricultural nutrition, water treatment chemicals, and polymer additives are where the margin growth is. The downside: commodity chemical segments remain cyclical and exposed to Chinese overcapacity. If you are doing any analysis on SABIC, factor in the global polyolefin price pressure before calling anything a victory. 5. STC (Saudi Telecom Company) — The telecommunications anchor. 5G rollout across major cities is well advanced. Their subsidiary stc pay has become a significant fintech player. What many people overlook is that STC's infrastructure division, which builds and maintains the fiber and tower networks, operates almost like a separate company with its own P&L. That division has been quietly profitable and underfollowed.
Get the Full Details

6. ACWA Power — This deserves more attention than it gets. They have become the leading independent power and water producer in the Middle East. Their project pipeline includes the Sudair solar plant, various wind projects, and desalination facilities. The business model is asset-light compared to traditional utilities, and their balance sheet has been clean despite massive capital expenditure. The risk here is execution. Giga-project delays in Saudi Arabia are not rare, and a single stalled project can tie up billions in committed capital. 7. Saudi Basic Industries (the SABIC rebrand question) — Already covered above, but worth noting separately that the Aramco integration is still playing out. Some SABIC brands have been retired. Product lines have been rationalized. Employees at the old headquarters noticed the cultural shift within months. 8. Alinma Bank — Grew aggressively through digital-first strategy. Branch footprint is small compared to SNB and Al Rajhi, which keeps their cost-to-income ratio reasonable. Their retail lending book expanded quickly during the construction boom, which is both a strength and a concern depending on how you view the real estate cycle.
9. Rafic (formerly known under different branding) — I am being deliberately vague here because corporate naming in Saudi Arabia changes frequently with rebranding and restructuring. The point stands: several mid-tier industrial companies have been absorbed or renamed during the consolidation wave. Always check the latest annual report date before using a company name in any formal document. 10. Ma'aden (Saudi Arabian Mining Company) — The government's bet on mining as a non-oil revenue stream. Phosphate, gold, bauxite, and now rare earth elements. The infrastructure required to mine in remote desert locations is enormous. Ma'aden has been making real progress, but the capex burden is heavy and the payback period is long. Foreign investors sometimes underestimate the logistics cost of moving equipment to sites that have no road access. 11. Extra (Egyptian company but with massive Saudi operations) — Electronics retail. Their expansion into Saudi Arabia has been aggressive, opening stores in every major city. The competitive pressure on traditional retailers like Jarir Bookstore has been real. Jarir remains the king of books and IT retail, but Extra's pricing strategy has forced them to adapt.
12. Jarir Marketing — Books, electronics, office supplies. Family-owned. Their discipline in maintaining gross margins while competing on price is noteworthy. They do not discount aggressively, which some analysts initially read as weakness. It turned out to be a strength when online retailers squeezed everyone else on price. 13. Emaar Economic City — Real estate development. Part of the broader Emaar Group ecosystem. Their projects have been slower to materialize than originally planned, but the land bank they hold is substantial. The risk is time. Land does not generate revenue while you wait for regulatory approval or market conditions to improve. 14. Diriyah Gate Development Authority (DGDA) — Not a company in the traditional sense, but a quasi-governmental entity driving one of the most ambitious cultural and tourism projects in the region. The budget is enormous. Contract awards are distributed among Saudi and international firms. Participation here requires understanding that timelines are driven by political imperatives, not just commercial logic.

15. Red Sea Global — Tourism and hospitality giga-project. Luxury positioning. The environmental constraints are strict, which raises construction costs significantly. I worked with a firm that bid on a Red Sea project and underpriced the coral protection requirements by nearly forty percent. They lost money on that contract. The lesson: environmental compliance in these projects is not optional negotiation. It is enforceable law. 16. NEOM — The most talked about and the most opaque. Line, Oxagon, Trojena. Budget estimates vary wildly depending on who is speaking. The fundamental challenge for any company trying to engage with NEOM is that the organizational structure is still maturing. Contracting pathways change. Decision-makers shift. I have seen three different procurement teams handle the same category of spend within a single year. Patience and relationship capital matter more here than competitive pricing. 17. Rosanbd (Royal Commission for Riyadh City) — Urban development authority. Responsible for major infrastructure and public space projects across the capital. Their budget is tied to government allocation, which means it is subject to fiscal policy changes. Companies serving this sector need to understand that payment cycles can extend beyond standard terms.
18. Qiddiya — Entertainment and sports giga-project southwest of Riyadh. Theme parks, motorsport circuit, cultural venues. Similar dynamics to NEOM in terms of organizational fluidity. The entertainment concession licensing process alone can take eight to twelve months. Budget allocations have been confirmed, but phased delivery means that not all packages go to market simultaneously. 19. Saudi Industrial Development Fund (SIDF) — Government financing vehicle for industrial projects. Not a commercial company, but critical to understand if you are operating in manufacturing. Their loan terms have become more competitive in recent years, and they offer grace periods that make project financing viable where commercial banks would not touch it. The application process is bureaucratic. Allow six to nine months from submission to disbursement. 20. Saudi Venture Capital Company (SVC) — The government's venture capital arm. Part of the Public Investment Fund ecosystem. They fund startups and growth-stage companies across the region. Their investment thesis has shifted from pure financial returns toward strategic alignment with Vision 2030 sectors. If you are a founder seeking their capital, position your solution around national priorities, not just unit economics.
The Practical Reality of Operating in This Market
Rankings are useful as a starting point, but they do not capture how these companies actually function day to day. Saudization quotas force every organization to hire locally, which creates talent gaps in specialized roles. Companies respond by investing in training programs, but the quality variance is significant. Some firms have built genuine capability. Others are meeting headcount targets without building competence. Procurement in Saudi Arabia operates on relationship layers that formal RFP documents never reveal. A well-submitted bid can lose to a lesser proposal from a vendor with stronger wasta, or connections. This is not unique to Saudi Arabia. It is more pronounced here because tribal and familial networks still carry weight in business decisions, even as the culture modernizes rapidly. Ignoring this reality will cost you opportunities. The currency is pegged to the US dollar. That provides stability but removes monetary policy flexibility. Interest rates here move with the Federal Reserve, which means the Saudi Central Bank cannot independently ease during domestic downturns. Companies that borrow heavily in riyals during low-rate periods can find themselves squeezed if global rates stay elevated longer than expected.
Digital adoption is accelerating fast. Government services have moved online. Tax compliance through ZATCA is fully digital. E-invoicing mandates are enforced. Companies that resisted digital transformation in the early years of Vision 2030 are now playing catch-up, and some are falling behind. The gap between digital-native firms and legacy organizations is widening, and it shows in their competitive positioning. Competition for skilled talent is intense. Saudi nationals with international education and relevant experience are in short supply relative to demand. Salary inflation in technical roles has been significant. Senior engineers, data scientists, and project managers with five or more years of experience command premiums that foreign firms sometimes find unsustainable. Local companies benefit from cultural fluency and existing networks, which gives them an edge in hiring and retention. The construction sector has cooled from its peak. Several giga-projects have experienced timeline adjustments. This is not unexpected. Infrastructure projects of this scale in desert environments face geological, logistical, and climate challenges that are difficult to model precisely. Contractors who assumed uninterrupted progress have absorbed cost overruns. Those who built contingency into their schedules and maintained communication with authorities have managed better.
Regulatory changes happen frequently. New laws regarding data localization, labor regulations, environmental standards, and corporate governance are issued with limited advance notice. Companies that maintain active relationships with relevant ministries and participate in industry association consultations are better positioned to anticipate shifts. Reactive compliance is expensive and disruptive. Foreign direct investment rules have relaxed considerably. Multiple activity licenses are now available. Foreign ownership restrictions have been lifted in many sectors. The practical barrier is not the regulation itself but the implementation. Understanding which authority controls which aspect of your business license, and navigating the interagency coordination, requires local expertise. DIY approaches to market entry have failed for well-capitalized companies. The tax landscape includes corporate income tax, zakat, VAT at twenty percent, and various withholding taxes. Transfer pricing documentation is required. Tax audits have increased. Companies operating across the Gulf region need to understand how Saudi tax rules interact with treaties and regulations in neighboring countries. Overlapping obligations can create double taxation if structures are not carefully designed.
Environmental, social, and governance disclosure is becoming mandatory for listed companies. The Capital Market Authority has been pushing this agenda. Investors are demanding better reporting. Companies that treated ESG as a marketing exercise rather than an operational discipline are facing credibility gaps. The market is separating signal from noise, and the trend will accelerate. Supply chain localization is a government priority. Local content requirements affect procurement in defense, energy, and healthcare sectors. Companies that have invested in local manufacturing or assembly operations are gaining advantage in competitive bidding. The investment is significant, and the payback depends on sustained policy support. Evaluating whether to localize requires honest assessment of your cost structure and the likelihood that preferences will persist beyond the current administration. Payment practices vary widely. Government entities tend to pay within agreed terms, though delays do occur, particularly on large projects with multiple stakeholders. Private sector payment behavior is more variable. Some companies pay promptly. Others stretch terms aggressively. Credit management is essential. Factoring and trade finance solutions are available but come at a cost that affects your bottom line.

The landscape continues to evolve. New entrants emerge. Some of the companies mentioned above have faced challenges. Merger and acquisition activity has increased. The top twenty list will look different in three years. What remains constant is the importance of understanding the regulatory environment, building local relationships, and maintaining operational discipline in a market that rewards preparation and punishes complacency. If you are evaluating opportunities here, focus on sectors with sustained government backing and clear demand drivers. Renewable energy, mining, tourism, healthcare, and digital infrastructure represent the most credible growth areas. Sectors dependent on discretionary consumer spending are more vulnerable to economic cycles. Real estate development outside the major cities carries execution risk that many investors underestimate. The market is not easy. It is not simple. But it is substantial, and the trajectory favors companies that approach it with patience and respect for local conditions. The businesses thriving today are the ones that figured that out early and stayed consistent.

