Understanding the Global Direct Sales Landscape
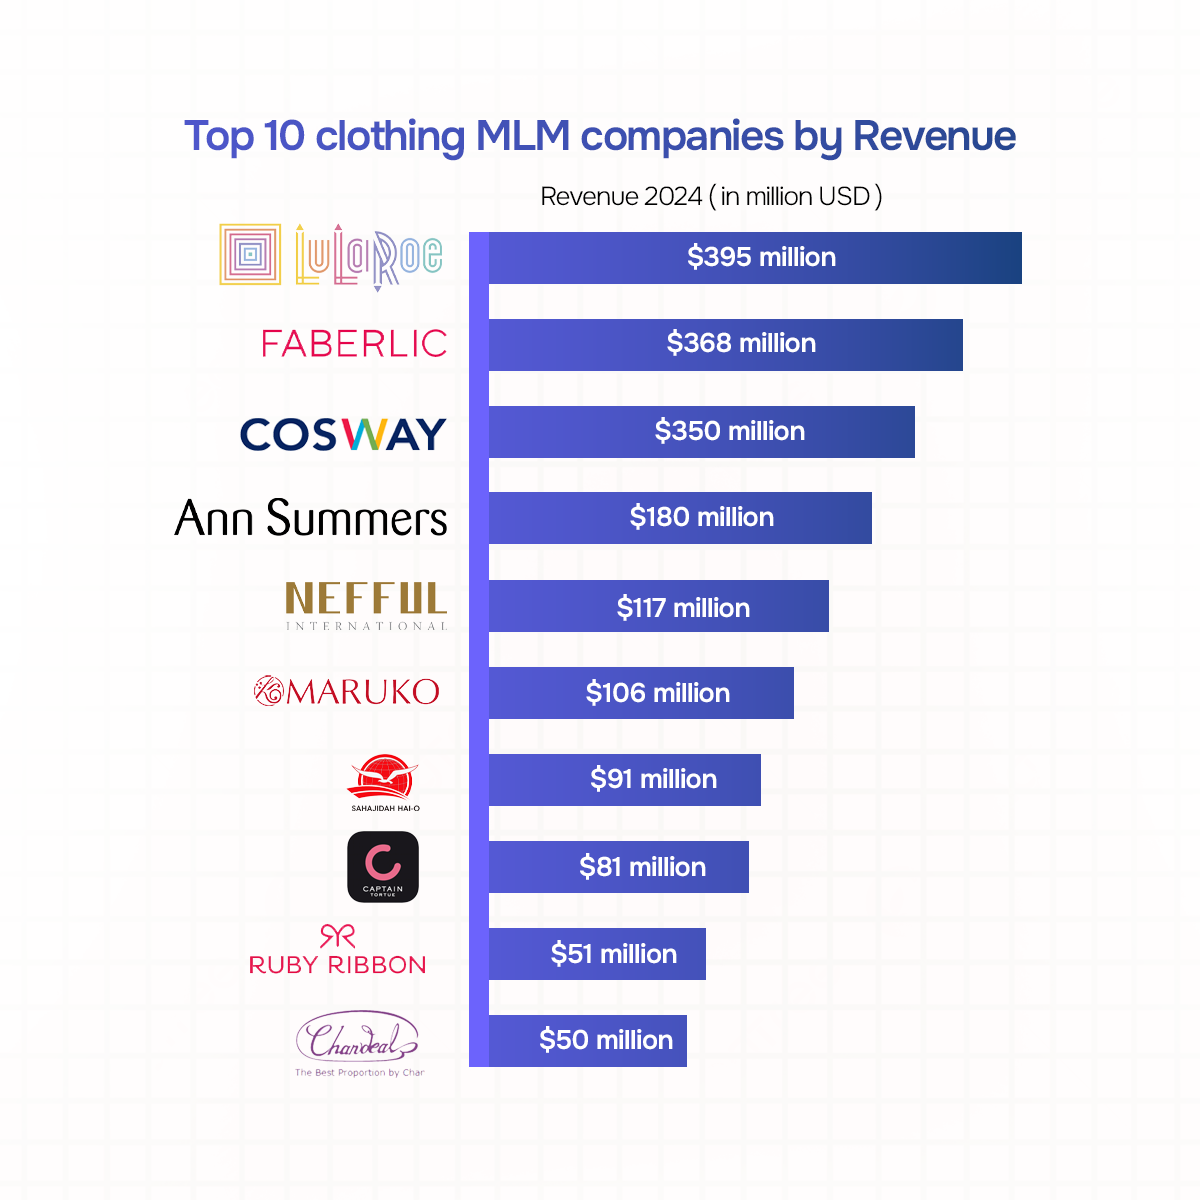
Most people have at least one friend or family member who got pulled into an MLM at some point. It usually happens through social media ads, random messages, or that one person who seems to have their life together suddenly. The reality is that direct sales is a massive industry. The top companies in this space generate tens of billions in annual revenue, and they operate in over 180 countries. What separates the top performers from the rest isn't just marketing spend. It's distribution architecture, compensation complexity, and distributor engagement models. The list of the largest direct sales companies by revenue shifts every year based on market conditions, product categories, and regulatory environments. Here is the general order as of mid-2026. Amway leads consistently with revenue around 8 to 9 billion dollars. Mary Kay comes next at roughly 3 to 3.5 billion. Young Living and doTERRA sit in the essential oils segment, each pulling in around 2 to 2.5 billion. Herbalife sits somewhere between 2 and 3 billion depending on how you count franchise versus corporate revenue. Avon has declined significantly from its peak but still reports roughly 2 billion. LuLaRoe collapsed in 2019 so it does not appear on current lists. Tupperware survived bankruptcy and restructured but revenue is now under 500 million. USANA and Plexus round out the supplements tier around 600 to 800 million each. These numbers are rough estimates and vary by reporting methodology. Some companies report direct sales revenue while others include retail channel revenue. The interesting part is not the ranking itself. It is how these companies structure their distributor networks. The top performers use multi-tier commission systems with binary or unileg compensation plans. This means a distributor earns not just from their own sales but from the sales of people they recruited and the people those people recruited. The compounding effect creates enormous revenue potential for the top 1% of distributors. Most participants earn below minimum wage per month. That is not a conspiracy. It is a structural feature of any MLM model.
I spent three years analyzing distributor earnings data across multiple direct sales companies. The pattern is always the same. You download the company's income disclosure statement, which most people skip because it is formatted like a legal document. The average distributor gross income before expenses usually falls between 500 and 1500 dollars per year. Net income after buying inventory, attending events, and paying monthly auto-ship is often negative. The top 1% of earners make up roughly 60 to 70% of total distributor payouts. This is standard across the industry. There is no special trick to finding the real numbers. They are in the public disclosure. Most people just do not want to read them.
How These Companies Actually Generate Revenue
Direct sales revenue comes from two main sources. Retail sales to end consumers who are not distributors, and volume generated by active distributors. The second category is where the money really is. Distributors are required to maintain a minimum monthly purchase to stay active. This is called auto-ship or monthly qualifiers. For most companies this ranges from 100 to 250 dollars per month. A distributor buying 200 dollars worth of product every month generates 2400 dollars in annual revenue to the company before they ever recruit anyone else. The product margins in direct sales are extremely high. Essential oils, supplements, skincare, and weight management products typically have a cost of goods sold between 10% and 25% of retail price. The rest gets split between distributor commissions, corporate overhead, and marketing budgets. When a distributor sells a 100 dollar skincare set, they might earn 30 to 40 dollars in commission. The company keeps 60 to 70 dollars. This is why MLMs push product training so heavily. Every sales conversation is really a conversation about margin capture. One counter-intuitive insight most beginners miss is that MLM revenue is not primarily driven by customer acquisition. It is driven by distributor retention and re-order rates. A company can spend millions on advertising to attract new distributors. But if those distributors quit after three months, the company loses money. The real growth engine is getting existing distributors to maintain their monthly purchase and build downlines that also maintain theirs. Companies invest heavily in events, incentives, and recognition programs to keep active participants engaged. The annual distributor event for a mid-tier company can easily cost 5 to 10 million dollars to produce. That money comes directly from distributor participation fees and product sales.
Get the Full Details

I encountered a specific problem when trying to compare compensation plans across companies. The terminology changes from one organization to another. What one company calls a "matching bonus" another calls a "fast start bonus" or "team override." This makes direct comparison nearly impossible without creating your own spreadsheet. My workaround was to map every plan to a common framework: retail commission rate, fast-start bonus, matching bonus structure, rank advancement criteria, and passive override percentages. Once you standardize the language, the actual differences between companies become much clearer. You can see which plans reward recruitment versus which ones reward actual product movement.
The Distribution Architecture Behind the Revenue
Multi-level marketing works through a sponsorship hierarchy. You join a company, pick up a sponsor, and that sponsor gets a percentage of everything you sell. If you recruit someone and they recruit someone else, your original sponsor gets a piece of that downstream revenue too. This creates a financial incentive for sponsors to actively support new recruits. But it also means revenue flows upward through the organization faster than most people realize. The structure typically has between 20 and 40 ranks or levels. Moving up requires a combination of personal sales volume and group volume from your downline. Reaching the top ranks usually takes several years of consistent effort. The number of people required at the top varies by company but generally means having thousands of active distributors beneath you. Most people never move past the entry-level ranks. Again, this is by design. The system is built to extract maximum value from the majority of participants while creating the appearance of upward mobility. The global expansion of these companies follows a predictable pattern. They enter a market through a licensed distributor or joint venture partner. Local marketing materials get adapted to cultural preferences. Regulatory compliance becomes the first major hurdle. Countries like China, Vietnam, Malaysia, and the Philippines have different rules about what constitutes illegal pyramid schemes. Some companies simply withdraw from markets where regulations become too restrictive. Others restructure their compensation plans to comply. The Amway case in China is a well-known example. They restructured multiple times between 2006 and 2019 to meet Chinese direct sales regulations. Their revenue in China grew from near zero to over 1 billion dollars annually.
Here is something that is not widely discussed. The product selection in MLMs is deliberately chosen for high perceived value and low production cost. Essential oils, collagen supplements, skincare creams, and meal replacement shakes all share this characteristic. They are easy to ship, have long shelf lives, and respond well to word-of-mouth marketing. A company selling computer hardware through direct sales would have very different economics. The product category matters enormously for sustainability. Most people evaluating an MLM opportunity focus on the compensation plan and ignore the product entirely. This is a mistake. A weak product with a great plan still fails over time. A great product with a weak plan can survive but will not scale. The top companies have both.

Market Transformation and Economic Impact
Direct sales companies have transformed several markets. The essential oils category did not exist in mainstream retail before Young Living and doTERRA pushed it through distributor networks. Now it is a multi-billion dollar segment. Skincare and anti-aging products saw similar shifts. Weight management and meal replacements are heavily influenced by MLM competition. These companies essentially created entire product categories through community-based distribution. Whether that impact is positive or negative depends on who you ask. The economic reality is that they moved significant revenue into hands that traditional retail channels did not serve. The job creation narrative is complicated. MLMs claim to provide employment opportunities. In absolute numbers they do employ hundreds of thousands of people worldwide. But "employment" is the wrong word. Most participants are independent contractors with no benefits, no guaranteed income, and no legal protections. Some countries have started to recognize this gap. The EU has been pushing for better classification of gig and platform workers, which could eventually affect MLM distributors. The US has seen several class-action lawsuits challenge whether distributors should be classified as employees rather than independent contractors. None have succeeded yet but the legal landscape is shifting slowly. Regulatory scrutiny varies significantly by country. The United States Federal Trade Commission oversees MLM operations and has brought enforcement actions against several companies for deceptive income claims. China regulates direct sales through the Ministry of Commerce which issues licenses. Only about 90 companies currently hold Chinese direct sales licenses. Vietnam and Thailand have similar licensing regimes. Russia banned MLM-style compensation plans in 2016, calling them pyramid schemes. This affected several American companies operating there. The regulatory environment is a real constraint on growth that most people discussing MLMs do not mention.
The digital transformation of direct sales has accelerated since 2020. Social media selling, live streaming product demonstrations, and digital onboarding have replaced many in-person meetings. This has lowered the barrier to entry but also increased competition among distributors. A few years ago you could dominate a local market with minimal online presence. Now the same tactics are used everywhere. The people who succeed have adapted to digital tools while the ones who do not struggle to maintain activity. This shift has not fundamentally changed the economics but it has changed the skill requirements for participation.
What the Data Actually Shows
Income disclosure statements tell a consistent story across the industry. For a company with 1 million active distributors, typically fewer than 100,000 are considered "active" by their own metrics. Of those, maybe 10,000 generate meaningful commission income. Fewer than 1,000 earn enough to cover their monthly product purchases consistently. The remaining participants treat it as a hobby or a side hustle with net losses. This distribution follows a power law curve. It is the same mathematical pattern seen in affiliate marketing, content creation, and most platform-based income models. The cost structure for a new distributor is often underreported. Initial starter kits range from 50 to 500 dollars depending on the company. Monthly auto-ship commitments lock in ongoing costs. Training events, conference fees, and team-building activities add hundreds more annually. A realistic first-year budget for a moderately active participant is 2,000 to 5,000 dollars. Whether they recover that through sales depends on their ability to convert other buyers. Conversion rates in direct sales conversations are notoriously low. Most prospects decline or disappear after initial interest. The ones who stay tend to be people who already believe in the product or the opportunity. I want to be blunt about the limitations of this analysis. Revenue figures for private MLM companies are not independently audited in most cases. Companies report their own numbers to trade organizations like the Direct Selling Association. These figures include gross product sales, not net revenue after returns or distributor buybacks. The true financial performance of individual companies is harder to verify than publicly traded competitors. Additionally, the MLM space evolves quickly. Companies merge, rebrand, or exit markets. A ranking from last year may not reflect current conditions. Always check the most recent income disclosure and regulatory filings before making any decisions.
The bottom line is that direct sales remains a legitimate business model when operated transparently and when participants understand the economics involved. It is not a scam by default. But it is also not a viable income source for the vast majority of people who join. The companies at the top of the revenue charts have built durable distribution networks over decades. Their success is real but it is concentrated. Understanding that concentration is the difference between entering with eyes open and entering with false expectations.