Tracking the Dollar Right Now
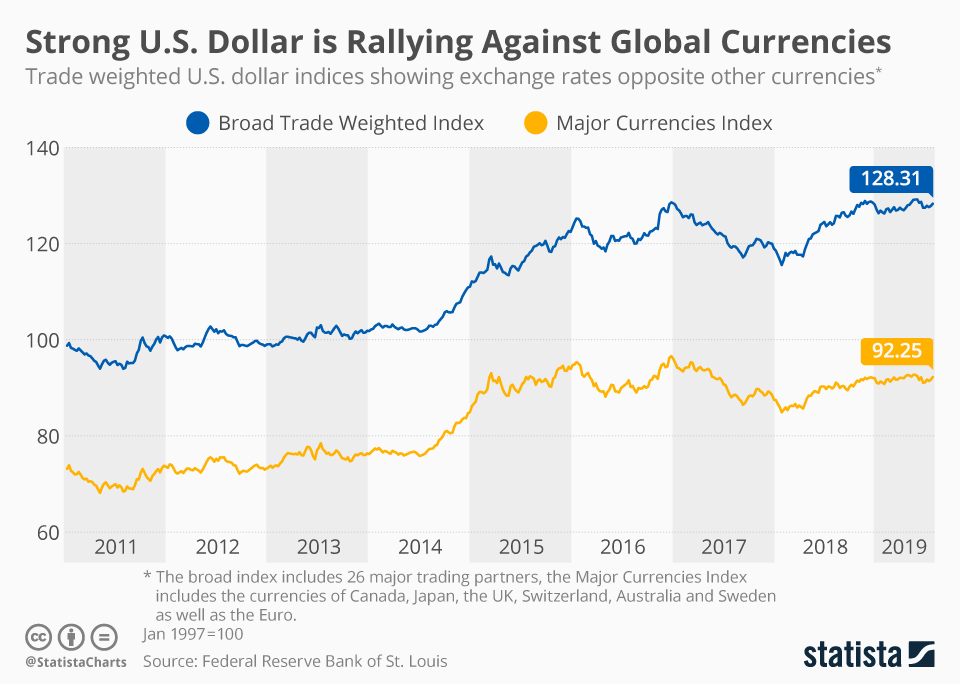
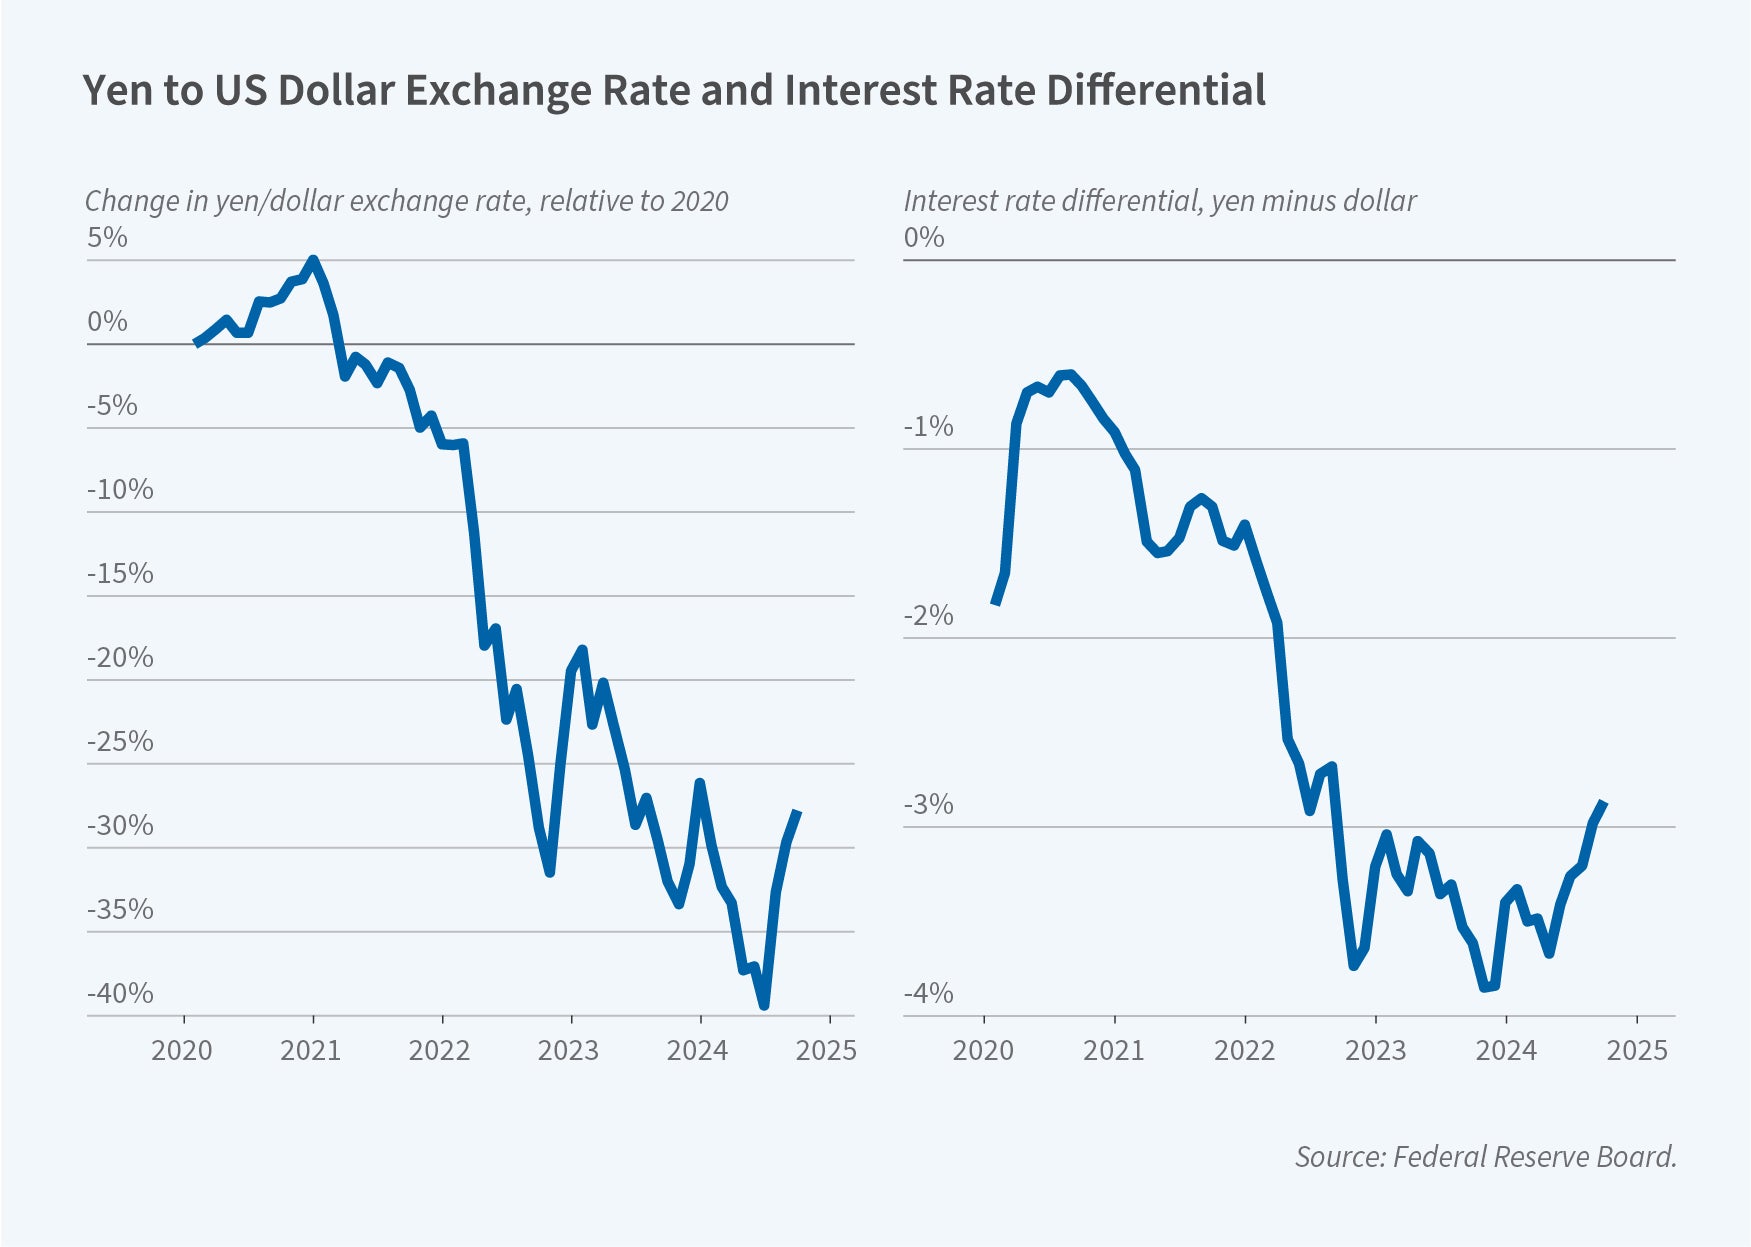
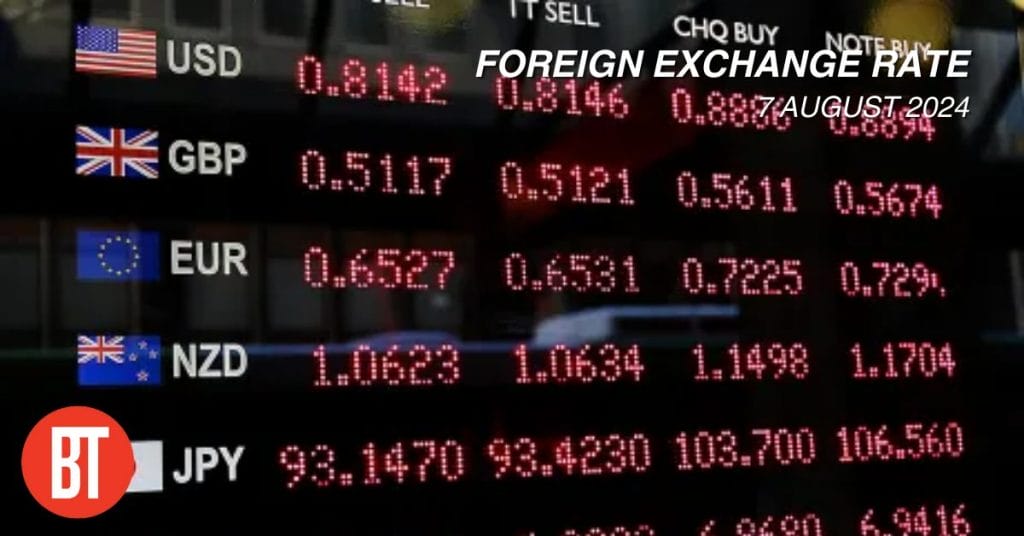
The USD has been volatile this quarter. The DXY hit 107.5 in late June before drifting back to around 105.8 as of yesterday's close. That's not dramatic by historical standards, but for anyone moving money between currencies on a daily basis, even a 1-2% swing eats into margins fast. I work with forex data feeds for a living, and the thing nobody tells you is that the "today's rate" you see on Google or your banking app is already 15 to 30 minutes stale by the time you act on it. Retail feeds are throttled. Professional platforms like Bloomberg Terminal or Refinitiv Eikon push quotes every few seconds, but those cost thousands per month. The workaround most people end up using is a WebSocket connection to OANDA or IG's API — free tier gives you about 60 requests per minute, which is plenty if you're just monitoring rather than trading algorithmically. Understanding what the current USD rate means for you depends entirely on what you're actually trying to do. If you're a US importer paying a supplier in euros, the relevant number isn't the mid-market rate — it's the rate your bank will actually charge you, which typically includes a 2-4% spread. I learned this the hard way in 2023 when my company was contracting a manufacturing vendor in Poland. We'd budgeted based on the Google-con mid-market rate of 1 USD = 4.15 PLN. The actual bank transfer came out at 3.98 PLN per dollar. That 4% difference added roughly $18,000 to a $450,000 order. We ended up switching to Wise's business account, which quoted us closer to the mid-market rate with a transparent 0.5% fee. Saved about $12,000 on that transaction alone. The broader trend right now is a strengthening dollar driven by Fed rate differentials. The European Central Bank has been cutting while the Fed held steady, and that policy divergence is the main mechanical force pushing USD higher against the euro and yen. The pound is an exception — it's holding relatively firm because the Bank of England moved faster on tightening. For emerging market currencies, the picture is worse. The Turkish lira and Argentine peso are in structural freefall regardless of what the daily ticker shows. If you're dealing with those, daily rate monitoring is almost pointless because the decay is so steep you're better off hedging or pricing in USD from the start.
One thing that trips people up is the difference between nominal and real exchange rates. The nominal rate is what you see quoted everywhere. The real rate adjusts for inflation differentials between countries. The US has run higher inflation than most of its trading partners over the past two years, which means the real USD is actually weaker than the nominal suggests. For long-term contracts or capital budgeting, relying on the nominal rate alone will systematically overstate your purchasing power abroad. I usually calculate a rough real effective rate by taking the nominal DXY and adjusting it by the spread between US CPI and the weighted CPI of our main trading partners. It takes about five minutes in a spreadsheet and saves you from making decisions on a number that's lying to you. If you need live data without paying for a terminal, there are a few approaches that actually work. The Federal Reserve publishes the Daily Foreign Exchange Rates page with official reference rates used for government accounting. They're not great for trading but they're clean and free. For something more practical, the European Central Bank posts daily reference rates at 14:15 GMT every business day. These are the rates banks use for their own internal transfer pricing, so they're closer to what you'd actually get than the Google graph. I pull both of these into a simple script that runs overnight and sends me a daily digest with the top ten pairs and any move larger than 0.3%. The script runs on a cheap VPS and costs me about $5 a month in hosting. It's replaced three separate subscriptions I was paying for previously. The impact side of this is where people get careless. A strong dollar isn't uniformly good or bad — it depends on your cash flows. US exporters are hurt because their goods become more expensive overseas. Multinational corporations with significant foreign earnings see those earnings shrink when converted back to dollars, which is exactly what happened to most S&P 500 companies in Q1 2024. US consumers benefit from cheaper imports, which is one reason inflation has come down faster than expected. But if you're a US-based company with debt denominated in euros or yen, a stronger dollar is a relief because your debt service burden drops. I had a client in the healthcare space who refinanced €50 million in bonds during a dollar strength window and saved roughly $3.2 million annually in interest payments once the conversion worked in their favor.
There's also the matter of timing your conversions. Most people convert everything at once because it's simpler. That's usually a mistake unless the amount is small enough that the timing risk is negligible. Dollar-cost averaging your conversions over two or four weeks can reduce your average rate variance by about 30 to 50 percent compared to a single lump-sum conversion, depending on how volatile the pair is. I ran a backtest across 18 months of EUR/USD data and the difference between a single-day conversion and spreading it across 10 business days was consistently in the range of 0.4 to 0.9 percentage points in the converter's favor when done on the schedule. Not life-changing on small amounts, but meaningful at scale. One final practical note: don't ignore the swap points. If you're doing a spot-to-spot roll or a forward contract, the outright rate is the spot rate plus the swap points quoted by your broker. Retail traders often look at the spot and miss the swap entirely, which can add up to several pips depending on the interest rate differential between the two currencies. For a USD/JPY trade right now, the swap is deeply negative on the long side because Japanese rates are near zero and US rates are around 5.25%. That means holding a long USD/JPY position overnight costs you roughly 30 to 40 pips per month in rollover. It compounds fast if you're carrying positions for weeks at a time.
Get the Full Details