What You Actually Get To Keep In Tennessee
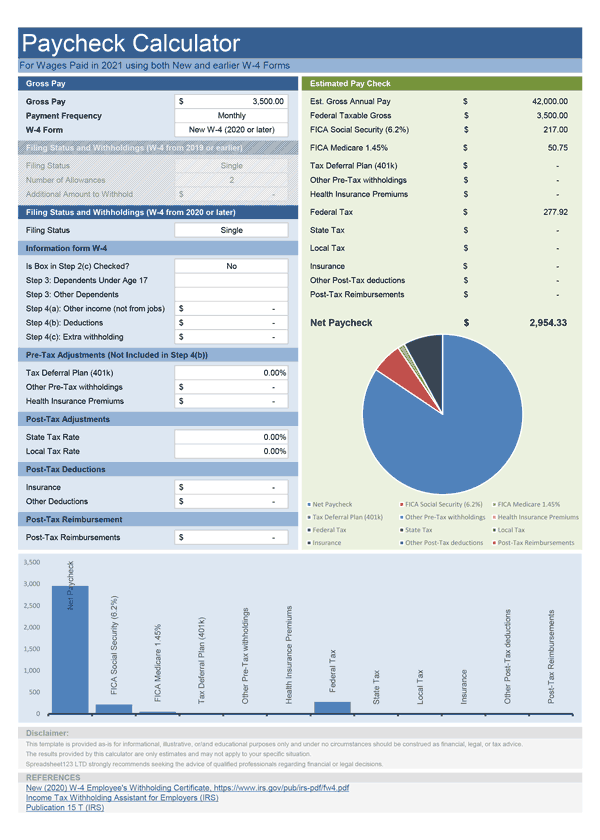
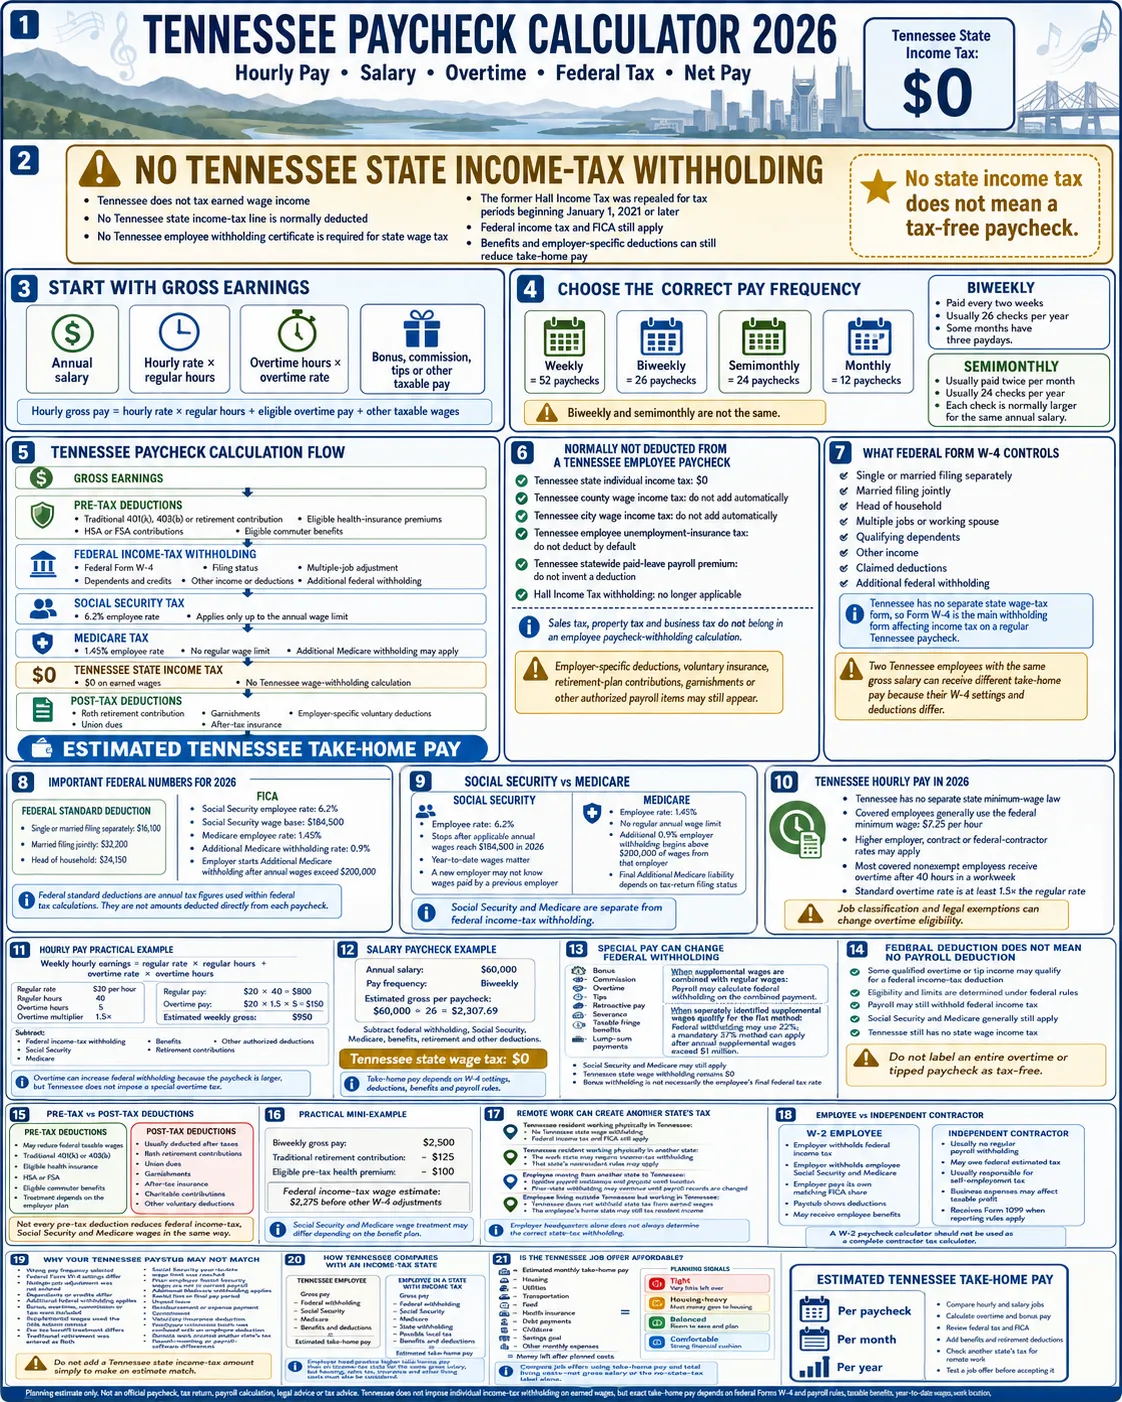
Tennessee does not tax wages, which sounds like a win until you realize most people still have money taken out of every check without understanding why. The average worker sees roughly a dozen line items on a payslip and has no idea which ones are mandatory, which ones are optional, and which ones vary based on filing status or benefit elections. That is where a proper calculator matters. It stops you from guessing and gives you something close to reality. Here is how I use this kind of tool day to day when I am helping someone figure out what their pay actually looks like after deductions. It is not glamorous but it works. I enter gross pay, pay frequency, filing status, pre-tax election amounts, and any local taxes or garnishments, then review the output against what the person's actual check shows. The difference is usually within a few dollars if the inputs are accurate. You start with gross pay. That is the number before anything comes out. Then you subtract pre-tax deductions first because they lower your taxable base. Things like a 401(k) contribution, health insurance premiums under a cafeteria plan, or HSA funding all reduce the amount of federal and state income tax you owe. Wait, Tennessee does not have a state income tax on wages, so you only have federal income tax and FICA to worry about there. But you still have local options and special income taxes that trip people up.
FICA is the big one most people confuse. It is Social Security at 6.2 percent and Medicare at 1.45 percent, both split evenly with your employer. You pay 7.65 percent total out of every paycheck, and it applies up to the Social Security wage base, which changes every year. The Medicare portion has no cap, and there is an additional 0.9 percent Medicare surtax that kicks in for high earners above certain thresholds. That extra slice is something most paycheck calculators handle automatically, but you need to make sure yours does. Federal withholding uses your W-4 form. The calculator pulls the percentage or bracket your allowance setting implies, then applies the IRS wage bracket or percentage method tables. State withholding for Tennessee is effectively zero for wage income, but the tool still needs to account for that zero properly so it does not accidentally apply a placeholder rate.
A Real Edge Case I Hit
One of my clients had a check that looked wrong. He saw a deduction labeled "intangible income tax" and assumed the state was taxing his salary. It was not a salary tax. He was working from home in Tennessee but his employer's payroll system classified part of his compensation as investment-linked income due to a stock option structure. Tennessee does tax certain intangible income, and the payroll vendor mapped it to a line item that nobody explained to him. I walked him through the breakdown. The calculator shows the main wage tax as zero, which is correct, but the edge-case bucket sits under a separate category. If you only look at the top line of a simple calculator output, you miss that entirely. The workaround is to verify your compensation type with payroll and confirm whether any portion falls under intangible or interest income rules. Once we adjusted the classification in the calculator, the projected net matched his actual check exactly.
Get the Full Details
What People Usually Miss
Most beginners treat a paycheck calculator like a yes-or-no machine. They plug in numbers and believe the result. The problem is that deductions are rarely static. If you change your 401(k) contribution mid-year, your withholding resets. If you add a dependent, your federal bracket shifts. If your employer switches to a different benefits provider, your pre-tax health premium may jump by a fixed dollar amount each period. All of that changes your take-home significantly. Another blind spot is the local tax layer. Tennessee itself does not levy a wage tax, but some municipalities and special districts have their own levies or fees. These are not common county-wide, but they exist in certain jurisdictions and can add a couple of dollars per check or more depending on your city and employer classification. A thorough calculator will ask for your municipality or at least prompt you to verify local withholdings.
Common Pitfalls
The most frequent error I see is people entering their annual salary when the tool expects a per-paycheck amount, or vice versa. If you are biweekly and you type in your yearly number without dividing, the calculator will spit out a tiny take-home figure that looks terrifying. Another mistake is ignoring the Social Security wage base. If you receive a large bonus near year end that pushes your year-to-date wages above the limit, Social Security stops withholding. Calculators that only project a single pay period will not show that shift unless they include year-to-date tracking. Then there is the misconception that Tennessee means zero tax altogether. That is only true for wage income. If you have rental income, capital gains, or certain trust distributions that flow through your personal return, Tennessee may still tax those under its intangible income provisions. A paycheck calculator will not cover that, and you need a separate tax tool or a professional if you are dealing with mixed income sources.
How To Use This Thing Properly
Enter your gross pay for the exact pay period. Select your pay frequency. Choose your filing status as shown on your W-4. Input your pre-tax contributions and benefit elections. Add any after-tax deductions. Include local taxes if your employer reports them. Review the federal income tax, Social Security, and Medicare lines. Compare the final net to your last actual paycheck. If the variance is more than five dollars, go back and check each input for typos or missed deductions. Keep your calculator updated when the IRS releases new withholding tables. Those come out annually and can shift your federal tax by a small but measurable amount. Using outdated tables is one of those quiet errors that makes your projection slightly optimistic and causes a small surprise at tax time.
When The Tool Falls Short
A paycheck calculator is a projection, not a guarantee. It assumes your current deductions and status stay constant. It does not capture retroactive pay adjustments, leave without pay, or unreported garnishment changes. If your employer processes retroactive wages in a single paycheck, the tax brackets can shift temporarily and create a mismatch between the projected and actual net. In those cases, the best approach is to run the calculator for the adjusted gross, then reconcile with payroll after the fact. Also, calculators struggle with equity compensation. Stock option exercises, RSU vesting, and employer matching contributions often require manual entry because they do not follow standard withholding rules. If your compensation includes significant equity, treat the calculator as a baseline and ask payroll for a detailed breakdown of those specific items.
Bottom Line
A Tennessee paycheck calculator strips away the guesswork for standard wage income. You get a clear picture of federal tax, FICA, and pre-tax deductions, and you see why your net is what it is. The tool is only as good as the inputs you feed it. Verify your classification, watch for edge cases like intangible income mappings, and understand that special compensation types will need manual adjustment. After that, it is a reliable way to project your take home without waiting for payday.