Understanding Tennessee Paycheck Calculations
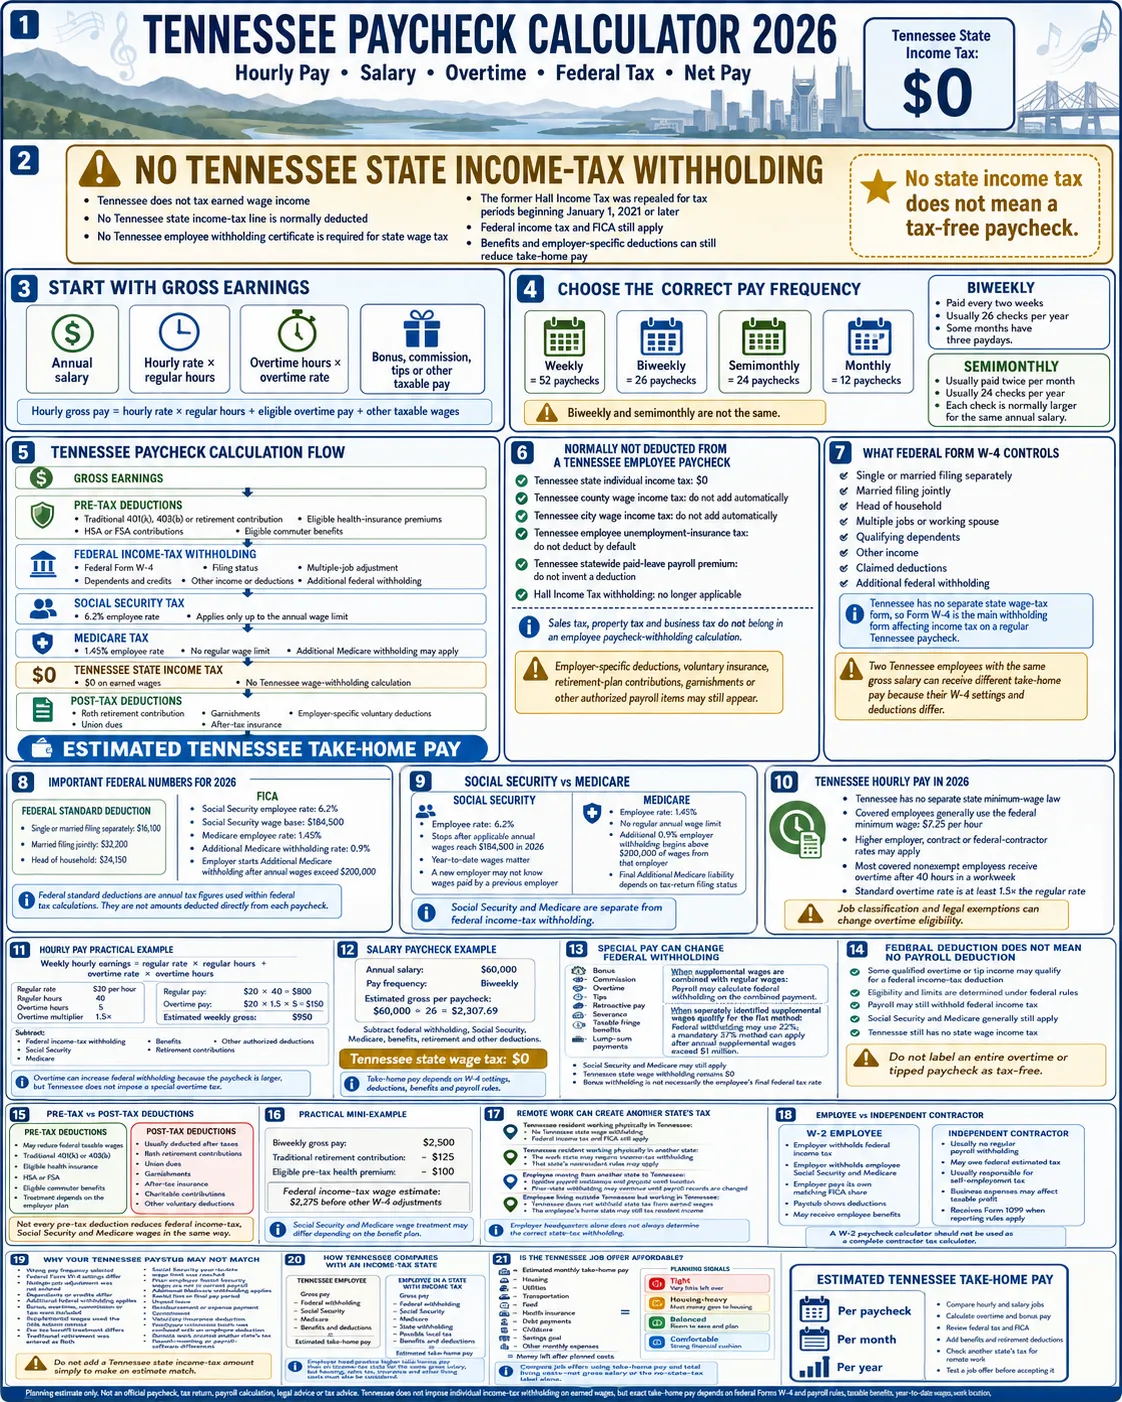
Tennessee doesn't have a state income tax on wages. That's the single most important fact you need to know before doing any paycheck math here. Most people arrive at this point confused because their online calculators still seem to pull deductions from thin air. The reason is usually federal withholdings, FICA, or employer-specific benefits that the calculator assumes but the state actually doesn't touch. I spent three years running payroll for a small staffing firm across two states, and Tennessee was the part that made people uncomfortable. They kept expecting it to work like North Carolina or Georgia. It doesn't. You file fewer forms. You calculate fewer things. That simplicity is what causes the most mistakes because people assume they can skip the steps that still actually matter.
Tn Paycheck Calculator The Definitive Guide To Navigating Tennessee Takehome Pay
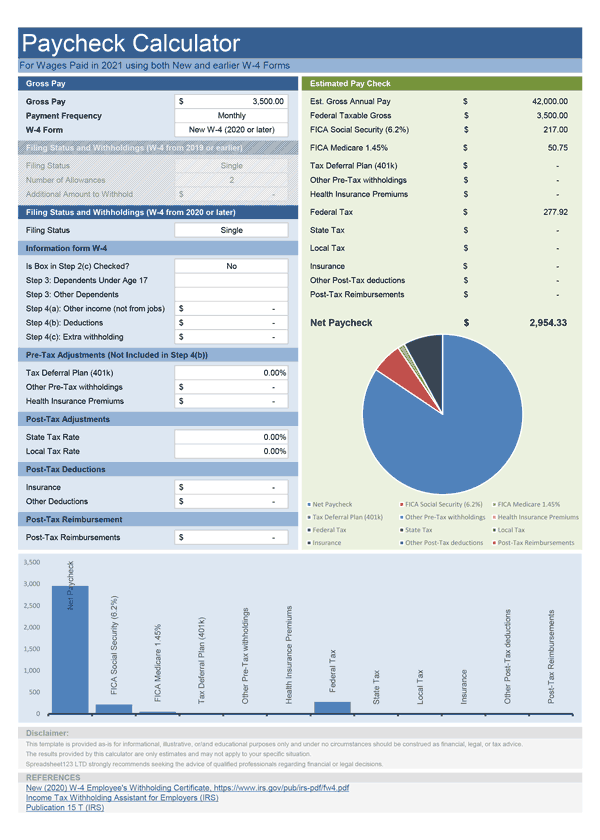
When you plug a gross salary into a Tennessee paycheck calculator, the result will be higher than for the same salary in a state with income tax, obviously. But the calculator still needs to account for the standard pieces. Federal income tax depends on your W4 filing status and any extra withholding amounts you entered. Social Security comes out at 6.2 percent of gross wages up to the annual taxable maximum, which is $168,600 for 2023 and stays around there. Medicare is 1.45 percent with no ceiling, and if you make over $200,000 single or $250,000 married, there's an additional 0.9 percent Medicare surtax that a lot of basic calculators ignore. The trick with Tennessee is that once you strip out the state income tax line, what's left is just the federal side plus whatever your employer deducts. Health insurance premiums, 401k contributions, wage garnishments, club dues, union fees. All of that still applies. The absence of one line item doesn't erase the rest of the structure. I ran into a real problem with a client who was comparing his Tennessee takehome against what he used to make in Texas. The Texas figure included a state tax line that showed zero, which made him think something was broken in the Texas calculator. It wasn't broken. It was just doing nothing, which is functionally identical to not having the line at all. I told him to add a side column labeled "state tax" with actual zeros for both states so he could see that the difference in his paycheck came entirely from federal bracket differences and his particular W4 selections, not from any Tennessee quirk. That visual fixed the confusion in about five minutes.
How the Calculation Actually Works Step by Step
Start with your gross pay. For a salaried employee this is straightforward. For hourly workers you need to account for overtime first. Tennessee follows the standard federal overtime rule: time and a half after 40 hours in a workweek. There is no state-level overtime law that differs from the Fair Labor Standards Act, so you don't need a separate calculation for that. Subtract pre-tax deductions. These reduce your taxable income for federal purposes. A traditional 401k, a health FSA, or a dependent care FSA all come out before federal tax is calculated. Tennessee follows federal adjusted gross income rules for its own tax calculation, which is a non-issue since the rate is zero, but it matters for understanding why your takehome looks the way it does on a pay stub. Calculate federal income tax using your W4 data. The percentage method or the wage bracket method from the IRS circular E-531 is what employers use. If you're doing this manually without software, you'll need the latest IRS tables. The 2024 tables shifted a few brackets due to inflation adjustments, and anyone working from 2022 or 2023 tables will get numbers that are slightly off.
Get the Full Details
Apply FICA. Social Security at 6.2 percent on wages up to the annual limit, Medicare at 1.45 percent on all wages, and the additional Medicare tax if you cross the threshold. These are employer-matched, meaning your employer pays another 6.2 percent and 1.45 percent on top of what comes out of your check. That doublesided number is why FICA shows up as roughly 12.4 percent of your gross even though you only see half of it deducted from your paycheck. Subtract post-tax deductions. Roth 401k contributions, wage garnishments, student loan repayments, court-ordered payments. These come out after everything else and don't affect your taxable income. They just reduce what lands in your account.
Common Pitfalls That People Miss
The biggest mistake I see is assuming that because Tennessee has no state income tax, local taxes don't exist. Some counties in Tennessee have local income taxes or business taxes that can indirectly affect your paycheck if your employer is structured a certain way, though this is rare for standard W2 employees. More commonly, people forget about local school taxes in neighboring states when they commute across a border. I had someone in Memphis who drove into Arkansas for work and didn't realize Arkansas withheld state tax on those earnings. His Tennessee calculator showed one number and his actual bank deposit showed another. The gap was Arkansas. Another issue is the annualized nature of Social Security. If you change jobs mid-year, both employers will withhold Social Security tax up to the limit each time. You end up paying excess Social Security tax and have to claim it back on your annual return. The paycheck calculator can't warn you about this because it only sees one pay period at a time. I learned this the hard way when a temp worker came to me every January asking why her refund was $1,000 less than expected. She'd worked two jobs the prior November through December and both had hit the cap. She just didn't connect the dots. Calculated overtime errors are the third common problem. Some systems round hours differently. One employer I worked with rounded to the nearest quarter hour at the start of the shift rather than the end. Another rounded to the nearest tenth. Over a year, these rounding methods can create a difference of several hundred dollars in gross pay. The calculator doesn't care which method you use as long as you tell it which one. If you don't, it defaults to the most common method, which might not match your employer's actual practice.
When Calculators Fail and What to Do Instead
Paycheck calculators are useful for estimates. They are not authoritative. If you need to verify an actual payroll run, you need the payroll provider's documentation or the IRS publication 15-K if your employer uses the percentage method. For high-income earners with multiple income streams, stock options, or significant pre-tax deductions, online calculators will give you numbers that look reasonable but are often off by a meaningful margin. In those cases, pulling your most recent pay stub and reverse-engineering the deduction lines is more reliable than trusting a web tool. I also recommend keeping a spreadsheet with your actual pay stubs for at least two years. Tennessee has no state withholding to reconcile, but federal overwithholding and FICA overwithholding from job changes are easy to miss if you're not tracking them. A simple sheet with date, gross pay, federal tax withheld, Social Security withheld, Medicare withheld, and takehome will show you patterns that no calculator reveals.
Bottom Line
Tennessee takehome pay is simpler to calculate than in most states because you drop the state income tax line and move on. The federal side and FICA remain unchanged. The difficulty isn't in the math. It's in the assumptions people bring to it. They expect a zero state tax to mean a dramatically different calculation when it mostly means a different final number on an otherwise identical spreadsheet. Once you accept that, the rest is just following the standard withholding process with more attention to the items that still matter.