The TJ Maxx Credit Card Is Basically a Points Accumulator With Some Nice Perks
Let me walk through how the TJ Maxx rewards credit card actually works, because a lot of people treat it like a magic money machine. It isn't. But it does work if you understand the structure. The card is issued by Comenity Bank. There are two versions: the TJX Rewards Credit Card (store-only, usable only at TJ Maxx, Marshalls, HomeGoods, and HSN) and the TJX Rewards Mastercard, which works everywhere. The rewards structure is different between the two, and that matters more than most people realize.
Tjmaxx Credit Card Pay Unlocking Exclusive Benefits And Rewards
Here is how the rewards actually break down. With the store card, you earn 7% in rewards on every purchase at TJ Maxx, Marshalls, HomeGoods, and Sierra. That is not points that turn into dollars immediately. It is reward certificates that accumulate in your account until you hit thresholds. Once you reach certain point levels, you get a certificate. You then have to manually redeem it at checkout. It does not apply automatically. I learned this the hard way during a $200 home goods order where I had 400 reward points sitting in my account from previous purchases. I checked out without realizing the certificates needed separate redemption, and the cashier had no idea what I was talking about. The workaround is simple: log into your Comenity account beforehand, go to the rewards section, select the certificate you want to use, and note the confirmation code. Bring that code to the register and ask the associate to apply it before scanning items. The Mastercard version gives you 5% back at TJ Maxx and related stores, 2% at gas stations and restaurants, and 1% everywhere else. The 5% is lower but it compounds differently because it posts directly to your statement balance rather than requiring certificate redemption. Some people prefer the instant statement credit model. Others prefer stacking multiple certificates for big purchases. Both strategies are valid. The signup bonus is usually $10 in rewards after you spend $50 within the first 90 days. That is easy to hit if you are already shopping there. But here is where people get confused. The $10 is not cash back. It is a reward certificate with a minimum spend requirement attached. You typically cannot use it on your very first purchase unless that purchase meets the threshold and the certificate terms allow it.
How Payments and Rewards Interaction Actually Works
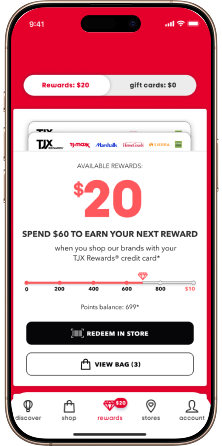
This is the part most guides skip. When you make a purchase with the card, the rewards accumulate in your Comenity account. You can check your balance at any time through the app or website. The certificates have expiration dates, usually around 12 months from issuance. If you let them expire, you lose that money. I once had $25 in certificates expire because I forgot to check my account. Worth noting: certificates do not earn interest. They just sit there until you use them or they vanish. For paying off the card itself, there is no special unlock mechanic. You pay your bill like any other credit card. The "unlocking" language in the topic title refers to the rewards benefits that become available once you open the account and start using it. There is no hidden tier system or secret payment method. You spend, you earn, you redeem. One edge case worth mentioning: if you return an item you bought with the card, the rewards points for that purchase are deducted from your account. If you had already redeemed a certificate and used it toward that purchase, the certificate value is also clawed back. This can create a weird situation where your reward balance goes negative temporarily. It corrects itself on your next billing cycle, but it is annoying. I recommend waiting until all pending returns post before redeeming certificates.
Get the Full Details
Common Pitfalls That Beginners Miss
First, the approval odds. Comenity has tightened their underwriting significantly over the past few years. If you have a thin credit file or recent hard inquiries, you may get denied even with good credit. This is worth checking your eligibility through their soft pull tool before applying, because a hard pull hurts your score temporarily. Second, the APR. The current rate sits around 25.99% variable. If you carry a balance month to month, the rewards earnings will not come close to offsetting the interest charges. This card only makes financial sense if you pay it off in full every billing cycle. I have seen people earn $30 in rewards over three months and then lose $80 in interest because they only made minimum payments. Do not let that happen to you. Third, stacking rewards with clearance. TJ Maxx clearance items sometimes already have discounts deep enough that the 7% reward certificate adds marginal value. A quick calculation before buying helps. If an item is already 50% off and you would earn roughly $3.50 in rewards on a $50 purchase, ask yourself whether waiting for a bonus reward point event or using a promo code would be more valuable.
Fourth, the certificates often have restrictions. Some require a minimum purchase amount. Some exclude certain categories. The fine print on each certificate varies, and Comenity does not always make this obvious. Always read the certificate terms before assuming you can use it on any purchase.
When This Card Makes Sense and When It Does Not
If you shop at TJ Maxx, Marshalls, or HomeGoods at least twice a month and pay your balance in full, this card is a solid choice. The 7% return on store purchases is genuinely competitive compared to most general cashback cards that top out at 2-3% on categories like groceries or dining. For someone spending $400 monthly at these stores, that is $28 in annual rewards, which is meaningful. If you shop there once every few months, the card is not worth opening. The signup bonus requires $50 in spending, which is easy, but the ongoing rewards become irrelevant if your visit frequency is low. In that case, a standard cashback card with no annual fee and broad 1.5-2% returns is probably better. You avoid the complexity of managing certificates and expiration dates. There is also the consideration that the store card only works at TJ Maxx family stores. If you want flexibility to use rewards at other retailers, the Mastercard is the way to go. The tradeoff is the lower 5% rate at TJ Maxx versus the 7% on the store card. It depends on how much you value flexibility versus maximum returns at these specific stores.
One final note about the application process. You can apply online at the TJ Maxx website or through the TJ Maxx app. The decision is usually instant. If approved, you get a virtual card number immediately, which you can use for online purchases right away while your physical card arrives in the mail. This is convenient if you want to start earning rewards without waiting for delivery.