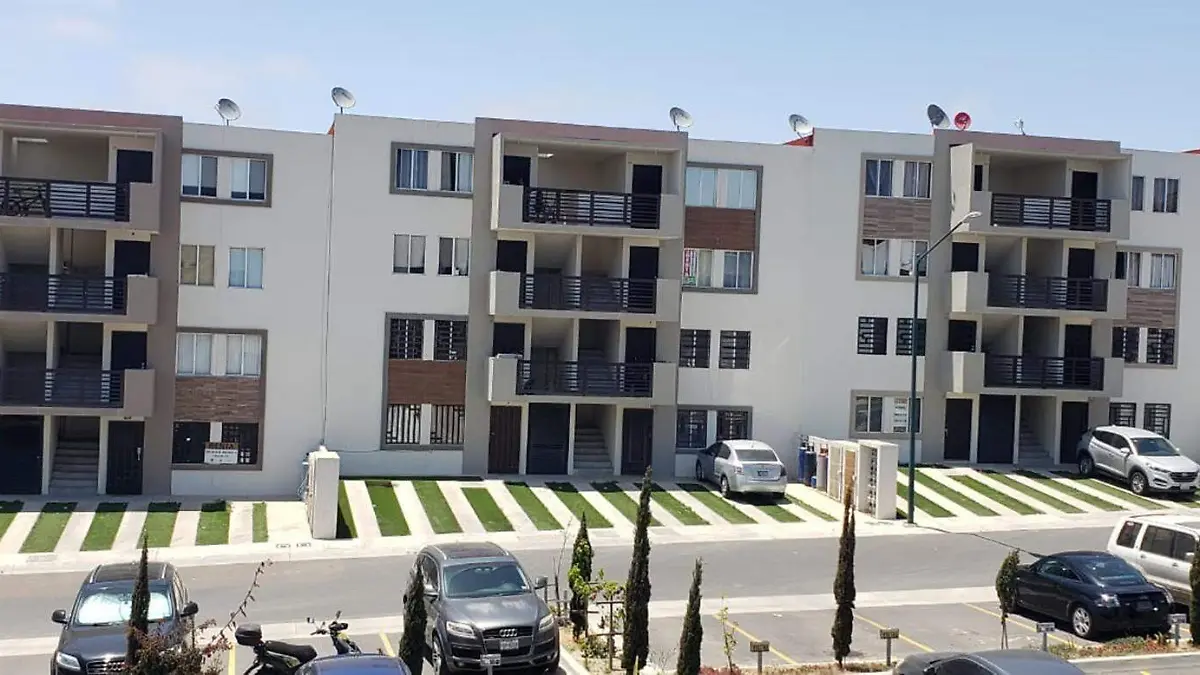
Infonavit In Tijuana Is A Different Animal
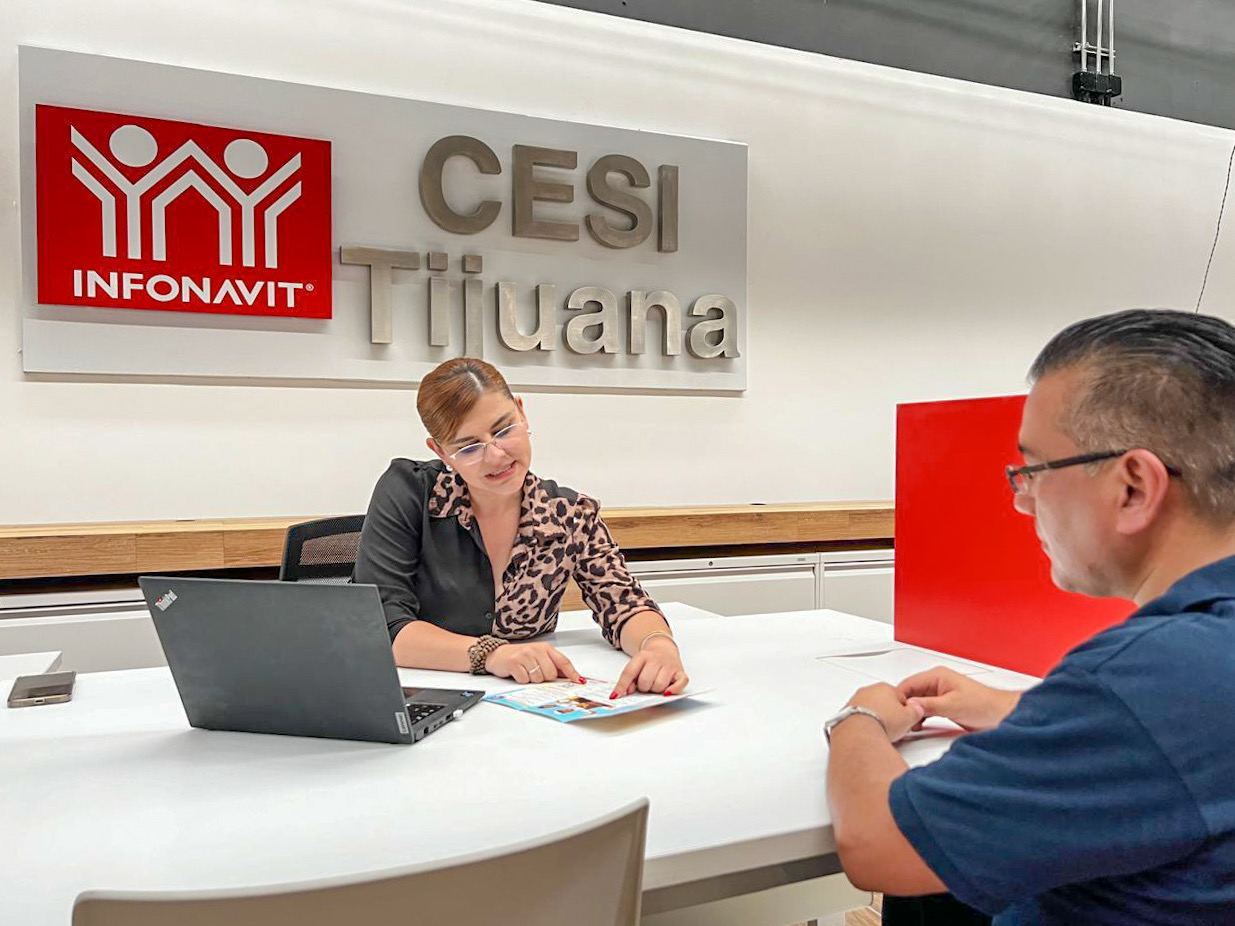
If you have dealt with INFONAVIT loans anywhere else in Mexico and then show up at the Tijuana regional office, you will quickly realize the paperwork moves differently here. The border location changes everything. Demand is higher. Turnaround times are different. And the staffing situation is not what you will find in Guadalajara or Monterrey. I spent about nine months helping a client navigate an INFONAVIT home purchase near the zone industrial de tijuana area. What I learned does not match the brochure you get on their website.
Tijuana De Tipo Infonavit Cmo La Sede Regional Revoluciona La Vivienda En La Ciudad Fronteriza
The regional office has been pushing newer digital processes faster than some other regions. They started accepting more submissions through the app before other offices caught up. That means fewer trips to the physical location. But it also means you need your documents scanned correctly the first time, because once something gets flagged in the system, getting it corrected can take two to three weeks instead of the usual five business days you might see elsewhere. One thing nobody tells you about INFONAVIT loans in Tijuana is that property appraisals take longer than in other cities. I had an appraisal scheduled for a unit in zona metro and the appraiser was rescheduled twice before finally showing up. The second attempt added eleven days to my timeline. This happens because there are fewer certified appraisers operating in the metropolitan area compared to cities like León or Querétaro. Here is what most people miss when applying. Your income documentation needs to cover at least the last six months, but if you are self-employed, they want to see your most recent SAT tax filing and sometimes the prior year as well. Self-employed applicants in Tijuana get flagged for additional review more often than in other regions, probably because border income structures look different on paper. I had a client who ran into this exact issue. His workaround was to bring a CPA-certified statement from his accountant along with his regular pay stubs, and it cleared the review in about four days instead of the standard three to four weeks.
The loan limits are another thing to watch. INFONAVIT raised their maximum loan amounts recently, but the higher tiers require a longer contribution history. If you have been contributing for less than thirty-six months, you might qualify for a lower bracket even if your salary would support a bigger loan. I saw this trip up someone who assumed their monthly salary alone determined their ceiling. It does not. The system weights both income and contribution history. There is a practical bottleneck with cross-border income. If you earn part of your salary in pesos from a US employer and part in Mexico, INFONAVIT will typically only count the Mexican payroll income. I know this sounds obvious, but several people I worked with expected the border wages to count toward their qualification. They did not. One workaround that actually works is having your US income formally documented through a stamped contract and showing consistent deposits into a Mexican bank account for at least six months before applying. It is not guaranteed to work, but it has helped a few clients bump their qualification tier up. The new digital channels at the Tijuana office are real but still uneven. The app lets you track your application status in near real-time, which is useful. However, the document upload feature has a file size limit and sometimes rejects PDFs that are perfectly fine on desktop. If your scan gets rejected, try compressing it with a tool like SmallPDF or just take a photo with your phone camera instead of uploading a scan. Weird but effective.
Get the Full Details
Another detail that saves time is knowing your UMIS balance before you apply. You can check this online in about five minutes. Your UMIS (Unidad de Medida y Sustento) score affects your loan calculation. If your UMIS number is outdated or shows an error, fixing it before you submit your application prevents a delay that could cost you ten to fourteen extra days. I have seen this slow down applications more than anything else. If you are working with a constructor or developer on a new project, make sure they are registered with INFONAVIT as an authorized producer. Not all builders in Tijuana are, and if yours is not, you cannot use your INFONAVIT credit for that unit. This comes up more often than you would think with newer developments popping up in areas like cerro colorado and el rosario.
What Actually Works When Things Stall
When an application gets stuck, do not just wait. Call the regional office directly and ask for the folio number and the specific reason for the hold. Generic responses like "en proceso" are not helpful. I usually push for a direct answer about whether it is a document issue, an income verification problem, or a property appraisal delay. Getting that specificity cuts down on waiting time significantly. The office is located near the centro area and has extended hours on certain weekdays, but showing up without an appointment rarely helps. They do accept walk-ins for basic inquiries, but for anything involving an active application, you need to be scheduled. The online scheduling system at infonavit.gob.mx works, but slots fill up within hours during peak seasons like January and February when applications spike. One final thing. Do not assume your broker or real estate agent knows the current INFONAVIT procedures inside out. A lot of them learned their process years ago and have not kept up with the recent digitization changes. I have watched good agents waste two to three weeks on applications because they were still using outdated document checklists. If you are handling this yourself, stay on top of the official website for updates rather than relying solely on third-party advice.