What Tiger Score Actually Is
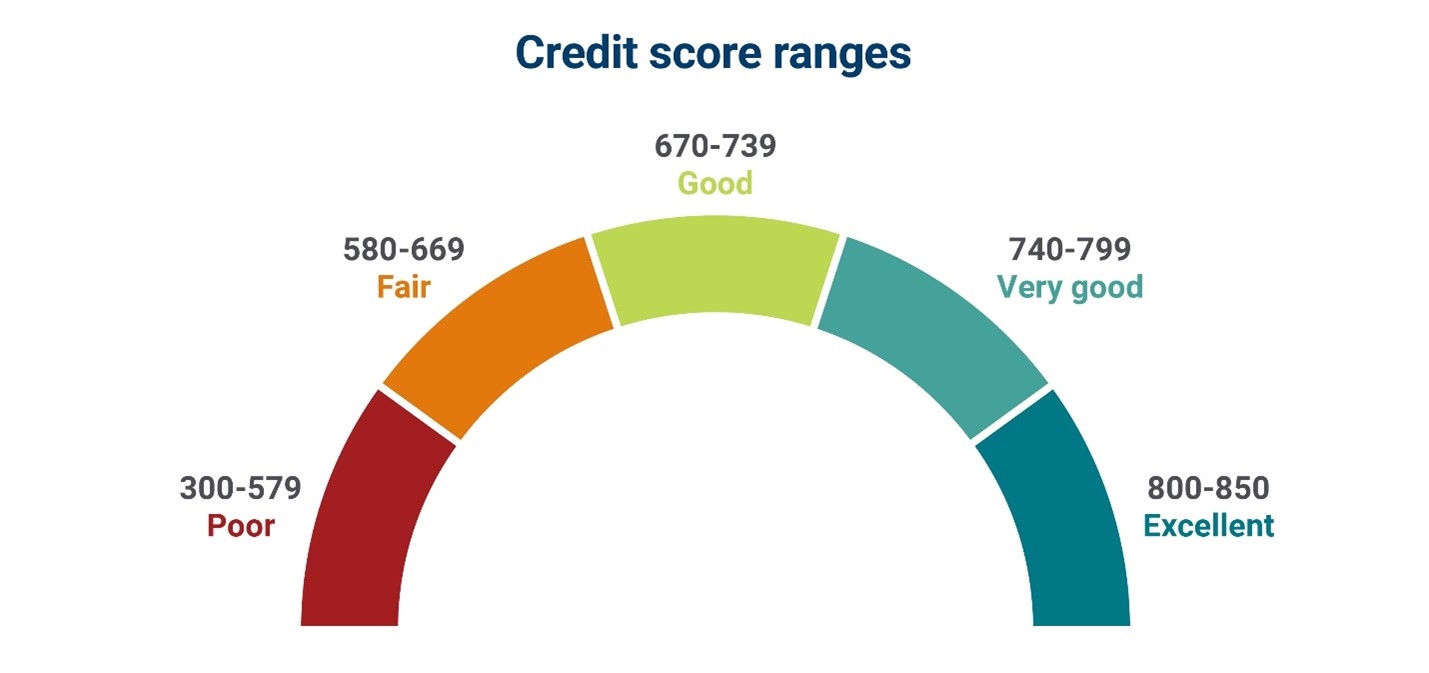
Most people have never heard of Tiger Score, which is probably the point. It's a credit scoring model used by a handful of regional lenders and credit unions, mostly in the Southeast and Midwest. It's not FICO. It's not VantageScore. It's its own thing, built on a different set of variables, and it matters if you're shopping for an auto loan, a personal loan, or trying to get approved at a credit union that doesn't report to all three major bureaus. The model weighs payment history heavily, but it also factors in credit utilization, length of credit history, types of credit in play, and recent hard inquiries. The twist is that it gives slightly more weight to revolving credit utilization than FICO does. If you're carrying high balances on cards, your Tiger Score will take a harder hit than your FICO would. Conversely, if you've got a thin file but you pay on time, Tiger Score tends to be more forgiving than the big two.Tiger Score Unleashed The Definitive Guide To Understanding Improving And Leveraging Your Personal Credit Rating
I ran into this head-on about three years ago when a member of my credit union network was turned down for a home equity line despite having a mid-700s FICO. The branch manager ran the numbers and said the Tiger Score was sitting at 612. Two different models, completely different outcomes. That kind of gap doesn't happen every day, but it's not rare either. This is the part most guides skip because there isn't really a consumer-facing portal for it. You can't go to myFICO and pull a Tiger Score. It's not one of the three major bureau models. Here's what actually works: Ask your lender directly. If you're applying for a loan, the lender pulls your score as part of the application. You have a legal right under the Equal Credit Opportunity Act to be told what score was used and what the primary factors were. Request that in writing if the loan officer brushes it off. They're required to provide it within thirty days.
Check with credit unions and regional banks. Tiger Score is more commonly used by smaller institutions. If you bank with a regional credit union, ask them at some point whether they use Tiger Score as part of their lending decisions. Most will tell you yes or no. A few won't, and in those cases you'll just see it reflected in whether you're approved or denied. Look for it on credit monitoring services. Some third-party monitoring platforms have started including Tiger Score as an optional add-on, but coverage is spotty. Don't rely on this as your primary source. Treat any number you find on a random monitoring site as approximate at best.
What Moves the Needle
Payment history is king here, same as everywhere else. But the marginal impact of a single late payment can be steeper on Tiger Score than on FICO if that late payment pushes you into a different risk tier. I've seen a thirty-day late drop someone's Tiger Score by forty points in a single month. On FICO, the same delinquency might have cost thirty to thirty-five. Credit utilization matters more than usual. Tiger Score seems to penalize utilization above 30 percent harder than FICO does. If you're carrying balances above that threshold across your cards, paying them down to under 10 percent before you apply for credit can make a noticeable difference. I had a client who knocked her utilization from 47 percent to 8 percent between applying for two different loans, and the second approval came with a significantly better rate. Her FICO barely moved. Her Tiger Score jumped about twenty-two points. The length of credit history factor is present but less punishing. Tiger Score doesn't penalize a short credit history as aggressively as some other models, which is actually one reason younger borrowers with thin files sometimes score decently here. It's not a get-out-of-jail-free card, but it's more forgiving than the alternative.
Get the Full Details
What Doesn't Help
Opening a bunch of new credit lines right before applying will hurt you. Hard inquiries land on your report and Tiger Score factors them in. Each inquiry typically costs a few points, and they accumulate. Closing old cards also hurts more than you'd expect on this model because it raises your overall utilization ratio. I've watched people close an old card to simplify their finances, then get flagged on a loan application because their utilization spiked past 50 percent. Checking your own score regularly won't move it one way or the other. Soft inquiries don't affect Tiger Score or any other model. Don't obsess over the number itself. Obsess over the behaviors that change it.
The Workaround I Use
When I'm working with someone who needs to maximize their Tiger Score for an upcoming application, I do three things in order. First, I pull their full credit reports from all three bureaus and identify any late payments that are less than two years old. Those are the biggest drag. Second, I calculate their aggregate utilization and aim for under 10 percent across all revolving accounts. Third, I check whether they have any derogatory marks like collections or charge-offs that might be dragging the score down disproportionately. Tiger Score treats derogatories harshly, and removing them through dispute or negotiation can yield the fastest improvement. The dispute process is where most people get stuck. Tiger Score uses data from Experian primarily, so disputes filed through Experian tend to move faster on this model. If you're disputing an error, route it through Experian's online portal rather than mailing a letter. Mail disputes can take sixty to ninety days to process. The online submission usually comes back in twenty to thirty.
When Tiger Score Won't Save You
It's important to be honest about the limits. Tiger Score doesn't help if you've had a foreclosure, bankruptcy, or multiple serious derogatories in the past seven years. No scoring model will rescue that profile quickly. The best you can do is rebuild slowly and let time do the work. It also won't help if your income is insufficient for the loan amount you're requesting. Tiger Score is a creditworthiness metric, not an affordability metric. A lender will still look at your debt-to-income ratio separately. A high Tiger Score with a forty-five percent DTI won't get you approved for a mortgage that requires a maximum DTI of thirty-six percent. Some lenders use Tiger Score as a tie-breaker rather than a primary filter. In those cases, your FICO score and your DTI matter more. Knowing when a lender relies on Tiger Score versus a traditional model is actually more valuable than knowing your exact Tiger Score number. Call the loan officer and ask directly. They'll tell you which model they're using, or they'll be vague, in which case you can infer it from the approval criteria they share.
The Bottom Line
Tiger Score is one tool in a larger credit optimization strategy. It's not the only number that matters, and for many borrowers it's not even the most important number. But ignoring it completely is a mistake if you're working with lenders who use it. Pay your bills on time. Keep utilization under thirty percent, ideally under ten percent. Don't open new accounts right before applying. And when you get denied, ask why. The answer might point you toward a different score model than you expected, and that changes your entire approach.