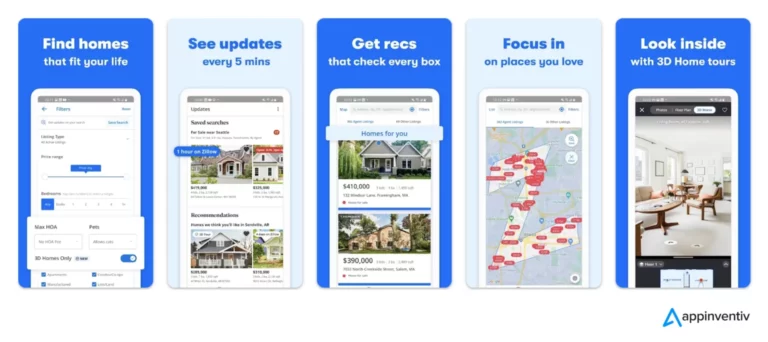
What Actually Happened When Zillow Changed Everything
Zillow launched its first major consumer-facing platform in 2006 and quietly absorbed the competitive landscape over the next two decades. What you're looking at now is the result of that consolidation. Online real estate platforms moved the primary listing database from closed MLS networks into public view, and everything downstream changed because of that single shift. Most people use Zillow the wrong way. I watch it happen constantly. Buyers walk into a seller's house convinced the Zestimate is accurate, and sellers price based on it without running their own numbers. Neither side is wrong for trusting the data—it's just not precise enough to build a transaction on.
The Zillow Revolution How Online Real Estate Platforms Are Changing The Game
Before platforms like Zillow, finding a home meant driving through neighborhoods, reading newspaper classifieds, or calling an agent who pulled listings from a shared database you couldn't access yourself. The MLS existed but was locked behind a professional credential. Zillow opened it. That alone explains why the industry looks completely different now compared to 2015. The technology underneath isn't particularly novel. Zestimate pulls from public tax records, past sale histories, and user-submitted data points, then runs a regression model against comparable sales in the area. It's fundamentally a weighted averaging algorithm with location adjustments. The accuracy varies wildly by market density. In a suburban neighborhood where every house on the block sold within six months of each other, the estimate is usually within five percent. In a rural area with one sale per year, the margin of error expands to twenty percent or more. I learned that the hard way when a client in rural Tennessee was shocked to see a Zestimate $40,000 above the nearest comparable sale from eighteen months prior. The algorithm had no recent data to anchor to. Here's what the average user doesn't understand about the platform: Zillow and Trulia merged in 2015, and the combined entity controls the largest fraction of consumer real estate traffic in the United States. Over sixty percent of home buyers start their search on a platform like this, according to National Association of Realtors surveys from the last few years. That traffic monopoly is what gives these platforms their pricing power and their ability to flip from a listing aggregator into a direct transactions business.
The iBuying program Zillow launched in 2018 is the clearest example of that evolution. They were buying homes directly, rennovating them, and reselling at a markup. The program collapsed in 2021 when they took $300 million in write-downs during a single quarter. The math didn't work at scale during a rapidly rising market. They exited iBuying entirely and pivoted toward an agent-matching and transaction-services model instead. That pivot is still playing out. I ran into a specific edge case last year that illustrates how these platforms actually function under the hood. A seller I was working with had her home listed at $389,000 on the local MLS. Zillow showed the same listing at $412,000. The discrepancy traced back to the fact that Zillow had pulled the square footage from the county tax record, which listed the finished basement as livable space, while the MLS appraisal had excluded it per local convention. The Zestimate baked in roughly three thousand extra square feet of living area, inflating the valuation by eight percent. The workaround was straightforward: I filed a correction through Zillow's agent portal with the MLS sheet as documentation, and they adjusted the figure within forty-eight hours. But most sellers never do that. They see the higher number and assume it's a good sign. The more important structural shift is how these platforms changed agent incentives. When buyers could browse every listing themselves, the traditional gatekeeper role of the buyer's agent became harder to justify. Platforms responded by creating "pre-approval" funnels and direct offer tools that capture lead data before an agent ever gets involved. An agent responding to a Zillow lead request gets maybe a five percent conversion rate into an actual client relationship. The platform sells that interaction as if it were a qualified appointment.
Get the Full Details
Another detail most people miss: the "made you a reasonable offer" feature on Zillow uses a proprietary valuation that doesn't map cleanly to any public metric. It's designed to generate engagement, not accuracy. I've seen offers flagged as "reasonable" at prices twenty percent below the actual comparable sales range in the same subdivision. The feature exists to make users feel like they're getting insider information. They're not. What actually works if you're trying to use these platforms effectively comes down to a simple sequence. Pull the Zestimate or Redfin estimate for a rough baseline. Then go to the county assessor's website and verify the recorded square footage, lot size, and tax assessment. Cross-reference the sale price of any comparable properties listed on the platform against the actual closing data from the county recorder's office. Public records are free and always more accurate than what the platform displays. Zillow doesn't update from county records in real time—there's often a three-to-six-month lag on sale data. For sellers, the biggest mistake is using the platform's estimate as a pricing anchor. I had a seller in Colorado Springs refuse to lower her price after forty-five days on market because the Zestimate hadn't moved. It stayed at $465,000 while the actual sold comps in her subdivision dropped from $430,000 to $410,000 over the same period. She was competing against newer inventory priced correctly, and her stale listing became a red flag to every buyer's agent looking at her house. The platform had no idea the market was moving because its data was twelve days old and its estimate was still anchored to the earlier higher sales.
The platform-based search model also changed what neighborhoods attract attention. Areas that were previously overlooked because they didn't appear in an agent's mental map of "good schools" and "nice streets" now get ranked by algorithm based on price-per-square-foot trends and click-through velocity. I've watched entire zip codes heat up because a platform's filter logic started surfacing them as "value picks" to buyers searching from distant cities. That feedback loop is real and it moves prices faster than local supply can adjust. If you're looking for a practical resource, Zillow's own research center publishes quarterly market reports that are more useful than the individual home estimates. The data is aggregated and sanitized, but it reflects actual transaction volume and price changes at the metro level. Redfin publishes similar reports with slightly different methodology. Both are freely accessible on their respective websites. Neither requires an account. The honest limitation of these platforms is that they optimize for breadth, not depth. They serve every market simultaneously with the same algorithm. A local agent who knows that the drainage issue on a specific street causes basement moisture problems every spring will price and market accordingly. The platform has no way to know that. It sees a square footage adjustment and a sale price. It doesn't see the foundation crack, the updated HVAC system that wasn't permitted, or the neighbor who recently filed a boundary dispute. Those details still matter at the transaction level.
What's coming next is harder to predict with confidence. Zillow's current trajectory points toward becoming a full transaction platform—title, escrow, lending, and closing services bundled behind the listing interface. They already own an mortgage originator and a title company. Whether that model sustains at scale is an open question. The iBuying failure proved that vertical integration into the physical transaction carries significant risk when market conditions shift unexpectedly. But the data advantage of sitting between the listing and the closing is real, and competitors are moving in the same direction. For now, the practical takeaway is that these platforms are excellent for initial discovery and rough benchmarking, terrible for pricing decisions, and deliberately designed to convert casual browsers into captured leads. The technology that built them isn't going away. The way people use it is still adjusting to what it actually is.