Why Most People Get House Number Staring At Them Wrong
When you buy a home, the sticker price is never what matters. What matters is the actual monthly cash flow after you factor in taxes, insurance, HOA dues, maintenance reserves, and the way interest compounds over thirty years. The Zillow Calculator Advantage How To Master Your Home Finance Decisions really comes down to understanding that a single screen of numbers can mask real problems if you don't push past the default assumptions. I ran into this last year when a client was comparing two properties in Columbus, Ohio. One listed at $385,000 and the other at $410,000. The first looked cheaper until the calculator pulled property tax data from Franklin County, which had just reassessed the neighborhood. The $385,000 house turned out to carry a $6,200 annual tax bill because it sat in a flood zone overlay. The $410,000 house had $3,800 in taxes. You would never see that difference on the listing page. The calculator exposes it, but only if you let it.
Setting Up The Zillow Calculator Advantage How To Master Your Home Finance Decisions
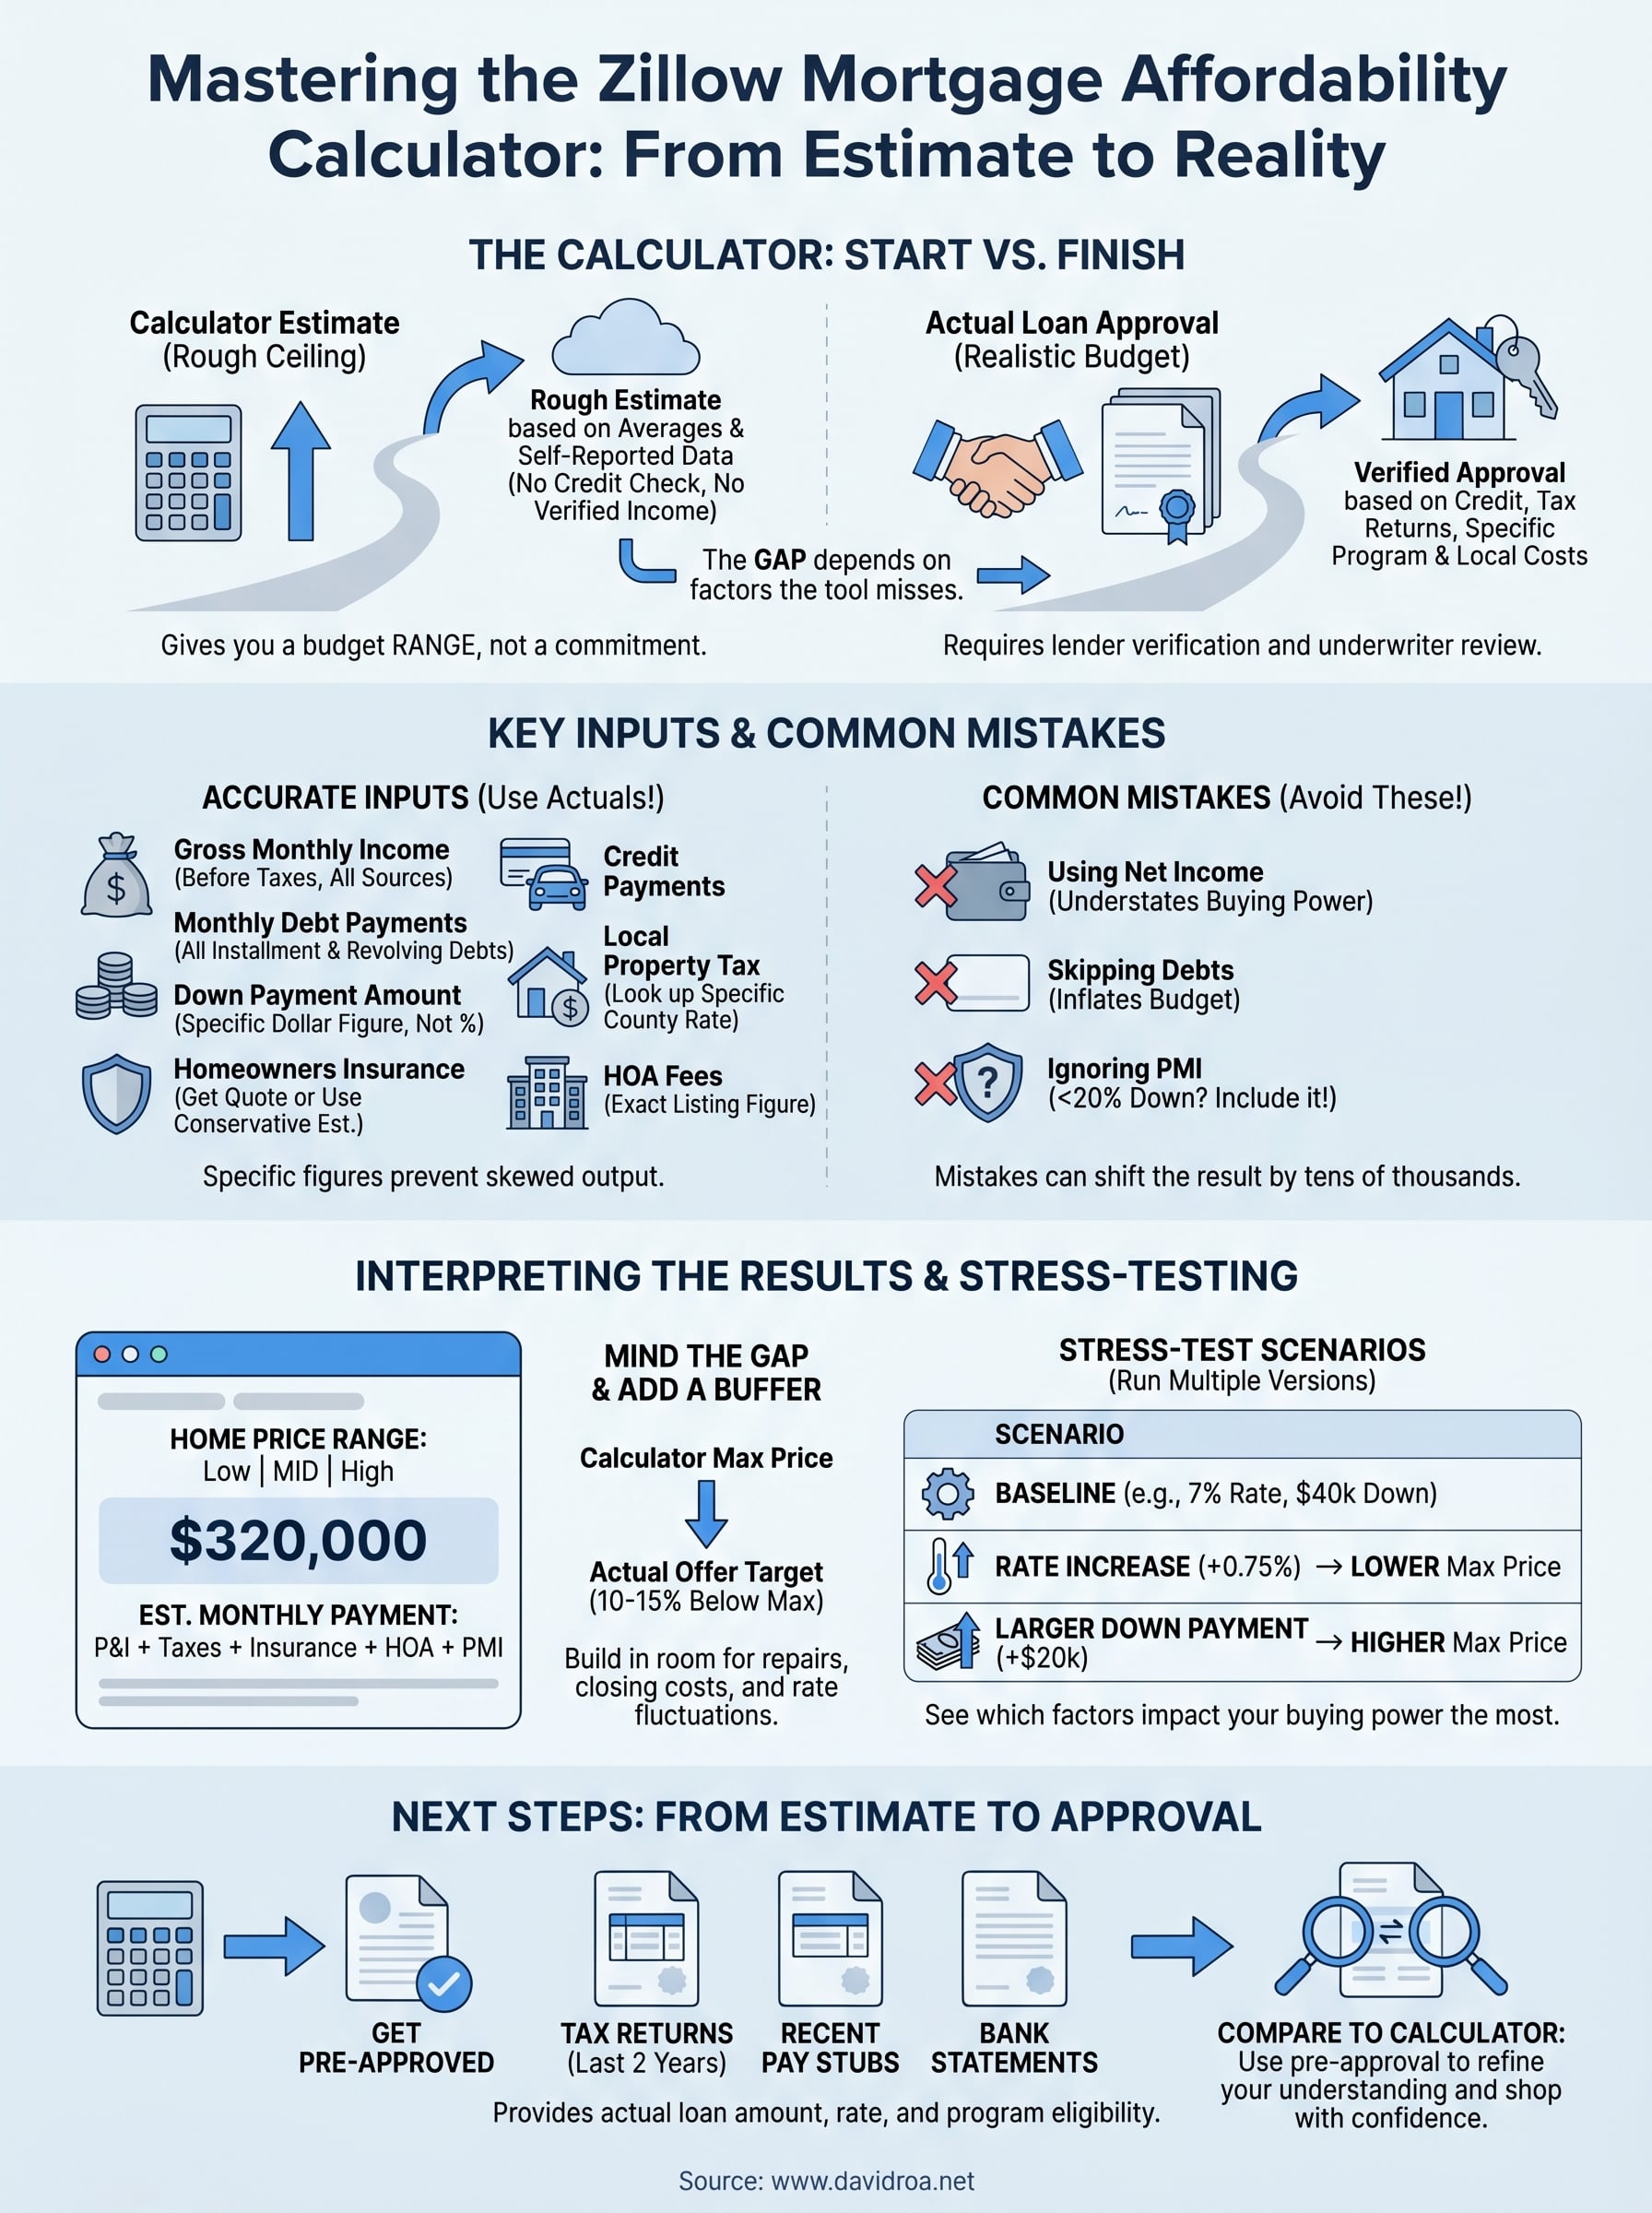
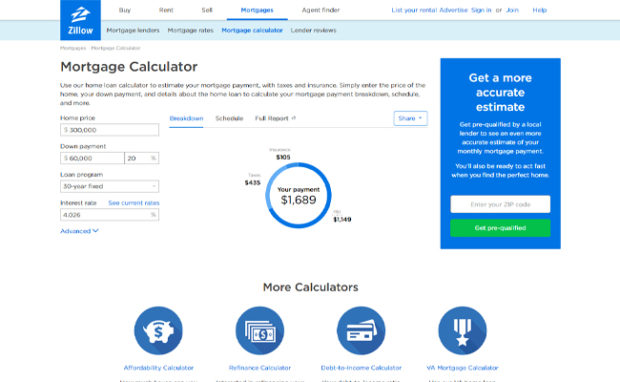
The first step is getting into the right section of the site. You type the address or paste a link, scroll past the photos and the agent blurb, and find the Mortgage Calculator widget. It usually sits near the bottom of the property page. Click it. You will see fields for purchase price, down payment, interest rate, loan term, property tax, home insurance, and HOA fees. By default, every one of those fields is pre-filled with something, and most of those somethings are wrong or outdated. Do not trust the auto-filled numbers. The site pulls them from public records, assessor data, and its own Zestimate algorithm. Public records lag. Assessor data is only as good as the last appraisal cycle, which might be three to five years old. The Zestimate is a statistical guess, not a licensed valuation. Your first move should be to open the county assessor's website for the county where the property sits and verify the most recent tax assessment. Then go to the insurance provider for that ZIP code and get a real quote, not a generic estimate. HOA fees come from the listing or the association documents. Once you have actual numbers, enter them manually. The interest rate field is where people lose sleep. The rate shown on the calculator is not your rate. It is a national average for conforming 30-year fixed loans, which at the time of this writing hovers somewhere between 6 and 7 percent depending on the week. Your actual rate depends on credit score, debt-to-income ratio, loan type, points you buy, and the lender. Call three lenders. Get written Loan Estimates. Enter the rate from the estimate that matches your situation. If you plan to buy discount points, adjust the rate in the calculator to reflect the post-point rate so the monthly payment tells the truth.
What The Calculator Actually Shows You
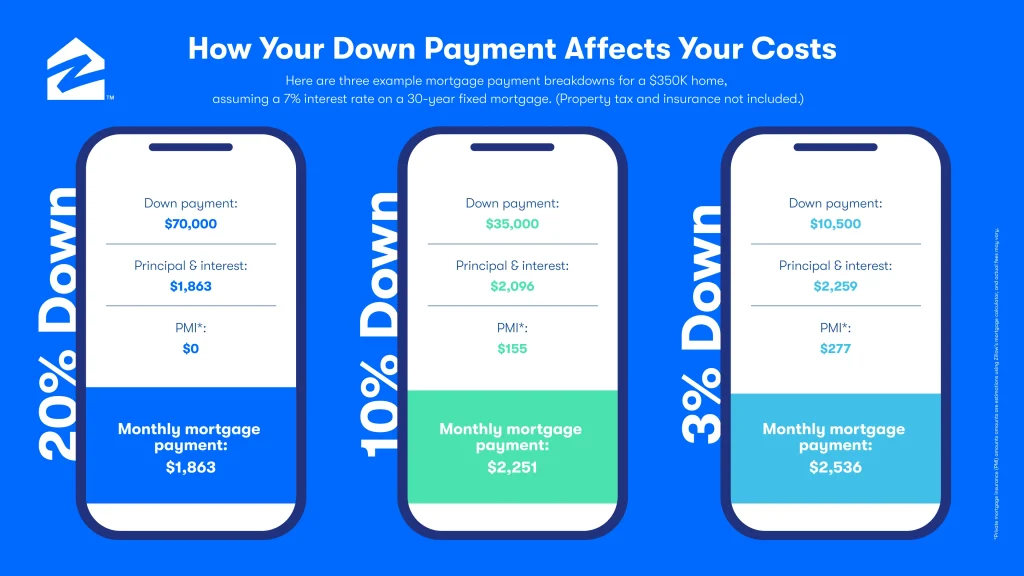
After you fill in the correct numbers, the tool outputs a monthly payment broken into principal and interest, property tax, homeowner's insurance, HOA dues, and sometimes PMI. That breakdown is useful because it forces you to look at every component that drains your bank account each month. A lot of buyers only look at the principal and interest number and assume that is the total housing cost. It is not. The real total is often 40 to 60 percent higher than the mortgage-only figure. The calculator also gives you an amortization schedule if you dig into it. That schedule shows how much of each payment goes toward interest versus principal in every single month. In year one of a 30-year loan at 6.5 percent, roughly 78 percent of your payment is interest. By year five, that ratio shifts but interest still dominates. This is not dramatic, it is just arithmetic. Understanding it early prevents the mistake of assuming you are building equity fast. You are not. Not until the middle of the loan term does principal start outpacing interest in any meaningful way. There is a useful trick most people skip. The calculator lets you run a side-by-side comparison if you open two property pages in separate tabs and keep the calculator widget open on both. Run the numbers for both properties with identical down payment and loan terms. The difference in monthly payment between the two tells you exactly what you are paying for the extra bedroom or the newer roof. Sometimes the delta is only $40 a month. Sometimes it is $400. Either way, the number is clearer than anything an agent will tell you in a walk-through.
Get the Full Details

The Part Nobody Talks About
Maintenance reserve. The Zillow calculator does not include it. It never will. But skipping it is how people buy houses and then realize they cannot afford the water heater that dies six months later. The standard rule of thumb is one percent of the home's purchase price per year. On a $400,000 house, that is $4,000 annually, or about $333 monthly. I learned this the hard way when a client bought a 1978 split-level in suburban Detroit. The calculator showed a clean $2,100 monthly payment. The house needed a new HVAC system in month fourteen. That was an $8,400 bill. The one-percent rule would have built a cushion that absorbed the hit without touching savings. Enter that number yourself in a separate column, even if you have to add it to a spreadsheet outside the calculator. Another thing that trips people up is the difference between what the calculator says you can afford and what the underwriter actually approves. The calculator runs a back-end debt-to-income ratio based on your stated income and debts. Underwriters use verifiable income, recent pay stubs, W-2s, and sometimes tax returns. If you are self-employed, the gap between the calculator's number and the underwriter's number can be thousands per month. Do not treat the calculator as a pre-approval. It is a planning tool. Use it to narrow your search range, not to lock into a purchase.
The Zillow Calculator Advantage How To Master Your Home Finance Decisions
The advantage exists, but it has hard limits. The data sources are public and stale. The interest rate is generic. Maintenance is invisible. PMI gets calculated using a default threshold that may not match your lender's actual requirement, which can be 80 percent or lower depending on the program. Some state and local taxes are not captured at all. If you live in a homestead-exemption state like Texas or Florida, the calculator will show you the full assessed value unless you manually reduce it by the exemption amount. That adjustment can change your monthly tax by hundreds of dollars. I had a case in Houston where the auto-fill showed $1,800 a year in taxes. The homeowner had a standard homestead exemption that knocked it down to $1,200. The calculator was off by exactly $200 a month until someone corrected the field. If you need precision, the calculator is a starting point, not a final answer. Pair it with a real Loan Estimate from a lender and a property tax verification from the county. Then run your own spreadsheet with the maintenance reserve added. The combination of all three sources gives you a picture that is close enough to reality to make a decision without risking financial regret. The tool is free, it loads fast, and it covers the basics. Use it before you walk into a real estate office. It will save you from falling in love with a house whose true carrying cost you never understood.