The Yen At 800: What Actually Happened And Why It Matters
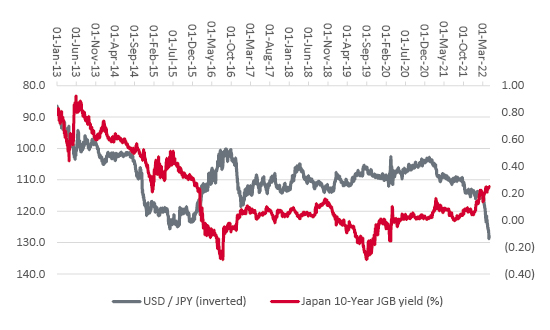
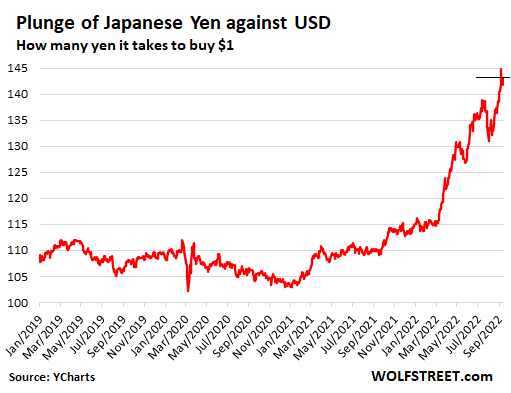
I was at a dinner in Tokyo last November when a colleague mentioned his company had just started invoicing in dollars instead of yen for their European contracts. Not because they wanted to hedge. Because nobody in Tokyo trusted the yen to hold its value past the next earnings call. That conversation stuck with me more than any chart ever could. When the yen broke through 800 against the dollar, most people treated it like a curiosity. Tourists cheering cheaper trips. Forex bros posting screenshots. Nobody really stopped to consider what structural damage had to occur for a currency that had spent decades in the 100 to 120 range to suddenly become this unmoored. Here is the mechanism. Japan ran yield curve control for years. The Bank of Japan kept short-term rates at negative territory while letting the long end drift slightly higher. This created a massive interest rate differential with the United States, where the Federal Reserve was pushing rates into restrictive territory. When you have a 4 to 5 percent gap between what American bonds pay and what Japanese bonds pay, capital leaves Japan. It does not stay. This is basic portfolio mathematics.
But the yield differential alone does not explain the speed of the decline. The real acceleration happened because Japan runs a structural current account surplus that has been slowly eroding. Energy imports after Fukushima forced the country to import nearly all of its petroleum at spot prices while domestic demand stayed flat. A weaker yen should theoretically help exporters, and it does, but the math stopped working at a certain threshold. When the yen hits 800, the cost of every imported energy shipment becomes unbearable for companies that cannot pass those costs onto consumers who are already struggling with stagnant wages. I ran into this problem directly when a client asked me to model hedging strategies for a mid-tier manufacturing firm that sourced raw materials from Southeast Asia but sold finished goods domestically. Their natural hedge had completely collapsed at 800. I built a scenario analysis showing that even a 60 percent forward cover position would burn through their net margin within two quarters. The workaround was restructuring their supply chain contracts to include yen denomination clauses with quarterly adjustment mechanisms tied to the BOJ policy rate. It added administrative overhead but preserved their gross margin at levels that kept the P&L readable. Most smaller firms never figure this out and just absorb the losses until they quietly exit the market.
Why The Boomers Were Wrong About This
For thirty years, every time the yen weakened significantly, Japanese policymakers assumed it would reverse. The conventional wisdom was that the Bank of Japan would eventually intervene or raise rates and the currency would grind back. That assumption died somewhere around 750. The structural factors that supported the old range are gone. Japan's population is shrinking. Domestic consumption is flat to declining. The trade balance has turned inconsistent. These are not cyclical problems you wait out. The counter-intuitive part that most commentators miss is that a weaker yen is actually making Japan's debt problem worse, not better. Japan carries over 250 percent of GDP in public debt, almost entirely denominated in yen and held domestically. When the currency weakens, inflation rises, and the BOJ faces pressure to normalize policy. But normalizing policy on that debt load would trigger immediate fiscal crisis. So they are trapped. They can let the yen float lower and accept inflation, or they can try to prop it up and risk breaking the government bond market. Neither option produces a good outcome. Another nuance people overlook: the yen carry trade has been the backbone of global macro strategy for decades. Hedge funds borrow cheap yen, convert to dollars, and buy American assets. When the yen weakens this trade becomes more profitable and attracts more capital, which pushes the yen even lower. The feedback loop is self-reinforcing until someone loses money and unwinds it simultaneously. That unwinding can happen fast. I watched a similar dynamic play out with the Swiss franc in 2015. The markets looked calm right up until they did not. The yen situation is structurally more dangerous because Japan's central bank has far less credibility and far more domestic constraint than the SNB ever did.
Get the Full Details
What This Means In Practice
If you are a business operator in Japan dealing with this environment, the practical reality is that your financial planning horizon has compressed dramatically. Three-year forecasts are basically fiction now. I recommend building scenario models around three exchange rate bands: 750 to 800, 800 to 850, and above 850. Each band requires a completely different operational posture. The 750 to 800 range still allows for some hedging discipline. Past 850 you are in damage control mode and should be prioritizing pricing power and supply chain relocation over financial instruments. For individual travelers or expats, the asymmetry works against you. Yes, your dollar goes further in Tokyo. But if you earn in yen and spend in yen, which is most people here, the currency move is pure negative. Rent, utilities, groceries, everything priced domestically has absorbed some of the inflation pressure. The purchasing power erosion is real even if the exchange rate number looks glamorous on a conversion app. The BOJ has signaled they may allow rates to rise above zero. When they actually do it, the yen will likely strengthen briefly on the policy shift. But without a credible growth narrative behind it, that strengthening will be short-lived. Markets price in future growth expectations, and Japan currently has none to offer that are convincing. The demographic math is simply unforgiving.
I do not know where the yen settles long term. I do not know if it reverses to 110 or drifts to 900. What I do know from watching this unfold in real time is that the old frameworks for understanding Japanese currency strength no longer apply. The assumptions that kept the yen in a tight range for decades were built on growth expectations, capital controls that never existed but functioned anyway, and a global financial system that rewarded stability. None of those conditions obtain today. The 800 level is not an anomaly. It is a rational repricing of an economy that has been running on borrowed time for twenty years.