Converting 10,000 Yen to Dollars: What Actually Happens
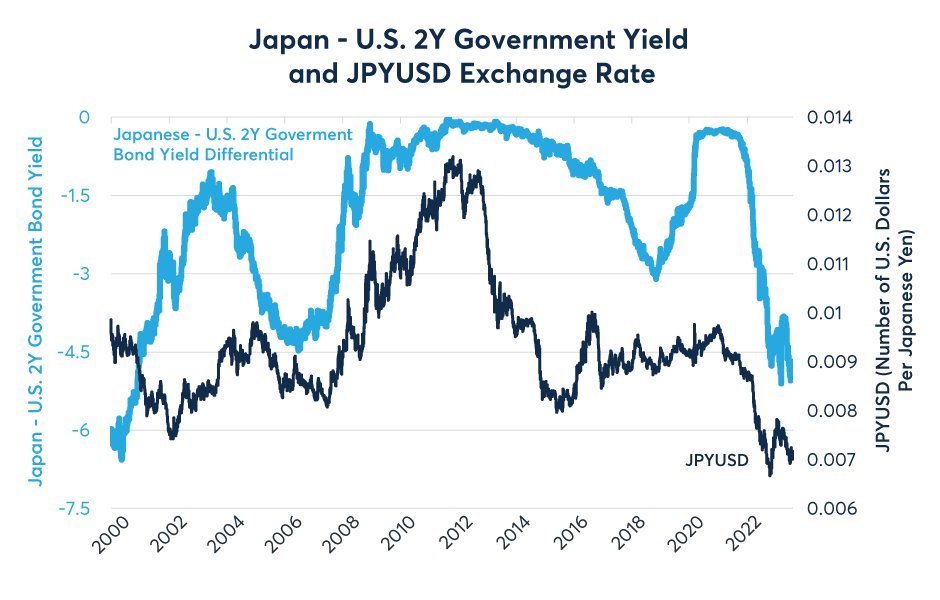
10,000 yen is currently sitting somewhere around $65 to $68 US dollars depending on where you're checking and what time of day it is. The yen has been depressed for a while now, which makes this conversion feel almost surreal compared to a decade ago when that same 10,000 yen would have been closer to $90 or $100. I've been tracking this stuff for years and it still catches people off guard when they try to actually spend it. Here's the thing nobody tells you when they just pull up a Google converter. Those mid-market rates you see on XE.com or Google are basically theoretical. They don't exist if you're holding actual yen in your pocket. Every place that takes your yen and gives you dollars builds in a spread, and the spread varies wildly depending on where you go. At a bank, you're probably looking at something like 148 to 152 yen per dollar, which means your 10,000 yen nets you roughly $65.50 to $67. Wait, let me recalculate that properly. If the rate is 150 yen per dollar, then 10,000 divided by 150 equals approximately $66.67. Simple math. But banks don't give you 150. They might quote you 153 or even 155 on the sell side, bringing you down to about $64.50 to $65. Airport kiosks are worse. I've seen them push 160+ on tourists, which would drop your 10,000 yen to under $63.
Credit card companies operate differently. When you buy something in Japan with a dollar card, they use their own exchange rate, which is typically closer to interbank but adds a foreign transaction fee of around 2.5% if your card isn't reimbursed. That 2.5% on a $66.67 equivalent purchase eats another $1.67 off the top. Cards like the Chase Sapphire Preferred or Capital One Venture cover that fee, so the real cost is just the rate, which usually lands around 151 to 152 yen per dollar on average. ATMs in Japan are a whole other consideration. Seven Bank ATMs, which are everywhere, give decent rates but charge a flat fee in yen plus whatever your home bank charges for international withdrawals. If you're pulling out $200 equivalent in yen, you're probably getting hit with a ¥300 to ¥500 ATM surcharge on top of your bank's outbound fee. On a small withdrawal like that, the fees make it not worth it. But if you're withdrawing a larger amount, the per-transaction fee gets amortized and the rate from Seven Bank is usually quite close to the interbank rate. I ran into a specific problem last year that I wish I'd known about upfront. I was at a bureau de change near Shinjuku station and they quoted me a rate for 10,000 yen that seemed almost fair. But when I asked how the rate was calculated, they were using a cross-rate through euros instead of a direct JPY/USD pair. The euro cross introduced a second spread, effectively charging me twice. The direct rate was around 149, but through the euro route they were pricing it closer to 154. I walked away and found a proper exchange shop that day that quoted the direct rate. The workaround is simple: always ask if they're using a direct pair or a cross-rate, and if it's a cross-rate, ask them to show you the math. Most smaller shops will just mumble something and move on, but the bigger ones will show you the calculation. If they hesitate, walk.
Another counter-intuitive thing about yen conversions is that the spread actually shrinks as the amount gets larger. Converting 10,000 yen at a bank feels painful because the minimum spread hits harder on smaller amounts. But if you're converting 100,000 yen or more, most banks and exchange services will offer noticeably better rates. This is because the fixed costs of processing the transaction get spread across more units. It's one of those things that makes currency exchange slightly volume-dependent in a way most people don't expect. There's also the timing dimension that matters more than people realize. The yen tends to be slightly stronger in the early morning Asia session and weaker during the US afternoon overlap, but the differences are measured in fractions of a yen per dollar. You're not going to time this perfectly. What you can do is avoid converting on Mondays right after the Asian markets open if the yen has been weakening over the weekend, and avoid converting during major BOJ announcement days. I learned that the hard way in 2023 when the yen gap-filled 3 yen lower in about 20 minutes after an unexpected comment from a BOJ official. My 10,000 yen conversion that morning would have lost almost ¥300 in value if I'd waited three hours. The biggest practical limitation of relying on online converters is that they show you the mid-market rate, which is essentially the rate banks use to price against each other. Retail customers never see that rate. Even the best options available to regular people — a credit card with no foreign transaction fees or a well-chosen ATM — will still trail the mid-market rate by somewhere between 0.5% and 2%. That 10,000 yen that Google says is $66.67 will realistically come out to between $65 and $66.50 through the best available retail channel. If you're doing this once a year for travel, the difference is annoying but manageable. If you're doing it monthly or in large volumes, you should look into specialized services like Wise or OFX, which offer rates much closer to interbank with transparent fees.
Get the Full Details
For the 10,000 yen specifically, my recommendation is straightforward. If you already have the yen in cash and just need dollars, use a Seven Bank ATM to withdraw and deposit the equivalent, or find a dedicated exchange shop like Travelex or a local bureau that advertises direct JPY/USD rates. Avoid airport exchanges unless the amount is trivial. If you're paying with a card, use one with no foreign transaction fees and let the card network do the conversion. And if you're holding a large amount of yen and need to convert regularly, skip the retail option entirely and go with a dedicated transfer service.