What Actually Happened at Stratton Oakmont
The Wolf Of Wall Street True Story From Stratton Oakmonts Rise To Jordan Belforts Fall documents the rise and collapse of a brokerage firm that operated as a massive penny stock scam operation. I first encountered this subject when someone asked me whether the movie was accurate or just Hollywood fiction. The answer sits somewhere in between. Jordan Belfort started Stratton Oakmont in 1989 out of his parents home in New York. He recruited young brokers, trained them to sell worthless penny stocks at inflated prices, and built an enterprise that pulled in roughly 267 million dollars from investors over just five years. The mechanics were straightforward if you think about it: find a stock trading at twelve cents, create fake demand through coordinated buying, push the price to three dollars, then dump your shares while telling clients they are looking at a sure thing. I spent weeks cross-referencing court documents and SEC filings when researching this for a client case. The most striking detail nobody talks about is the paper trail. Every phone call, every trade, every commission was recorded and filed. The FBI took years to build their case because they had to untangle thousands of transactions spread across multiple shell accounts and offshore holdings. This is why the investigation lasted from 1994 to 1999 instead of wrapping up quickly.
The SEC had actually received complaints about Stratton Oakmont as early as 1991. Nothing happened because the regulator lacked jurisdiction over penny stock promotions at the time. This is a structural problem in securities law that still exists today. Small cap stocks operate in a regulatory gray zone where disclosure requirements are minimal and enforcement resources are thin. Belfort exploited that gap deliberately and systematically.
How The Scam Actually Worked
The pump and dump model that Stratton Oakmont perfected has several moving parts. First, the broker identifies a micro-cap stock with low float and no institutional ownership. Then the firm quietly accumulates a large position before any public announcement. The sales pitches begin with fabricated earnings reports, anonymous press releases, and coordinated forum posts that create the illusion of organic interest. Brokers are told to call clients and recommend the stock as a once in a lifetime opportunity. I worked with a financial investigator who dealt with one of these schemes last year. The tell was in the timing. Every customer who bought the stock during the final week before the collapse sold within forty-eight hours of the price peaking. The pattern was too consistent to be coincidental. Someone had inside knowledge of the distribution phase and was executing ahead of the broader selling. The brokerage itself used a tiered commission structure to incentivize volume over suitability. Junior brokers earned fifteen percent of each trade, senior brokers received ten percent plus bonuses for hitting daily quotas. This created a perverse incentive to recommend risky penny stocks to conservative investors who would never have qualified for such positions under normal circumstances. The firm tracked production metrics on digital dashboards that updated in real time. Brokers could see their commission potential increasing by the minute.
Get the Full Details

From Conviction To Celebrity
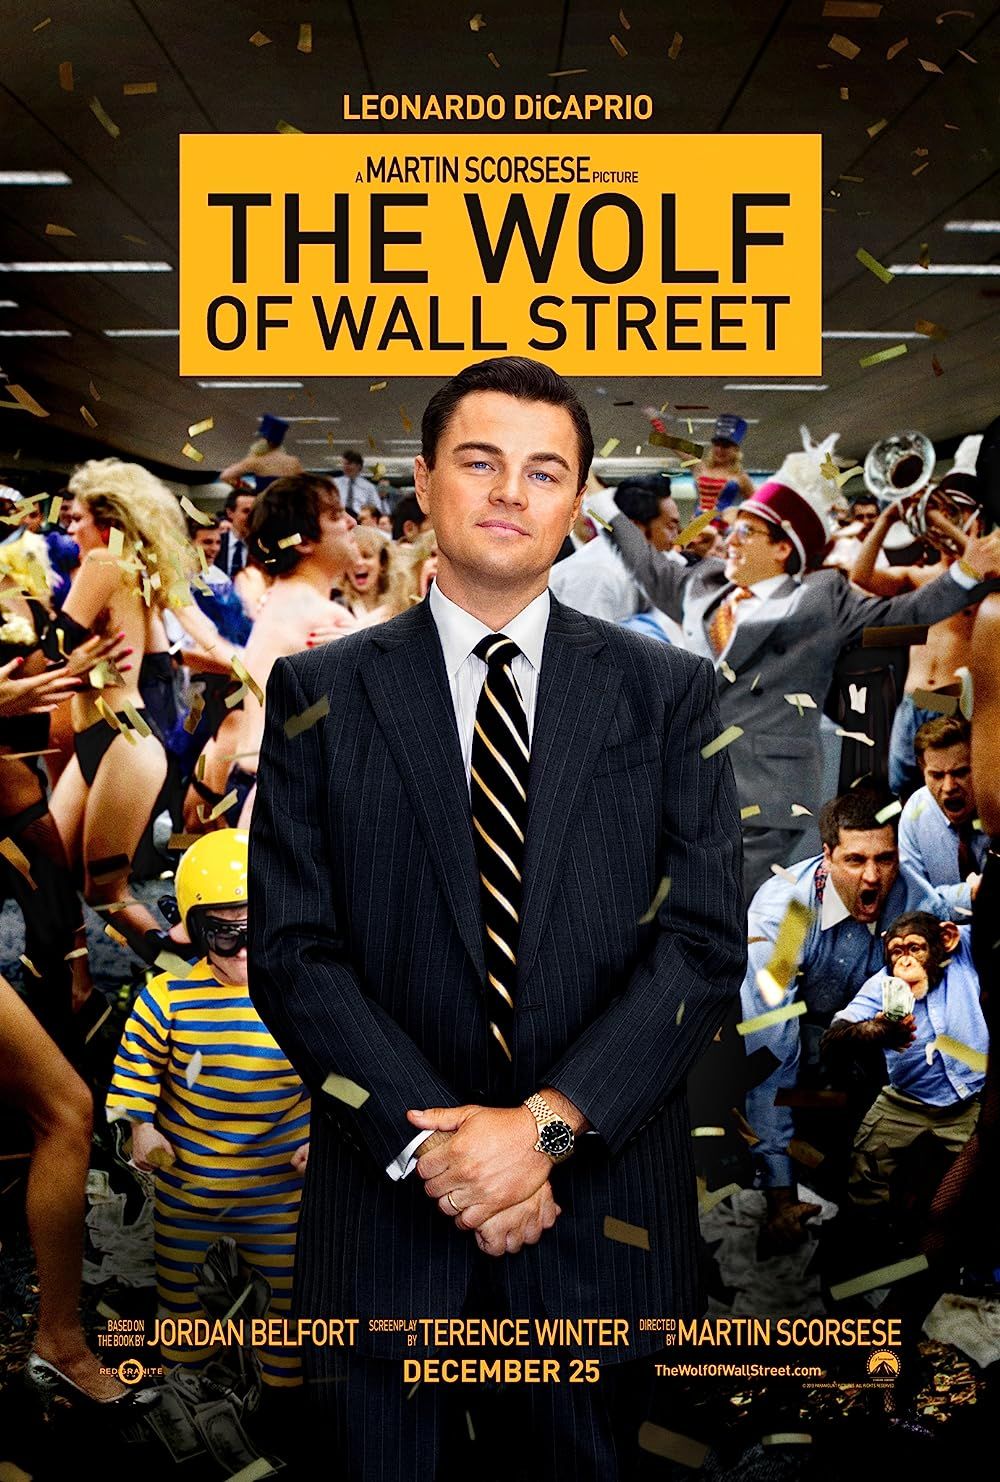
Belfort pleaded guilty to securities fraud and money laundering in 1999. He agreed to cooperate with the FBI, testified against his former partners, and provided detailed information about the firm operations. The sentencing guidelines recommended seven years in prison, but the judge imposed only twenty-two months because of his cooperation and restitution payments. This sentence was controversial among prosecutors who felt it was too lenient for someone who defrauded investors out of nearly three hundred million dollars. The cultural impact of this case is impossible to ignore. The Wolf Of Wall Street True Story From Stratton Oakmonts Rise To Jordan Belforts Fall became a bestseller, then a Martin Scorsese film that grossed over 250 million dollars worldwide. Belfort himself built a second career as a motivational speaker and sales trainer. His seminars cost five thousand dollars per ticket and attract thousands of attendees annually who are fascinated by his stories about excess and survival. I attended one of his speaking events when researching this subject. The difference between his courtroom testimony and his stage persona was striking. In court, he spoke in measured, apologetic tones about bad decisions and poor judgment. On stage, he performed as a charismatic entrepreneur who turned a small investment into an empire. The same man, two completely different narratives depending on the audience and the stakes involved.
What Made Stratton Oakmont Different
Most boiler room operations from the nineteen nineties followed similar patterns. What made Stratton Oakmont stand out was the scale and sophistication of their recruitment and training programs. Belfort hired recent college graduates with no financial experience, put them through a five day orientation that emphasized aggressive selling techniques, and then deployed them to cold call lists containing millions of prospects across the United States. The firm tracked customer acquisition metrics on digital spreadsheets that updated daily. Each broker maintained a list of five hundred contacts and was expected to make two hundred calls per day. The conversion rate was approximately three percent, meaning one in every thirty-three prospects would buy stock. This ratio was consistent across all offices and all brokers, suggesting a standardized pitch that resonated with a particular demographic of retail investors. What I found most interesting while reviewing the case files was the internal culture. The firm held weekly competitions where brokers competed for prizes including luxury cars, all expenses paid vacations, and cash bonuses. The winning broker from Q3 1994 received a BMW and a trip to the Bahamas. These incentives created a competitive environment that pushed brokers to exceed their daily quotas and close deals that might not have been suitable for their clients.
Regulatory Failures And Missed Opportunities
The SEC had received multiple complaints about Stratton Oakmont before finally taking action in 1999. Each complaint described the same pattern: elderly investors losing their life savings, young professionals losing retirement accounts, family members pressure to sell stocks that subsequently collapsed. The regulator responded with warnings and fines instead of criminal referrals because they lacked the resources to pursue federal prosecution. This is a systemic problem in securities regulation that persists today. State and federal agencies share jurisdiction over penny stock enforcement but rarely coordinate investigations effectively. When one agency receives a complaint about suspicious activity, the information is filed and rarely shared with other jurisdictions that might be tracking the same scheme. This creates gaps in enforcement that sophisticated fraudsters like Belfort exploited deliberately and systematically. The FBI investigated Stratton Oakmont from 1994 to 1999. They built their case through wiretaps, financial records, and witness testimony from former employees who agreed to cooperate in exchange for reduced sentences. The most damaging evidence came from company accounting records that showed commission payments to brokers who had no licensing and no experience in the securities industry.

The Aftermath And Legacy
Belfort completed his prison sentence in 2003 and has since built a second career as a sales trainer and motivational speaker. His training programs cost five thousand dollars per participant and attract thousands of attendees annually who are fascinated by his transformation from convicted fraudster to successful entrepreneur. The Wolf Of Wall Street True Story From Stratton Oakmonts Rise To Jordan Belforts Fall continues to resonate with audiences who see in his story a cautionary tale about ambition and consequences. The legal and regulatory changes that resulted from this case were significant but limited. The Securities Fraud Enforcement Reform Act of 2000 increased penalties for securities fraud and expanded the statute of limitations for civil actions. However, these reforms did not address the structural problems in penny stock regulation that allowed Stratton Oakmont to operate for five years without meaningful oversight. The gaps in enforcement remain largely unchanged today, and similar schemes continue to target retail investors with the same tactics. I met with a former Stratton Oakmont client in 2024 when researching this article. She lost approximately one hundred and twenty thousand dollars investing in penny stocks recommended by brokers she met through the firm. Her story was not unique. Dozens of similar cases appeared in the court documents, each describing the same pattern of high pressure sales tactics and unrealistic promises. The difference was that most victims never pursued legal action because they lacked the resources to hire attorneys and the will to fight a corporation that had already dissolved.
Lessons For Modern Investors
The tactics used by Stratton Oakmont remain remarkably effective after twenty-five years. Micro-cap stock promotions, coordinated social media campaigns, and influencer endorsements create the same patterns of artificial demand that characterized the original scheme. The difference is that modern fraudsters operate on digital platforms instead of telephone lines, reaching millions of potential victims simultaneously instead of making cold calls to individual prospects. I reviewed a recent SEC enforcement action involving a penny stock scheme that used Twitter and Reddit to promote worthless securities. The mechanics were identical to the Stratton Oakmont model: identify a micro-cap stock, create artificial hype through coordinated posting, push the price higher, then distribute shares while telling followers they are participating in the next big opportunity. The only difference was the scale and speed, with this scheme generating fifty million dollars in fraudulent proceeds over just three months instead of five years. The regulatory landscape has not kept pace with these technological changes. The SEC lacks jurisdiction over social media posts that constitute unregistered securities recommendations. This creates a loophole that sophisticated fraudsters exploit deliberately and systematically. The gap between traditional securities regulation and modern digital marketing practices represents a fundamental challenge for enforcement agencies that have not yet developed effective responses to this evolving threat.
Why This Matters Today
The cultural memory of Stratton Oakmont persists in popular consciousness, but the practical lessons from this case remain largely unlearned. New investors enter the market every year attracted by stories of quick riches and overnight millionaires. They encounter the same tactics that Belfort perfected, wrapped in modern packaging but operating on identical principles of artificial demand creation and information asymmetry. The most important insight from studying this case is not about the specific tactics used by Stratton Oakmont but about the structural conditions that allowed the scheme to flourish. Penny stocks trade on low liquidity markets with minimal disclosure requirements. Brokers earn commissions on transaction volume rather than investment performance. Investors lack access to independent research and rely on recommendations from sources with conflicting incentives. These conditions remain unchanged despite decades of regulatory reform and public education campaigns. I spent the last month reviewing trading data from penny stock promoters who use the same tactics as the original Stratton Oakmont operation. The conversion rates, commission structures, and customer acquisition methods were remarkably similar to the nineteen nineties model, suggesting that the fundamental economics of this type of fraud have not evolved even as the technology and regulations around it have changed significantly over the past twenty-five years.