Understanding What's Actually Happening Right Now
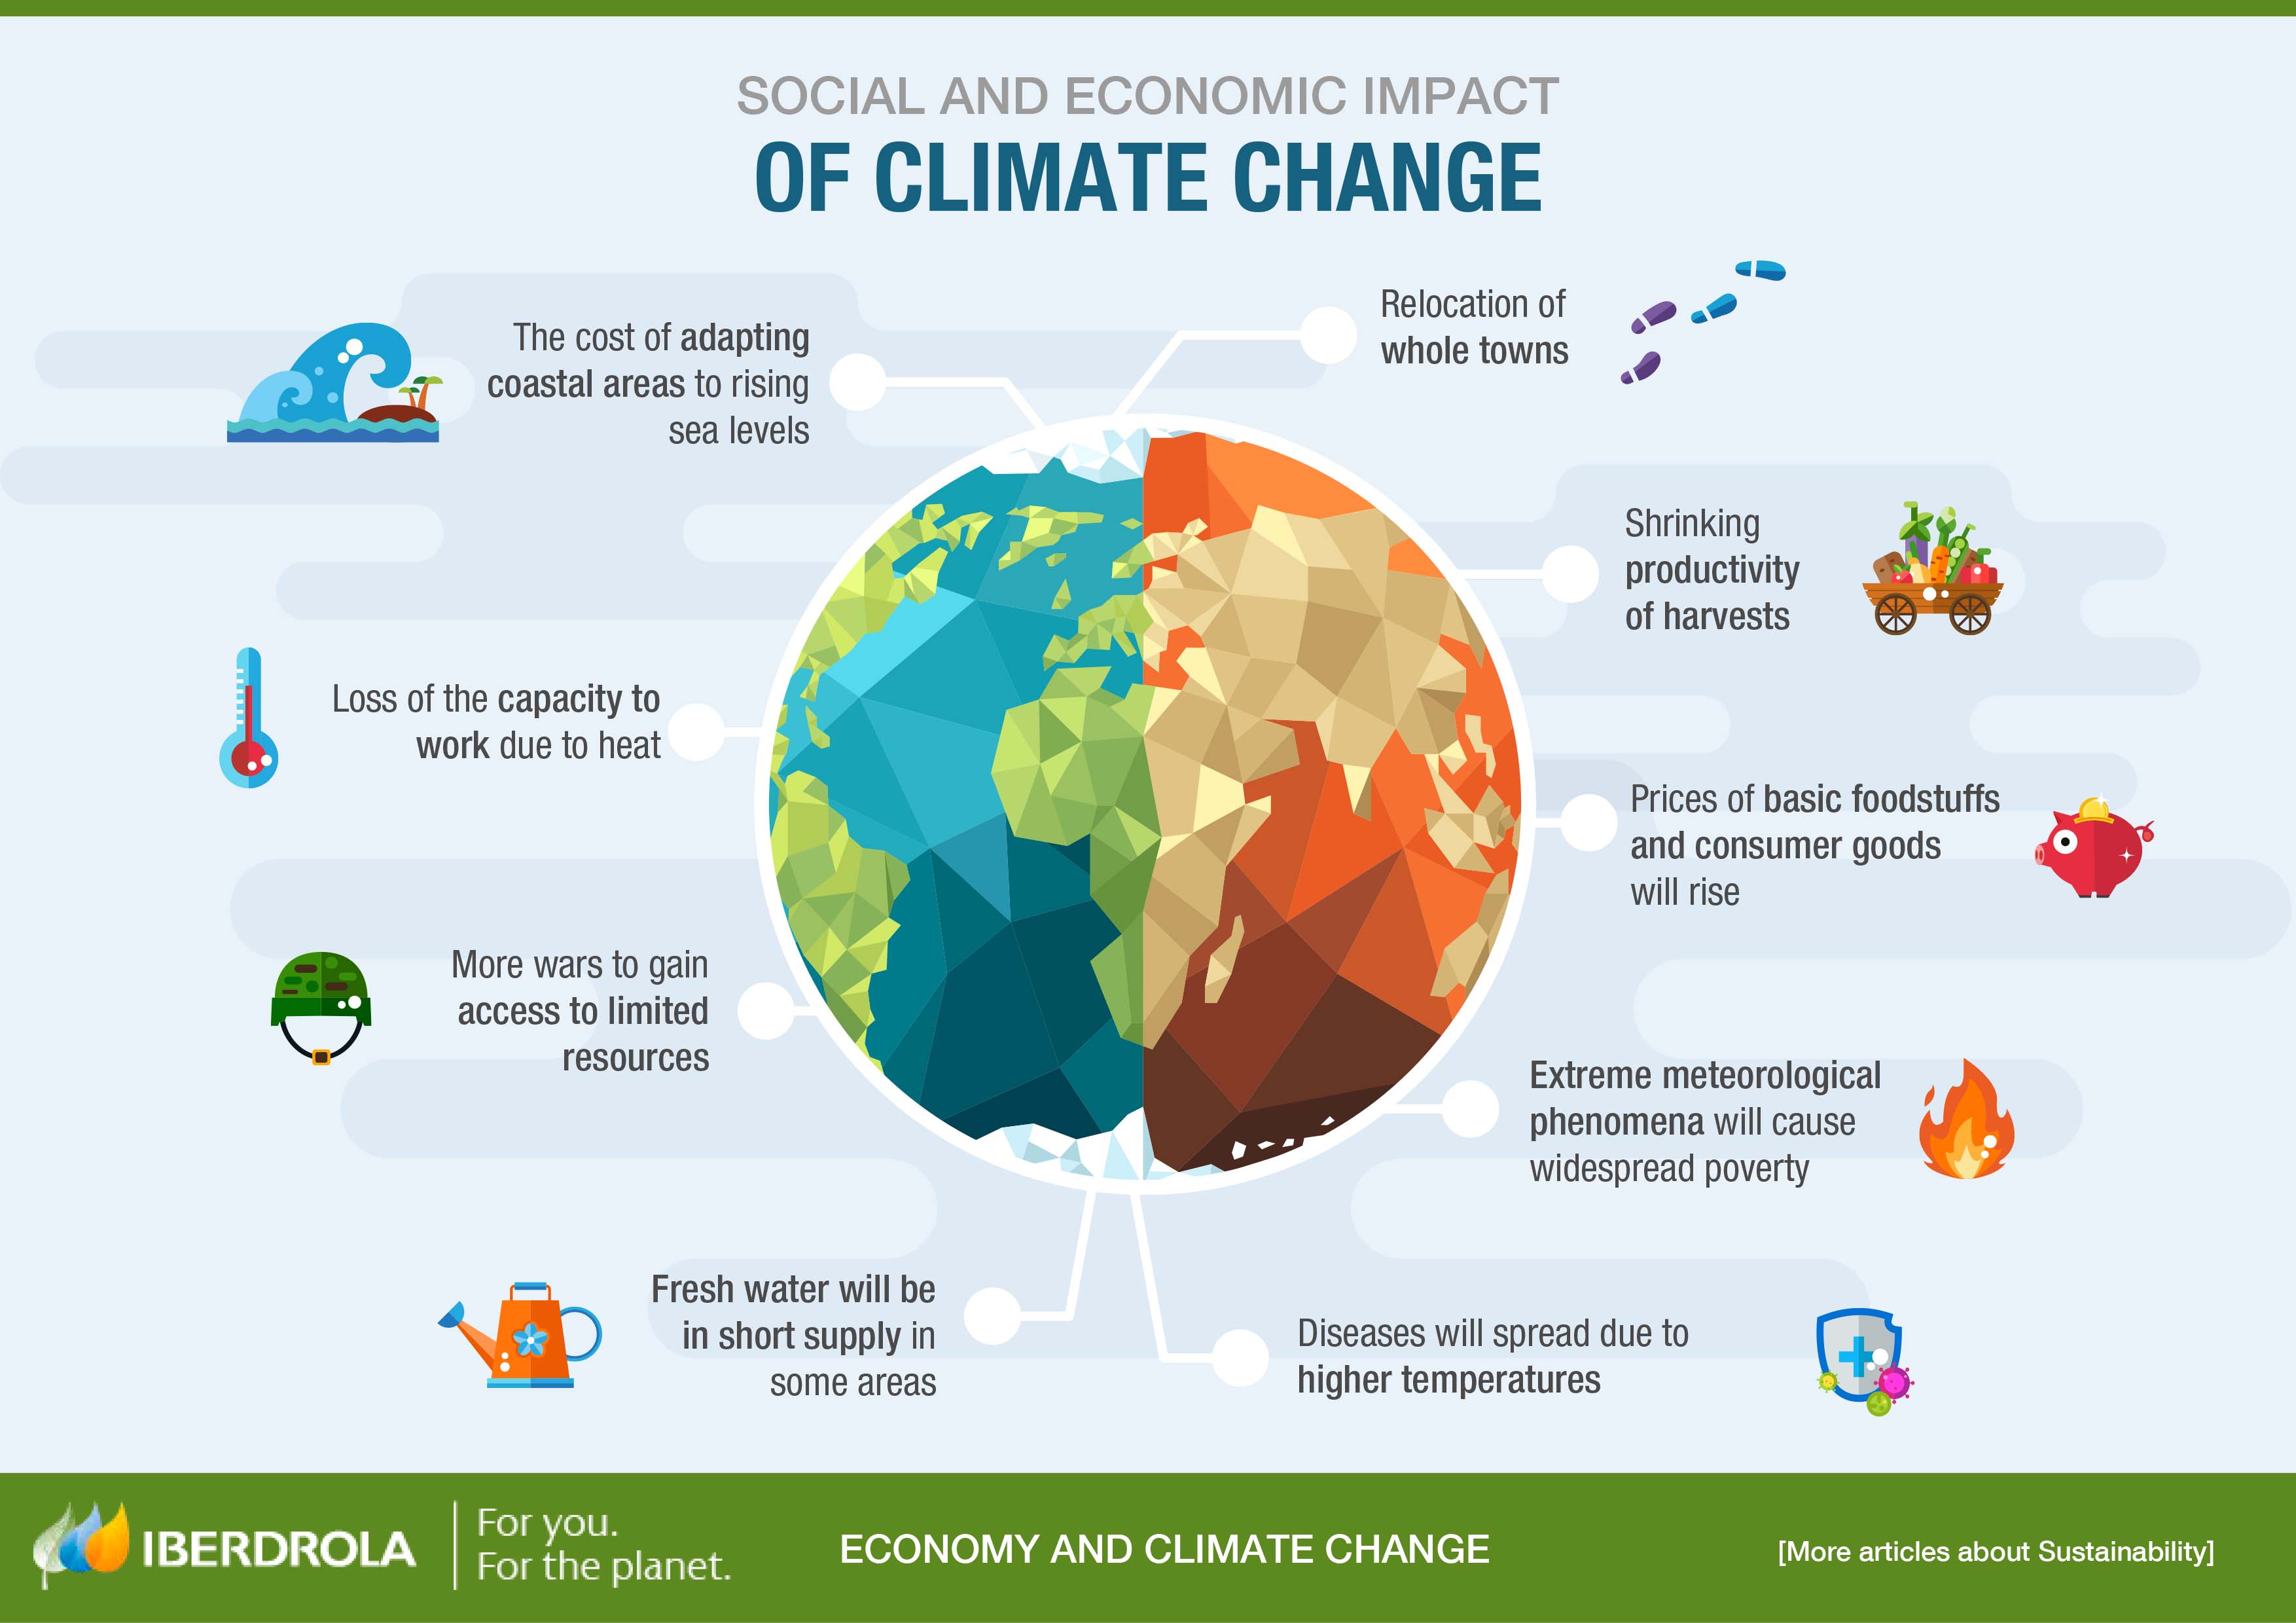
Climate change is no longer a future projection. The data is already in your bank account, your insurance premium, and your local grocery store prices. I spent about six years working in disaster risk assessment for a mid-sized firm, and I can tell you that the models we were using in 2018 are already outdated because the real-world data has been moving faster than anyone predicted. Here's what people don't understand about this shift. It's not just about hotter summers or weirder winters. The entire framework that businesses, governments, and insurance companies use to plan for the future has been broken. When I was doing flood risk modeling for residential properties in Florida back in 2020, we'd calculate a 100-year flood zone based on historical data going back roughly 70 years. By 2023, those same zones had shifted inland by several miles. The maps were wrong. The policies written against those maps were wrong. The people who bought homes based on those maps were wrong. The economic ripple effects are what hit most people, and they happen through channels most folks never think about. Crop yield volatility in the American Midwest alone has cost the average consumer an estimated $40 to $120 per year in grocery costs over the last five years. That's not a theoretical number. It shows up directly at checkout. Supply chain disruptions from extreme weather events have become routine enough that logistics companies now build climate delay buffers into their standard contracts. You see it when your package arrives three days late instead of two.
How The Impacts Actually Reach Your Daily Life
Insurance is the most direct channel. I've watched homeowners insurance premiums in coastal states double and in some cases triple between 2019 and 2024. In Florida, some insurers completely pulled out of certain counties. That's not a gradual trend. That's companies writing off entire zip codes because the actuarial tables no longer make sense. When private insurers flee, the state-backed insurers of last resort take over, and those programs are mathematically insolvent within a decade according to multiple state auditor reports. Food systems are the second channel most people miss. The wheat belt in the central United States is experiencing increased variability in growing seasons. Spring floods are destroying planted crops at higher rates, and summer heat spikes during pollination windows are reducing yields unpredictably. The result isn't necessarily permanent scarcity. It's price volatility. Prices that used to move within a narrow band now swing significantly from quarter to quarter. Healthcare costs are the third channel. Respiratory issues from prolonged wildfire smoke seasons have increased emergency room visits in western states by roughly 18 percent over a five-year span. Heat-related hospitalizations during summer months have climbed steadily even in regions that previously had minimal heat infrastructure. Insurance databases track this. Out-of-pocket costs for affected individuals rise proportionally.
The Workaround Nobody Talks About
I dealt with this directly when a client in North Carolina needed to refinance a home in an area that had just been reclassified as high-risk flood zone after Hurricane Helene. The standard refinancing options were gone. The property valuation had dropped because appraisers were now factoring in climate risk, which meant the loan-to-value ratio was unfavorable. Here's what actually worked: we structured the deal around a USDA rural development loan, which has different flood zone requirements than conventional financing. It wasn't a perfect solution. The interest rate was slightly higher, and the processing time added about three weeks. But it got the refinancing done when the conventional route was completely blocked. The broader workaround for most people involves understanding which institutions are still pricing climate risk accurately and which ones are lagging. Credit unions and smaller regional banks sometimes have more flexible underwriting than national chains because they understand local conditions better. Community development financial institutions have programs specifically designed for climate-affected areas. These aren't advertised prominently, but they exist and they're underutilized.
Get the Full Details
What Actually Works and What Doesn't
Adaptation strategies fall into three categories, and most people only address the last one. Personal preparedness — having emergency supplies, evacuation plans, knowing your local risk profile — is the obvious tier. The second tier, which most people skip entirely, is financial resilience. That means maintaining an emergency fund large enough to cover three to six months of expenses without climate-related disruptions, understanding your insurance coverage gaps before a claim happens rather than after, and not concentrating your assets in real estate in high-risk zones without appropriate hedging. The third tier is structural. Voting for local representatives who understand infrastructure investment, supporting community-level adaptation projects, and staying informed about regional risk assessments from sources like the National Climate Assessment. Most people treat these as separate activities. They're not. They compound each other. The biggest mistake I see is paralysis. People read about rising sea levels or increasing drought frequency and conclude there's nothing actionable. That's incorrect. The personal financial and logistical steps I outlined above have real measurable impact on individual outcomes. The systemic engagement matters too, but it works on a longer timeline. If you're only focusing on one, you're underprepared.
There's also the misconception that mitigation and adaptation are in tension. They're not. Individuals and communities that invest in energy efficiency improvements reduce both their exposure to fossil fuel price shocks and their carbon footprint simultaneously. Solar panels with battery storage in hurricane-prone areas provide backup power during grid failures while also displacing grid electricity. These solutions address multiple problems at once and are often more cost-effective than treating each issue separately. The data doesn't support waiting for a technological breakthrough to solve this. The economic impacts are already occurring and accelerating. The practical steps available today are sufficient to meaningfully reduce personal vulnerability. The gap isn't knowledge or technology. It's coordination and willingness to act before a crisis forces the issue.