How Zillow Became the Default Search Engine for North Carolina Housing
Zillow started as a consumer research tool. It became something else entirely. By 2019, the company had launched its Offer program and began operating as a direct buyer in select markets including Charlotte and the Research Triangle area. The shift was not gradual. Within two years, Zillow was handling thousands of transactions in North Carolina alone, and the entire landscape of how people buy and sell residential property in the state changed around that pivot. The numbers tell part of the story. North Carolina's housing market grew from approximately 147,000 existing-home sales in 2019 to over 193,000 in 2022 before moderating slightly in subsequent years. Zillow's daily active users in the state climbed well past the two million mark during that same window. That is not background growth. That is the kind of scale where a single algorithmic adjustment on their estimate engine ripples through entire neighborhoods.
The Unprecedented Growth Of Zillow In North Carolina What You Need To Know
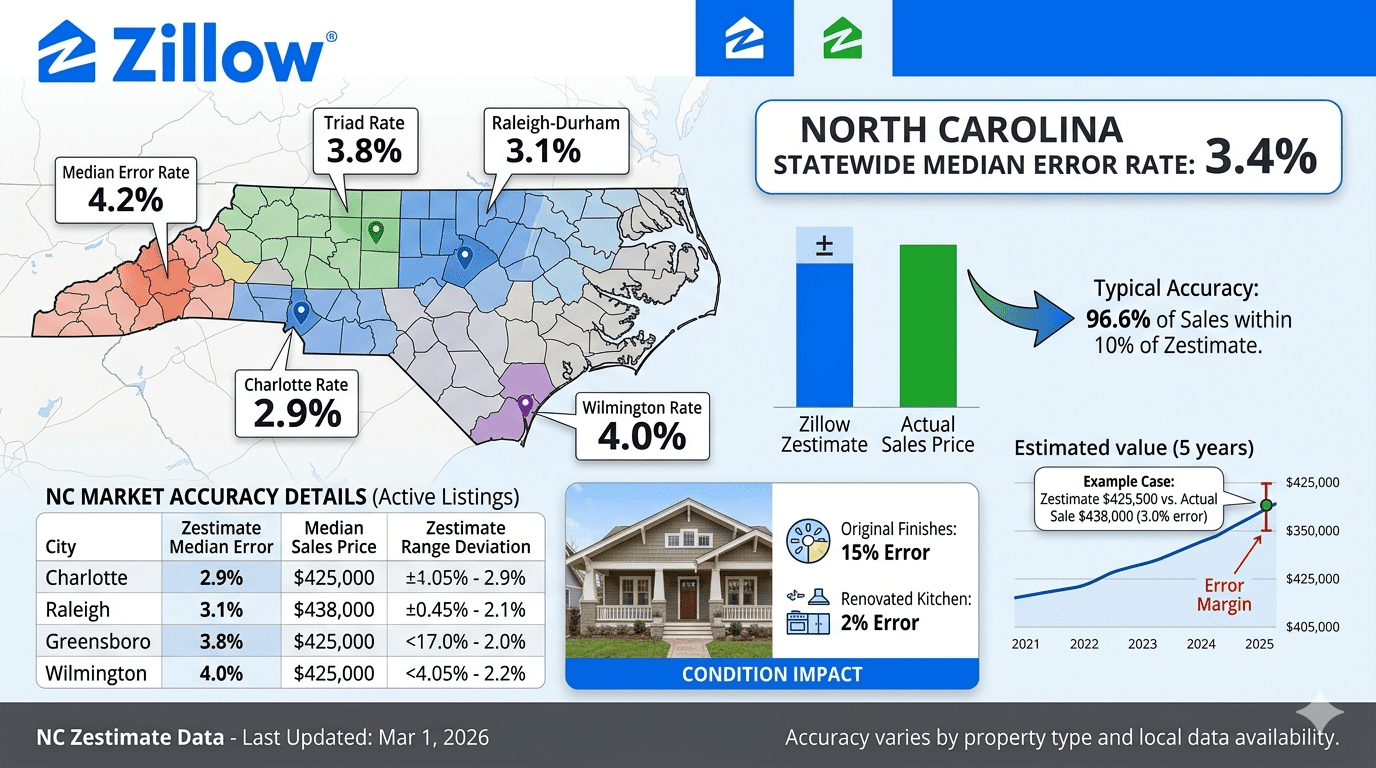
The growth itself is straightforward to document but harder to navigate practically. Zillow's dominance in North Carolina came from three converging moves: the aggressive expansion of their iBuying operation, the acquisition of mortgage and title service partnerships that pulled everything under one login, and a continuous refinament of their Zestimate algorithm using county-level public record data that most agents never look at directly. The Zestimate median error rate for North Carolina sits at roughly 6.9 percent for on-market listings, which sounds reasonable until you work with a market where median home prices in suburbs like Cary, Apex, or Ballantyne regularly exceed half a million dollars. Six point nine percent on a $520,000 home is approximately thirty-six thousand dollars. That gap shows up when a seller relies on the estimate as a pricing anchor and then watches the listing sit for forty-five days before attracting showings because the number felt authoritative but was off by a margin that mattered in real money. Here is something most first-time sellers in the state do not understand about the platform. Zillow pulls its data from county GIS and tax records, but North Carolina is one of the few states where those records are updated asynchronously across one hundred thirteen counties with completely different schedules. Wake County might refresh parcel data monthly. Swain County in the western mountains might do it quarterly. Macon County on a different cadence still. When Zillow runs its automated valuation model, it is working with whatever the last recorded assessment was in each county, and in fast-moving markets that creates stale baselines that drift further from reality the longer the gap between updates.
I dealt with this directly in 2023 when a client in Raleigh wanted to list a renovated bungalow near the Glenwood South district. The Zestimate came in at $485,000 based on an outdated square footage figure from a 2019 permit that had never been closed out in the county system. The actual finished square footage after a legal second-floor addition was approximately nine hundred square feet more than what the algorithm was using. We pulled the recorded permit from the Wake County GIS portal, cross-referenced it with the tax assessment ledger, and documented the discrepancy in writing before listing. The home sold for eleven percent above the Zestimate, and the buyer's agent had already flagged the estimate in their initial offer discussion because Zillow displays prominently on their side of the transaction too. The workaround is not complicated but it is not obvious either. Before trusting any Zestimate for a pricing decision in North Carolina, pull the most recent deed transfer for the property from the county register of deeds, check the current tax assessment against the assessed land versus improvement split, and compare the gross living area figure on the tax record to what is physically in the house. If three data points diverge, the estimate is probably working from incomplete information and you need an actual comparative market analysis from a local agent who knows the micro-market rather than relying on a statewide algorithm. For buyers the situation is subtly different. Zillow's platform aggressively surfaces the Estimated Monthly Payment breakdown, which includes principal, interest, taxes, and insurance calculated from the list price and a user-selected down payment percentage. The tax component uses the county's current annual tax amount divided by twelve, but North Carolina property taxes vary wildly between municipalities even within the same county. A home in Charlotte's city limits pays municipal taxes on top of county taxes. A home in Mecklenburg County unincorporated territory pays county-only rates. A home in Davidson County carries an entirely different millage structure. The payment estimate on Zillow does not account for these municipal overlays, and I have seen buyers budget around a monthly figure that turned out to be two hundred to four hundred dollars short once closing costs and actual tax bills landed.
Get the Full Details

Another practical detail that matters in North Carolina specifically is how the platform handles waterfront and lake properties. The state has thousands of shoreline parcels along Lake Norman, Wylie Lake, Smith Mountain Lake, and the many smaller reservoirs that dot the Piedmont region. Zillow's listing engine does not distinguish between riparian rights, lake access through a privateHOA, and direct waterfront frontage with deed-defined shoreline. A buyer looking at a listing tagged as "lake view" might assume waterfront access that does not actually exist in the deed. The workaround is to request the survey and the shoreline delineation from the listing agent before making an offer, not after inspection. Zillow will not provide that level of granularity. The iBuying side of Zillow's North Carolina presence deserves its own scrutiny because the mechanics are different from a traditional sale and most people do not read the fine print. Zillow Offers operated in Charlotte, Raleigh, and a few surrounding submarkets before winding down the program nationally in late 2021. When it ran, the trade-in and direct purchase options were fast but expensive. The typical all-cash offer came in at roughly eighty-five to eighty-eight percent of after-repair value minus repair estimates and a service fee that could run another five to eight percent depending on condition. For a home appraised at three hundred thousand dollars needing fourteen thousand dollars in repairs, the net to the seller could land somewhere between two hundred fifty and two hundred sixty-five thousand dollars after all deductions. That speed came with a real cost premium compared to a standard MLS listing. If you are evaluating whether to use Zillow's transaction services versus working with a traditional agent in North Carolina, the calculation hinges on three variables: your timeline, your property's condition, and how much you value certainty over maximum proceeds. A cleanlisted home in good shape in a competitive submarket like Huntersville or South Charlotte will typically net more through a conventional sale because the commission cost is offset by a higher sale price. A distressed property that needs significant repair and the seller cannot wait ninety days for a traditional close might find the iBuying path, or its current equivalents through other operator-buyers, more useful despite the lower net.
There is also a data transparency issue that has not received enough attention in the state. Zillow publishes its transaction history and price change logs publicly, which is useful, but the platform does not always distinguish between an intentional price reduction and a system-generated recalculation triggered by a new comparable sale in the neighborhood. A seller in Greensboro noticed their Zestimate drop by eighteen thousand dollars overnight after a similar home two streets over sold for less. The algorithm adjusted. The seller's perception of their home's value shifted accordingly, and they almost accepted a low-ball offer because the number looked validated by the platform's own math. The comparable sale was an outlier caused by a motivated seller and an off-market family transaction, not a market trend. Manual verification of the comps behind any sudden estimate change prevents this class of mistake entirely. Mortgage and title services attached to the platform have created another layer of complexity for North Carolina buyers. Zillow's mortgage division partners with multiple lenders, and the pre-approval letters generated through the platform are legitimate, but the rates and terms displayed are snapshot estimates that can shift within a single business day depending on market movement and the buyer's credit profile at the time of application. The estimate tool does not lock anything. It generates a hypothetical payment range. Actual lock rates, points, and lender-specific closing cost structures in North Carolina vary enough that relying on the displayed estimate for budgeting without getting a real Loan Estimate from a licensed lender within forty-eight hours of application is a recipe for surprise costs at closing. North Carolina is a contract state, not an escrow state, which affects how the platform's tools interact with actual transaction flow. In contract states the purchase agreement is executed first and escrow opens after. Zillow's transaction timeline templates do not always reflect this sequencing accurately, and I have seen buyers confused about when earnest money was actually due versus when the platform suggested it should be. The platform's default calendar assumes standard escrow timelines that align with Western states more closely than with North Carolina practice. This is a small operational detail that can cause real friction if someone follows the platform's suggested dates instead of their attorney's instructions.
The practical takeaway is that Zillow in North Carolina functions best as a research and discovery tool with some transactional capabilities layered on top, not as an authoritative pricing engine or a substitute for local professional guidance. The data is broad but uneven. The estimates are directional. The transaction pathways work but carry costs and conditions that are not always visible until you are midway through the process. Local agents who understand county-level data discrepancies, municipal tax variation, and the actual negotiation dynamics in North Carolina submarkets still provide more value than any platform feature, particularly when the market shifts direction as it has done repeatedly since 2022. If you are a seller, pull your county records yourself before listing. If you are a buyer, verify every tax and square footage figure against the deed and survey rather than trusting the listing display. If you are considering a Zillow Offer or similar program, run the numbers on paper including the repair deduction, the service fee, and the opportunity cost of selling faster versus selling for more through a traditional channel. The platform is powerful. It is also not infallible, and the people who get the best outcomes in North Carolina's market are the ones who use it as one input among several rather than the final word.