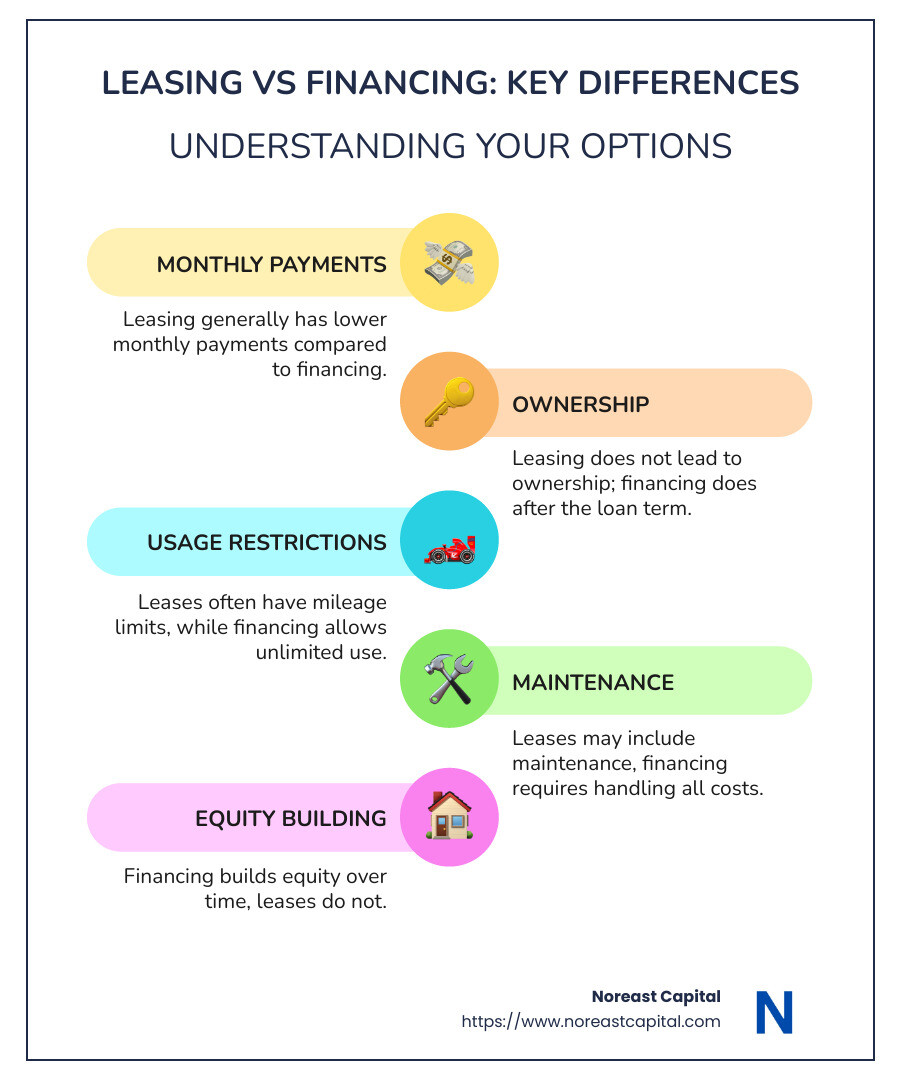
Commercial Financing: Leasing vs Mortgage
Most people approach commercial property financing by looking at monthly payments alone. That misses the actual decision. The real question is whether you want ownership equity building on a depreciating asset or operational flexibility with a fixed ceiling on your downside. A mortgage gives you the deed. The bank doesn't care how you run the business, and the property typically appreciates over a 15 to 30 year horizon if you're buying in a market that actually grows. But mortgages come with personal guarantees, down payments between 20 and 35 percent for commercial properties, and closing costs that run 2 to 5 percent of the loan amount. On a half million property, that's $10,000 to $25,000 sitting in escrow and legal fees before you get keys. Leasing turns that capital into operating budget. You might pay $3,000 a month instead of putting $150,000 down. The landlord covers major structural repairs. Your balance sheet looks cleaner. Banks like it when you lease because your debt-to-income ratio stays lower, which means you can qualify for more credit lines while you still have cash for inventory or hiring.
Here's what nobody tells you: a triple net lease sounds simple but the CAM charges are where margin dies. Common area maintenance escalates every year, often tied to CPI or a fixed 3 to 5 percent add-on that compounds silently. I learned this the hard way in 2019 when I signed a five year NNN lease for a warehouse space. The base rent looked competitive at $18 per square foot. CAM charges started at $4.50 and jumped to $6.20 by year three because the property management company decided the roof needed "supplemental addressing" and parking lot resurfacing. My effective rent went from $22.50 to $24.20 per square foot without a single renegotiation clause protecting me. The workaround was simple but painful: I spent three weeks before signing reviewing the last two years of CAM statements from that exact property and had my broker demand a CAM cap at 3 percent annual escalation with an audit right written into the lease. That cost me $2,000 in legal fees upfront but saved me roughly $8,400 over the remaining lease term when the charges tried to spike again in year four. Mortgages have their own trap. Adjustable rate commercial loans reset after five to seven years based on SOFR plus a spread. If rates climb 200 basis points at reset, your payment jumps immediately. I've seen business owners get squeezed out because they calculated payments at 5.5 percent and the reset hit 7.8 percent with no bridge savings. The fix is a rate buydown at closing. Pay points upfront to lock a lower rate for the first five years, giving you time to refinance into a fixed rate or grow revenue enough to absorb the reset. A 2-1 buydown on a $400,000 loan at 6 percent costs about $4,800 in points but saves roughly $1,200 annually during years one and two. Depreciation matters more than people think. A commercial mortgage lets you take MACRS depreciation, usually 39 years for nonresidential buildings. That's a significant tax shield in the early years. Leasing gives you Section 179 expensing on equipment and certain leasehold improvements, but you're not depreciating the structure itself. If your business is profitable and you want to reduce taxable income, the mortgage wins on taxes. If you're operating at a loss or thin margins, the lease keeps more cash in your pocket month to month.
Another edge case: lease assignments versus mortgage assumptions. If you need to sell or sublet before the term ends, a mortgage assumption requires lender approval and credit review, which takes 30 to 60 days and often requires the new buyer to qualify at current rates. A lease assignment is faster but most commercial leases have an assignment clause requiring landlord consent and sometimes a fee of 1 to 2 percent of remaining rent. I once had a client who needed to exit a commercial lease in eight months because the tenant mix at the center shifted and foot traffic dropped 40 percent. The lease allowed assignment with consent, but the landlord dragged their feet for six weeks asking for documentation that should have been standard. The workaround was filing a formal demand letter citing the state's commercial landlord-tenant code, which requires reasonable cooperation in assignment approvals. The consent came through in five business days after that. Maintenance responsibility is the silent killer of lease economics. In a gross lease, the landlord handles HVAC replacements, roof repairs, and structural issues. In a net or triple net, those become your problems. A commercial HVAC system costs $15,000 to $40,000 to replace. A flat roof replacement runs $8,000 to $20,000. Over a ten year lease, you could be looking at two or three major capital expenditures that erode the monthly savings you thought you were getting. Equity buildup from a mortgage is forced savings with upside potential. Your principal payments go toward ownership. Property appreciation, if the market moves, adds to your net worth. Leasing builds nothing. At the end of a five year lease, you own zero. You've paid for occupancy, not assets. That matters when you're 45 and trying to build retirement wealth through real estate. I've watched too many business owners lease for a decade thinking they were being "smart" with capital, only to find themselves competing against buyers who locked in properties at 2015 prices and now own appreciated assets free and clear.
Get the Full Details

The break-even calculation is straightforward but people skip it. Take the difference between your lease payment and your mortgage payment, including taxes and insurance. Divide by your closing costs or leasing commissions to find how many months until ownership pays for itself. On a typical small commercial property, that break-even point sits around 36 to 60 months. After that, every mortgage payment is pure equity accumulation while the lease payment remains pure expense. Interest rate environment changes everything. When rates are under 6 percent, mortgages look attractive. When they're over 9 percent, leasing becomes the rational choice for cash flow preservation. Right now, we're in a zone where both options have real trade-offs and the decision depends entirely on your specific situation, not some universal rule. Your credit profile also determines which path is even available. Commercial mortgages require a DSCR of 1.25 or higher, meaning net operating income must exceed debt service by 25 percent. If your property barely covers the mortgage, lenders walk away. Leasing has no such requirement. Landlords care about your business viability, not debt service coverage ratios. This is why struggling startups often lease while established operators buy.
Flexibility favors leasing. Need more space in three years? Sign a new lease. Want to downsize? Negotiate an early termination with a reasonable fee. With a mortgage, you're stuck with the property until you sell or refinance, and selling a commercial property takes 90 to 180 days minimum with 5 to 7 percent in transaction costs. The right answer depends on your timeline, your cash position, your tax situation, and your risk tolerance. There is no superior option across all scenarios. The mortgage owner who can handle vacancies and maintenance headaches builds wealth over decades. The leaseholder who preserves capital and maintains operational flexibility survives downturns and scales faster. Pick based on where you actually are, not where you hope to be in five years.