Comparing Fidelity and LPL Financial as Advisor Platforms
The reason I keep coming back to comparing these two is that they serve very different types of advisors and clients. Fidelity is a self-clearing powerhouse, while LPL is a franchise-based independent broker-dealer. One isn't inherently better than the other, but picking the wrong one can cost you thousands in unnecessary fees or limit the strategies you're allowed to run. Let me start with what actually matters on a day-to-day basis. With Fidelity, you're working inside their proprietary ecosystem. The custodian, the execution, the reporting — it's all one platform. That simplicity is their biggest selling point and also their biggest limitation. If you want to bring outside assets from another firm, Fidelity handles rollovers well, but if you need something non-standard, like a direct transfer of a private placement or a complex trust structure, you'll hit walls quickly. LPL, on the other hand, operates as an introducing broker-dealer network. They clear through their own channel but support a much wider range of third-party platforms and products. This matters more than most people realize. I learned this the hard way in 2019. A client wanted to implement a collateralized mortgage obligation strategy using non-traditional financing through a credit union line of swap. Fidelity wouldn't touch it. Their compliance team flagged it as outside the standard product menu, and the paperwork chain just stalled out for six weeks. I ended up moving that account to an LPL representative who had dealt with something similar before. The workaround was filing a manual suitability overlay and getting pre-approval from LPL's risk committee, which took about ten business days instead. That experience alone taught me that the platform choice isn't a minor detail — it defines what you can and cannot do for certain clients.
Fidelity's fee structure is straightforward. For basic brokerage accounts, you pay per-trade commissions that have dropped to essentially zero for stocks and ETFs. Bonds and mutual funds carry small fees. What really adds up is their account maintenance side if you don't meet their minimum thresholds, which vary by account type but typically sit around $10,000 to $25,000 depending on whether you're looking at individual or joint accounts. Advisors who work with Fidelity often absorb these costs through their own advisory fees rather than passing them directly to clients, which makes the pricing look cleaner on paper than it actually is. LPL's pricing is less transparent. They charge membership fees, compliance monitoring fees, and transaction-based costs that compound across different product lines. A single client holding actively managed mutual funds through LPL could easily see 1.5 to 2 percent in annual recurring costs including both advisory fees and underlying fund expenses. Compare that to a Fidelity-advised client holding index funds, where total costs might land closer to 0.5 percent. That gap compounds significantly over time. Over fifteen years on a $500,000 portfolio, the difference between those cost levels translates to roughly $28,000 to $56,000 in drag depending on the exact fee structure. Here's something most comparison articles miss. Fidelity's reporting tools are actually superior for client-facing materials. Their dashboard generates IRS-compliant forms, performance attribution reports, and tax-loss harvesting suggestions automatically. LPL's reporting requires more manual intervention. If you're an advisor managing fifty or more client accounts, that difference between automated and manual reporting accounts for maybe five to eight hours per month. That's not trivial when you're trying to scale.
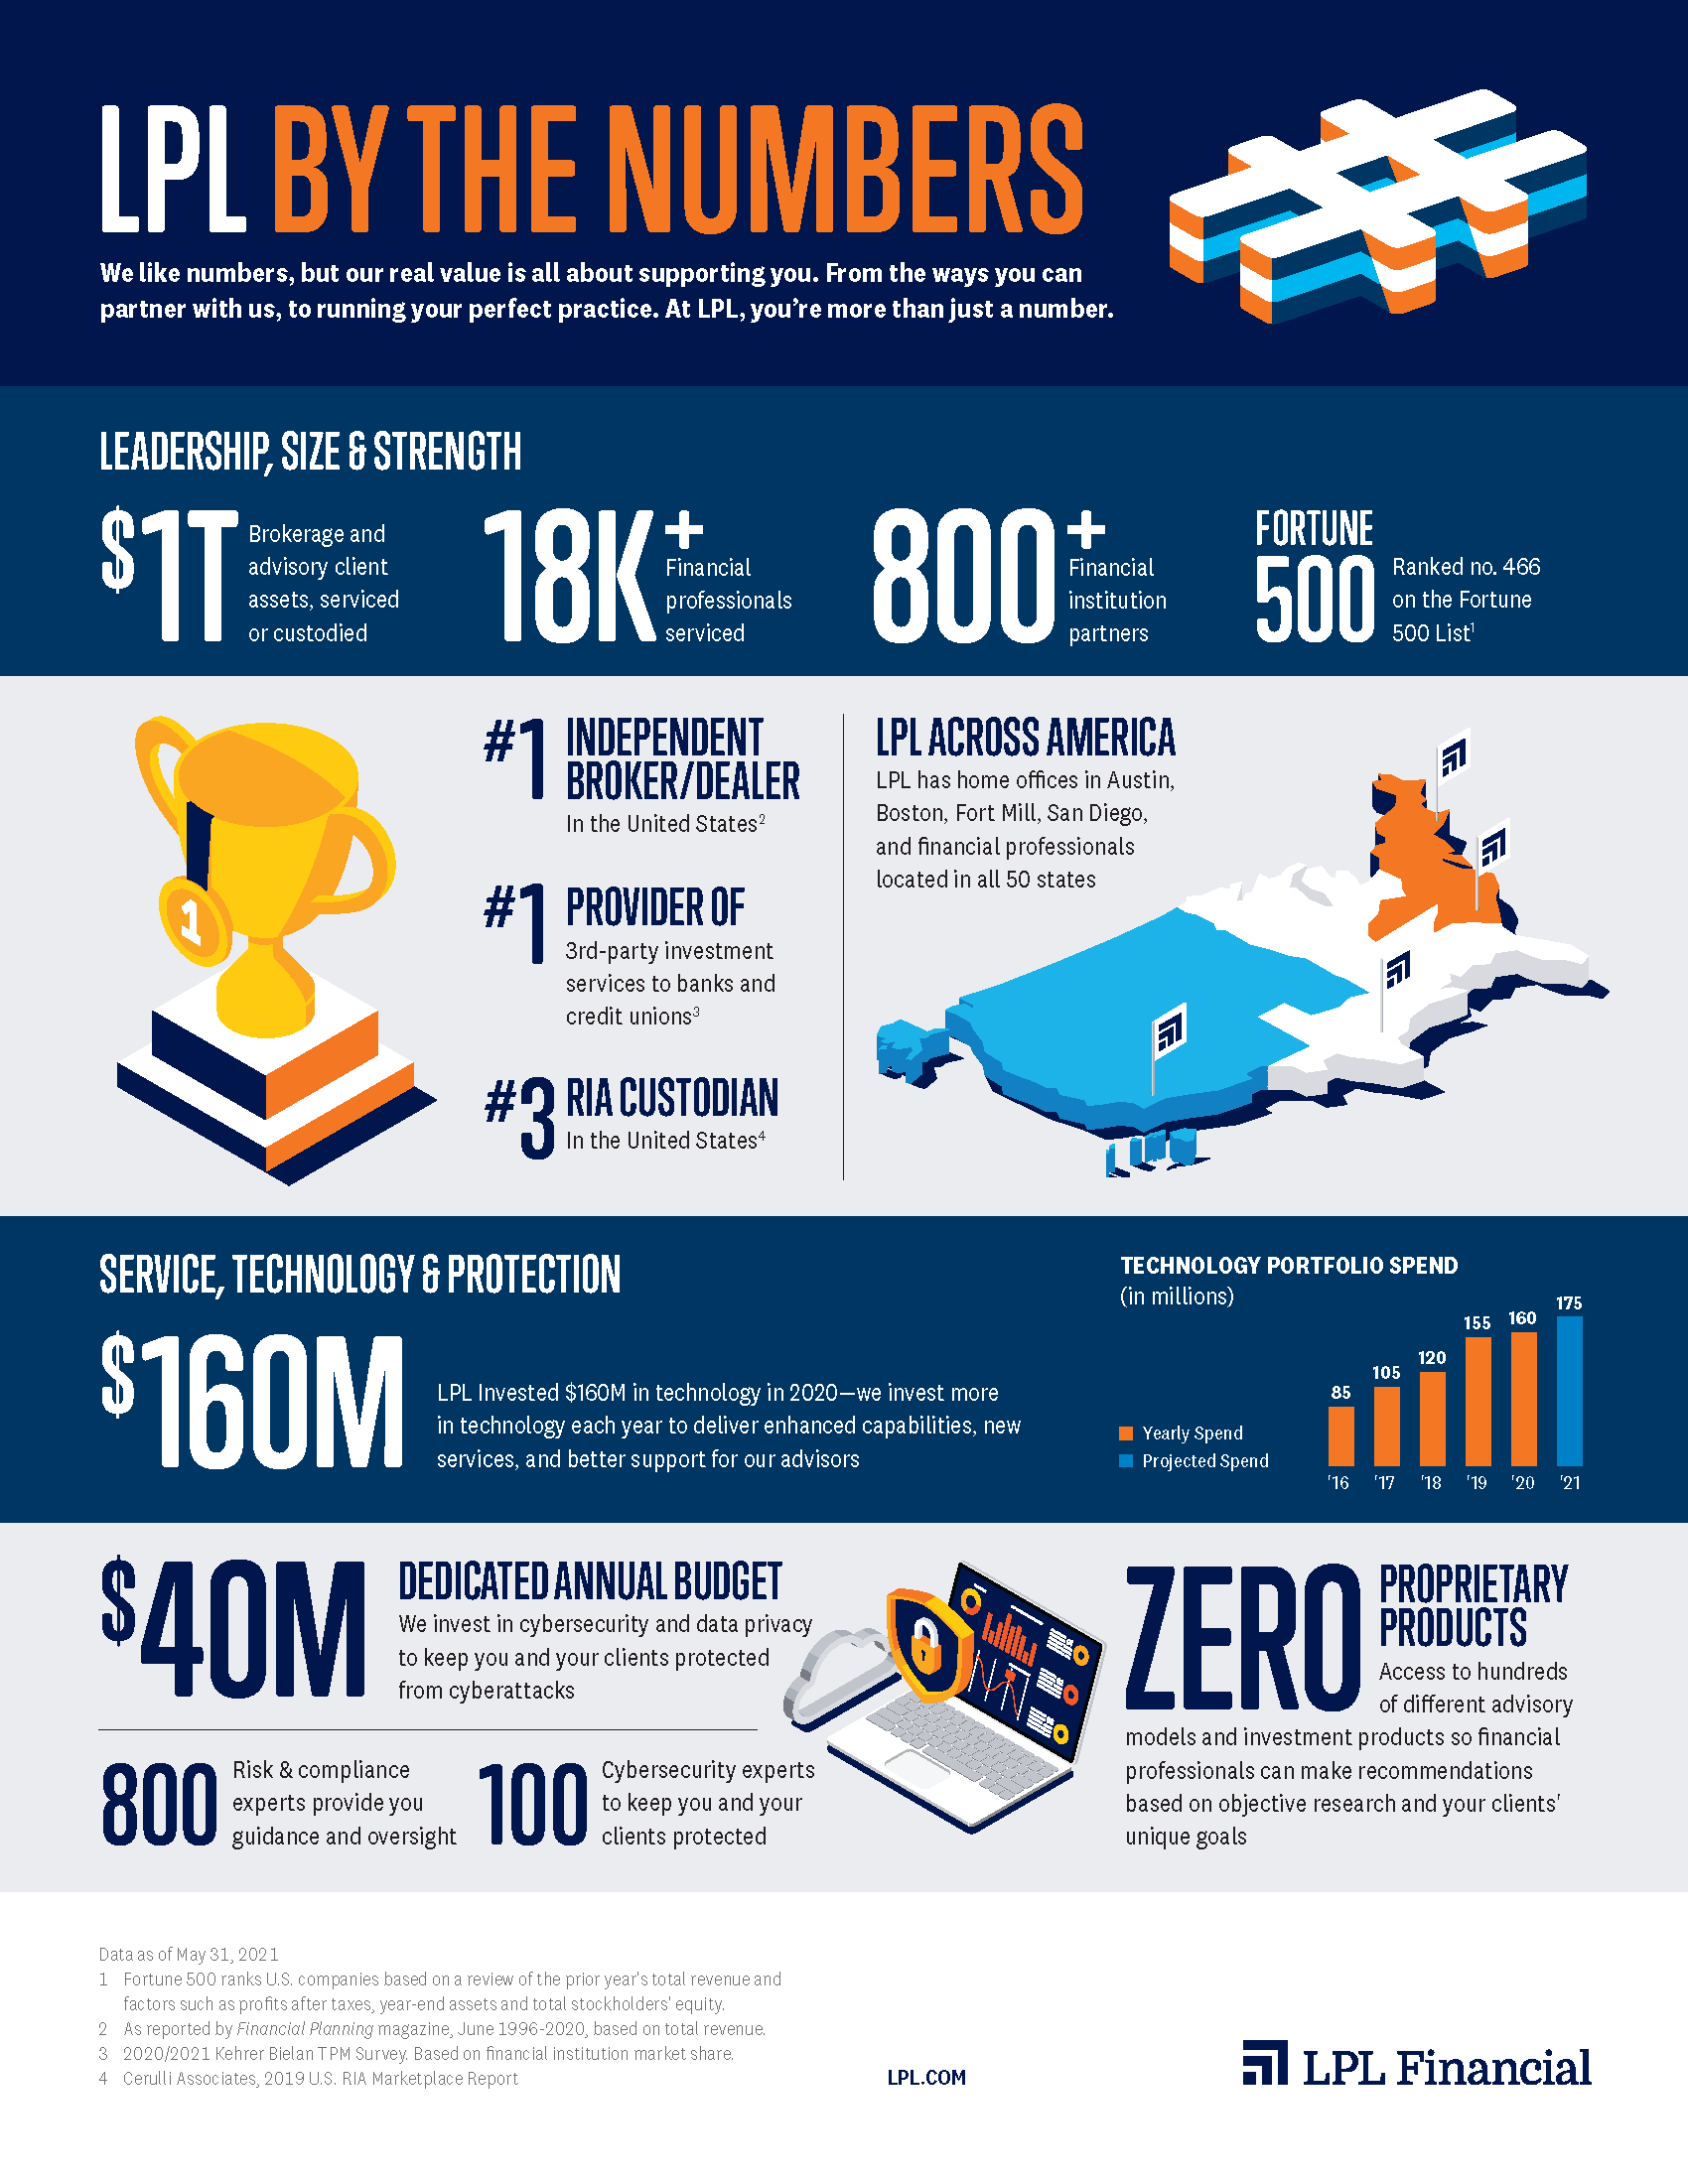
But LPL wins on product breadth. They offer access to hedge funds, private equity co-investments, insurance products, and alternative investments that Fidelity either doesn't support or supports through a much narrower set of providers. If your client base includes high-net-worth individuals who need estate planning vehicles beyond standard IRAs and 529s, LPL's network of registered representatives who specialize in those areas gives you options Fidelity simply doesn't provide. The tradeoff is that those specialists aren't always easy to reach, and coordination between your firm and an LPL rep can add weeks to deal timelines. Onboarding is another area where the difference becomes immediate. Fidelity's application process is fully digital and mostly automated. A new client can complete the entire intake in under twenty minutes if their documents are organized. LPL typically requires a face-to-face meeting or at minimum a phone consultation with a registered representative before any paperwork gets filed. This slows things down but it also means you're working through questions in real time, which reduces errors from incomplete information. I've seen Fidelity onboarding produce accounts with incorrect beneficiary designations because the system accepted incomplete fields without flagging them. LPL's manual review catches those issues before the account opens. The regulatory environment differs too. Fidelity operates as a full-service broker-dealer and investment adviser, which means their compliance team enforces a single set of rules across all products. LPL members are independent contractors who may have varying levels of compliance oversight depending on their office and regional manager. This isn't a criticism of LPL specifically — it's just a structural reality. When something goes wrong, Fidelity's centralized compliance model means faster resolution but less flexibility. LPL's decentralized model means slower responses but more room to negotiate exceptions for unusual situations.
Get the Full Details

For most financial advisors starting out, Fidelity makes sense if your clients are primarily middle-market — incomes between $75,000 and $200,000, portfolios under $1 million, and relatively simple needs like retirement planning and basic tax management. The technology is clean, the costs are predictable, and you can manage dozens of relationships without burning through your weekend doing manual data entry. If you're serving clients with $1 million or more in investable assets, or if those clients need estate planning trusts, alternative investments, or specialized insurance products, LPL's ecosystem provides more tools even though the experience is rougher around the edges. The key is finding the right LPL representative who actually understands what you're trying to accomplish rather than someone who just wants to move products that generate the highest commissions. Neither platform is perfect. Fidelity locks you into their product universe, which works well until it doesn't. LPL gives you freedom but demands more hands-on management of the administrative burden. The best advisors I know use both, keeping their simpler accounts at Fidelity and moving complex clients to LPL when the situation calls for it. It's not elegant, but it's practical, and practical beats elegant when you're trying to build a sustainable practice.