Understanding What $25 an Hour Actually Gets You
The Ultimate Salary Calculator Unraveling The Mystery Of 25 Per Hour
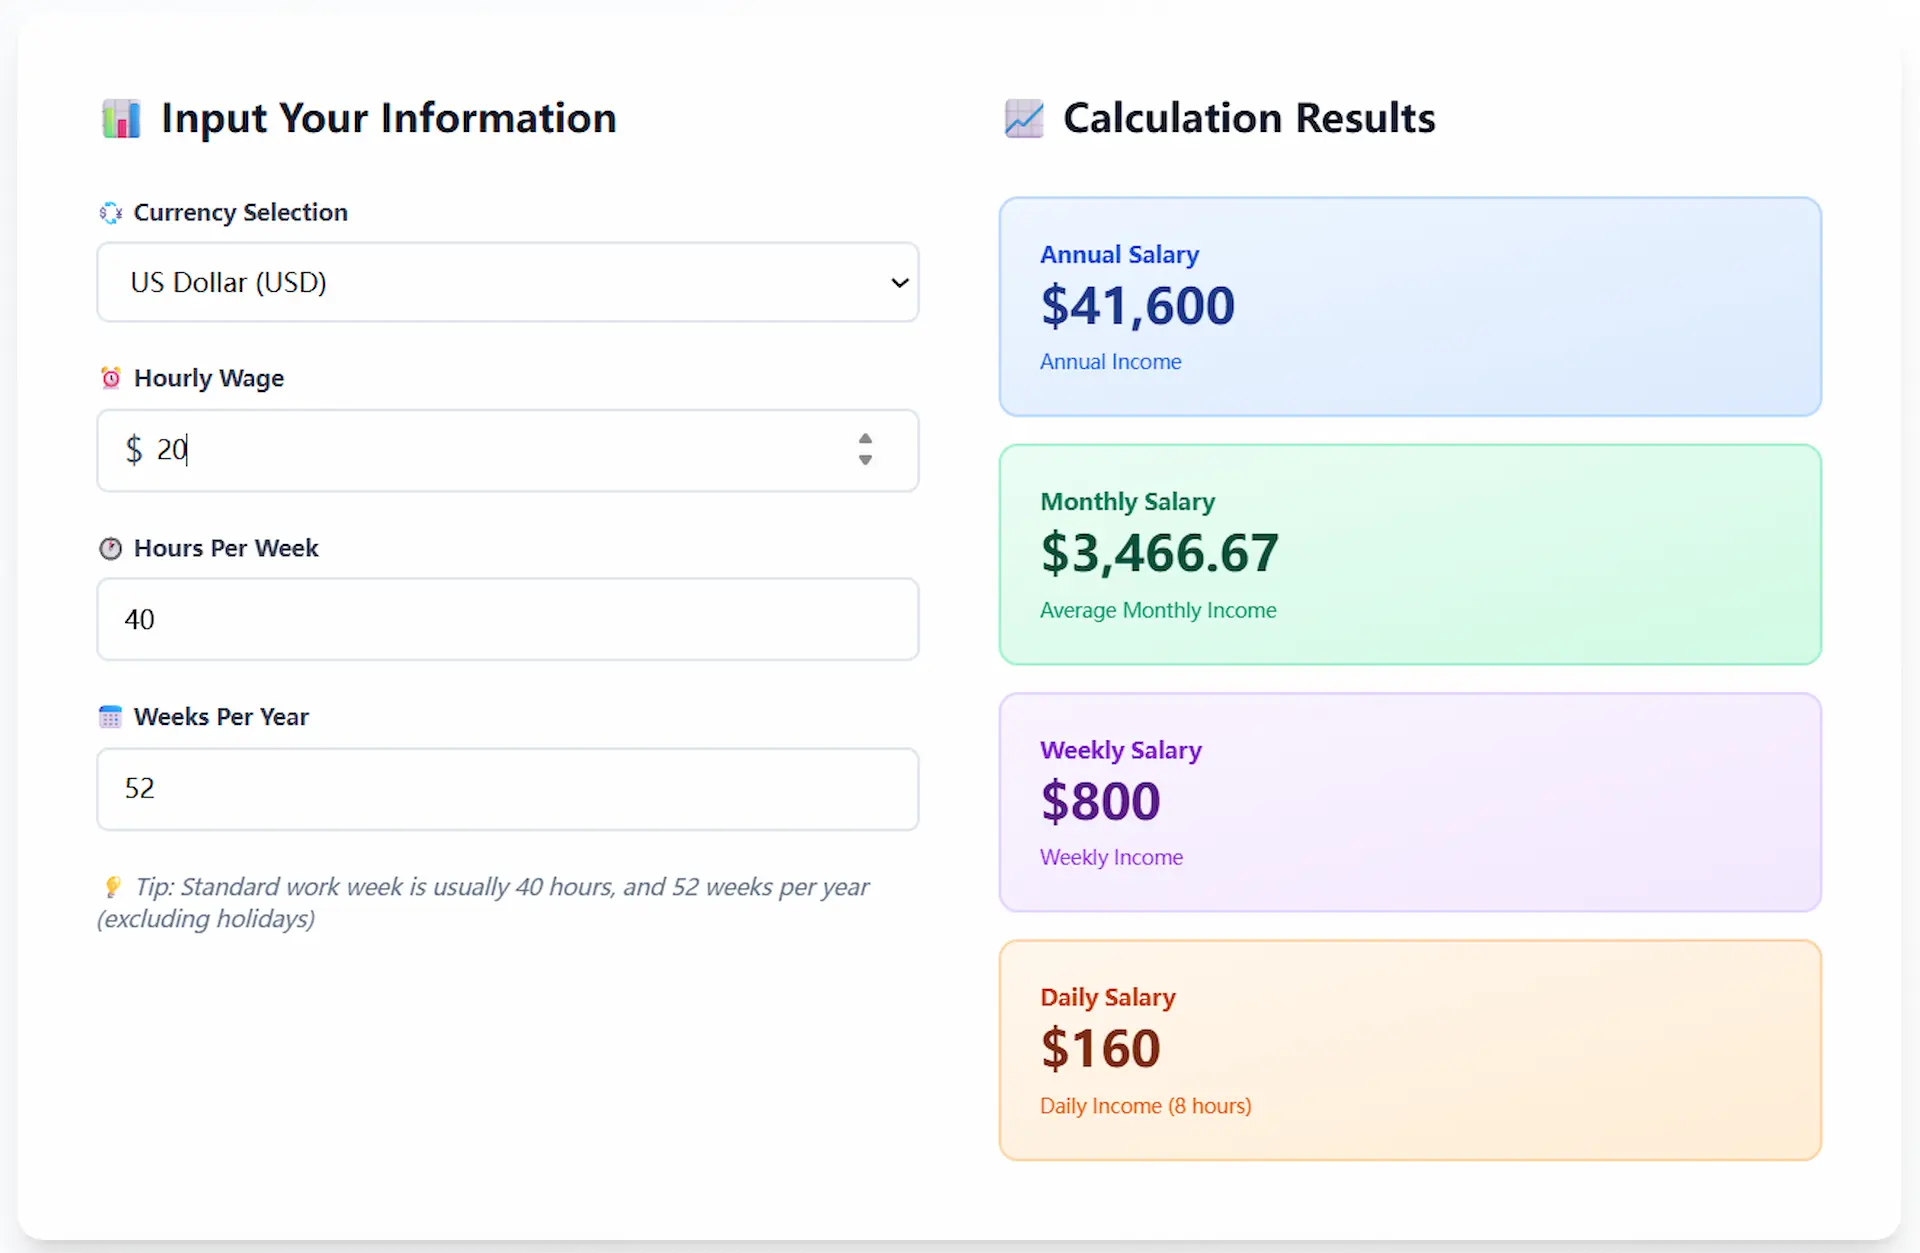
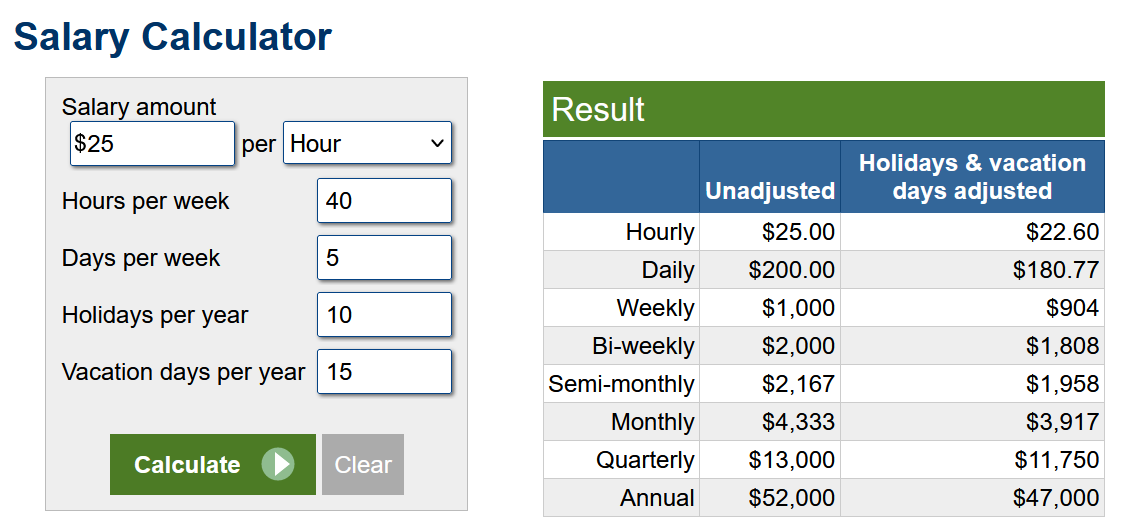
$25 per hour converts to $52,000 per year on paper. Multiply by 2,080 hours, which is 40 hours times 52 weeks. That's the standard calculation, but it only tells you the gross amount. The actual number hitting your bank account depends on a series of deductions most people don't think about until their first paycheck arrives and they realize it looks nothing like the $52,000 they started with. Gross vs. net pay is where this gets real. Gross is everything before anything is taken out. Net is what remains after mandatory and voluntary withholdings. The gap between those two numbers is what most salary calculators gloss over, and it's also where people get surprised.
Running the numbers manually
Start with the gross figure of $52,000. From there, you subtract FICA taxes first. Social Security is 6.2% and Medicare is 1.45%, which totals 7.65%. On $52,000 that's about $3,978. Next come federal and state income taxes, which depend entirely on your filing status and tax bracket. A single filer at that income level lands in the 22% bracket after the standard deduction, which works out to roughly $6,500 to $7,500 in federal taxes depending on the exact bracket thresholds for the year. State taxes vary wildly. If you live in Texas or Florida, you're looking at zero state income tax. If you live in California or New York, you could be looking at another $2,500 to $4,000 depending on your city and county. That leaves you with a rough net range of roughly $38,000 to $43,000 annually, or about $1,550 to $1,760 per month before any additional voluntary deductions. The margin of error here is meaningful because every individual situation shifts things.
The edge case I keep running into
I deal with this repeatedly when someone has a second income or is filling out a W-4 for the first time. The standard formula assumes one job, one withholding pattern, a single standard deduction. It breaks down the moment someone has two jobs paying $25 an hour each, or a W-4 that was filled out incorrectly during onboarding. The combined income pushes you into a higher effective tax bracket than a single-jobs calculator would predict. I've seen people arrive at paychecks that were $400 to $600 short per period because their withholding didn't account for the second job kicking them into additional Medicare taxes or a different marginal rate. The workaround is straightforward but rarely obvious: run both incomes through the IRS withholding estimator instead of a generic salary calculator, and specifically check whether you need to claim additional withholding on Form W-4 line 4(c). Retirement contributions, health insurance premiums, dental and vision plans, flexible spending accounts, and cafeteria plan elections all reduce your taxable income. A 401k contribution of $500 per paycheck is $13,000 a year. That drops your gross taxable income from $52,000 down to $39,000, which can pull you out of the 22% bracket entirely and into the 12% bracket. The immediate tax savings on that $13,000 contribution might be $1,400 to $1,800 depending on your state, but the real benefit compounds over time since you're deferring taxes and investing pre-tax dollars. HSA and FSA contributions work similarly but have their own rules. HSA contributions are triple-tax-advantaged if you have a qualifying high-deductible health plan. FSA funds use \"use it or lose it\" rules, so over-contributing is a common mistake that costs people money at year end.
Get the Full Details
What most calculators get wrong
The biggest blind spot is the lack of granularity in withholding assumptions. Most free online salary calculators apply a flat effective tax rate across the board. That's lazy math. The US federal system is progressive, and applying a flat rate either overestimates or underestimates your actual liability depending on where you fall. A more accurate approach uses the actual tax bracket tables for your filing status and year, then applies the standard deduction or itemized deduction separately. It takes longer, but it cuts the error margin from about $1,000 to maybe $200 or less in most cases. Another common failure is ignoring local taxes. City and county income taxes exist in places like Ohio, Pennsylvania, New York City, and several other municipalities. These are often overlooked in national-level calculators and can add another $300 to $1,200 to your annual tax bill depending on location.
When the calculator approach falls apart
There are scenarios where a standard salary calculator simply cannot give you a reliable answer. If you have self-employment income alongside your W-2 job, the calculator can't account for the self-employment tax of 15.3% on top of regular income tax. If you're an independent contractor earning $25 an hour through a platform, you're responsible for quarterly estimated taxes and the full FICA amount, which changes the picture entirely. Freelancers at that rate should expect to set aside roughly 30% to 35% for taxes rather than the 15% to 20% a W-2 employee would typically see withheld. Another hard limit is anything involving equity compensation, overtime, or bonus structures. The $25 per hour figure assumes straight time at a flat rate. Actual compensation that includes shifts into overtime, shift differentials, commissions, or stock options requires a payroll system that understands those variables, not a generic calculator.
The practical takeaway
Use the basic formula to get your anchor number: $52,000 gross from $25 an hour. Then refine it by running your actual situation through a dedicated withholding estimator that accounts for your specific filing status, state, city, and any pre-tax deductions you're enrolled in. The result will be closer to reality than any generic calculator can provide, and it will save you from the awkward conversation with your accountant about why your withholdings have been consistently off by a few hundred dollars each quarter.