Why most salary calculators are garbage
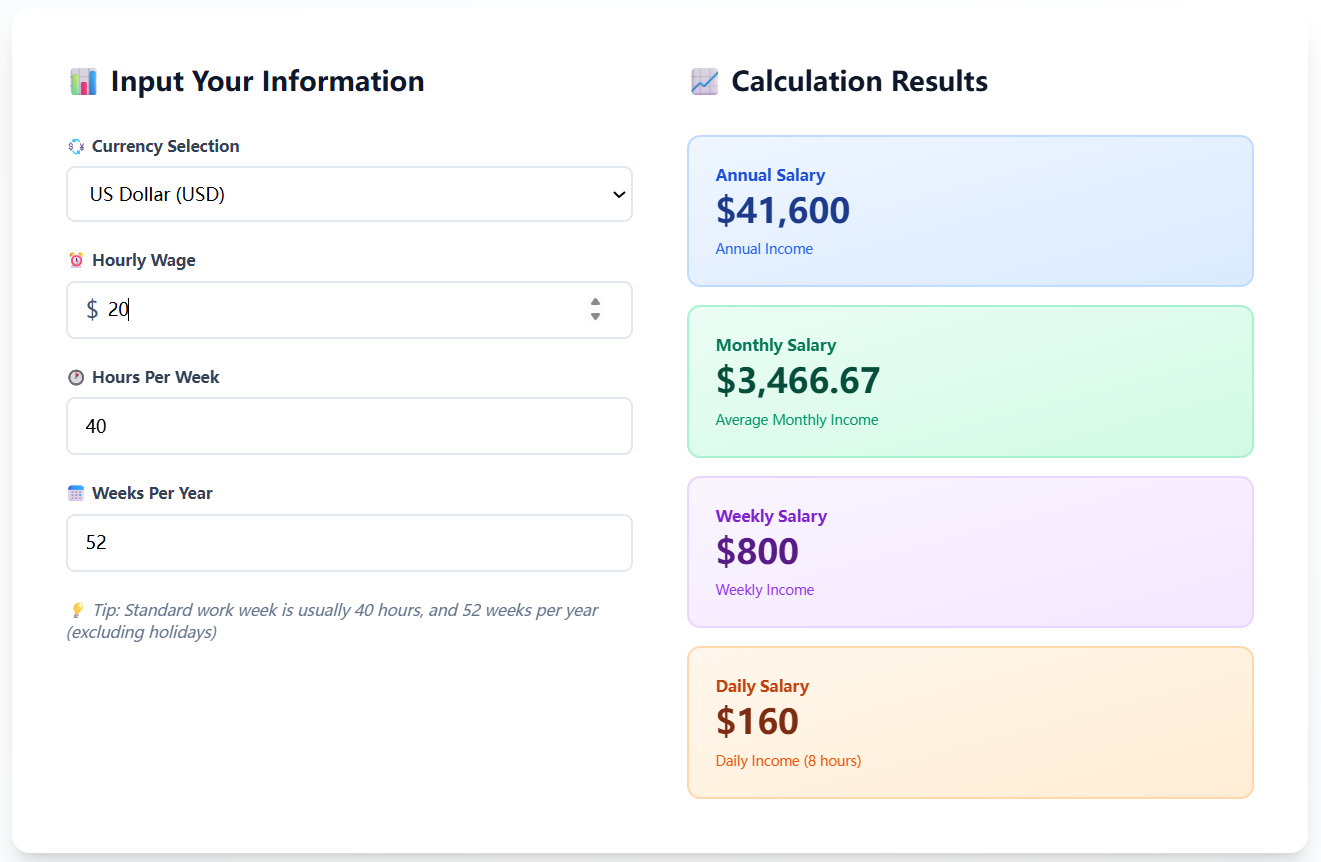
I spent about six months building one properly after watching too many people use free online tools that returned numbers wildly off from reality. The problem isn't that the math is hard. It's that almost nobody inputs the right variables and then compounds errors by ignoring regional tax brackets, benefit deductions, and pre-tax contributions that shift what actually lands in a bank account. The calculators you find on random blogs pull from a single flat tax rate and pretend benefits don't exist. Your gross salary might look impressive on paper, but the final assessment number matters more, and that's where things get messy fast.
The Ultimate Salary Calculator Cracking The Code To Accurate Income Assessments
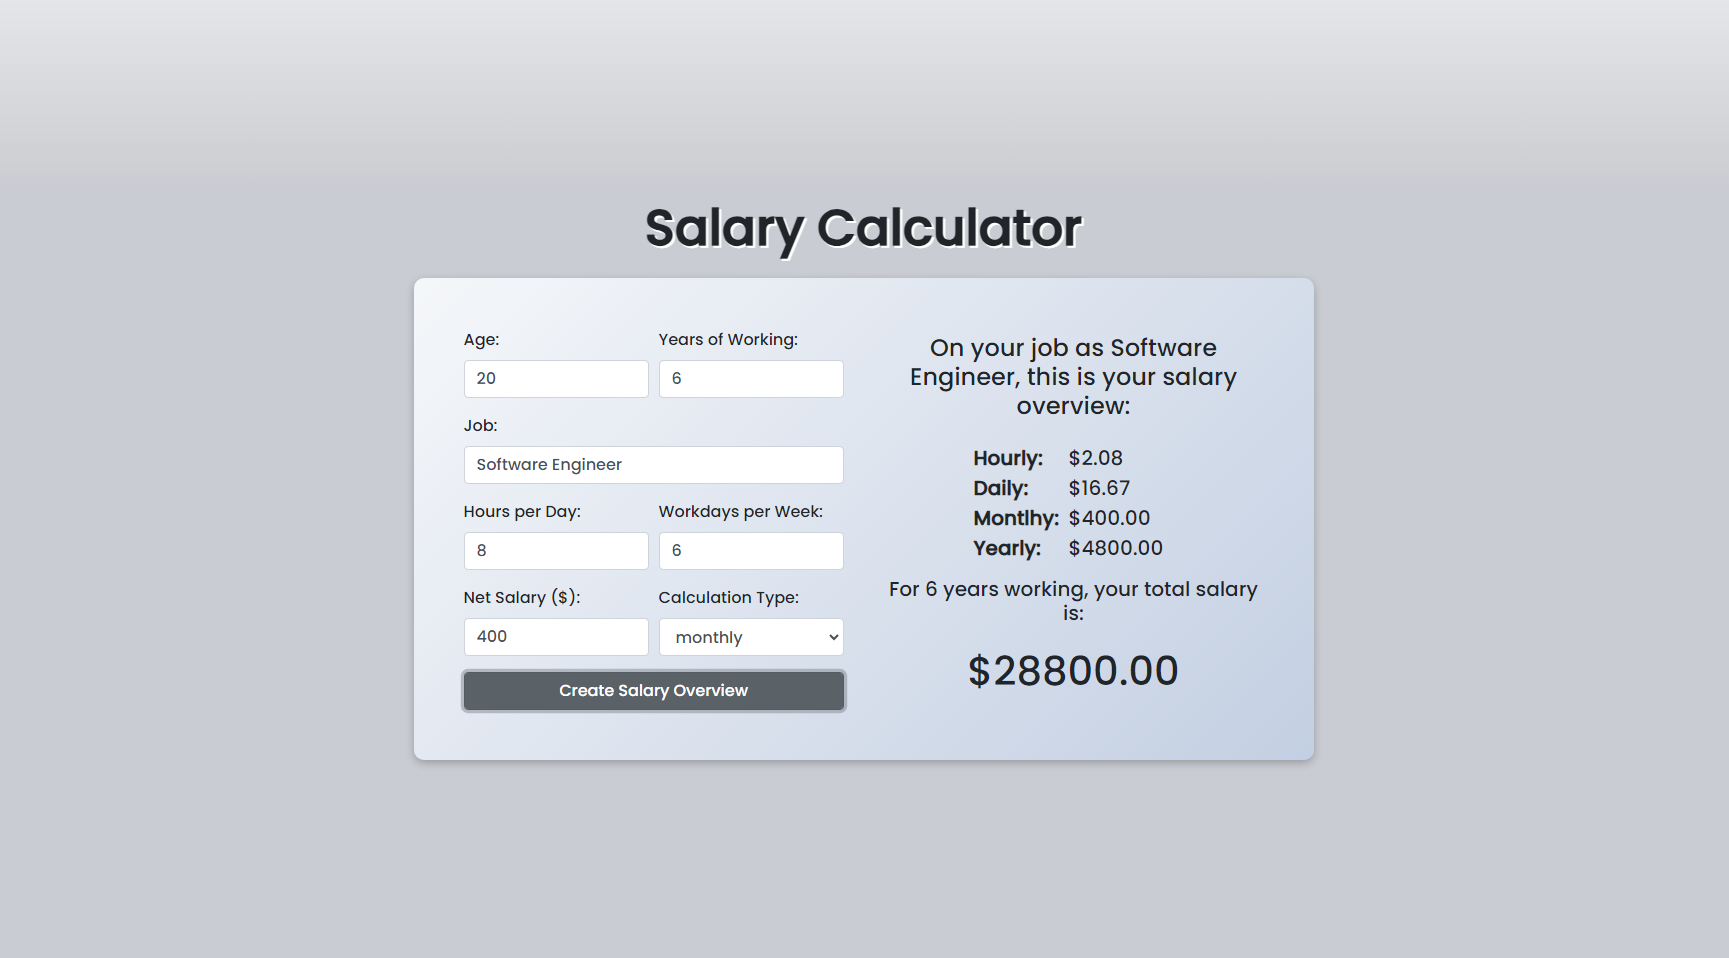
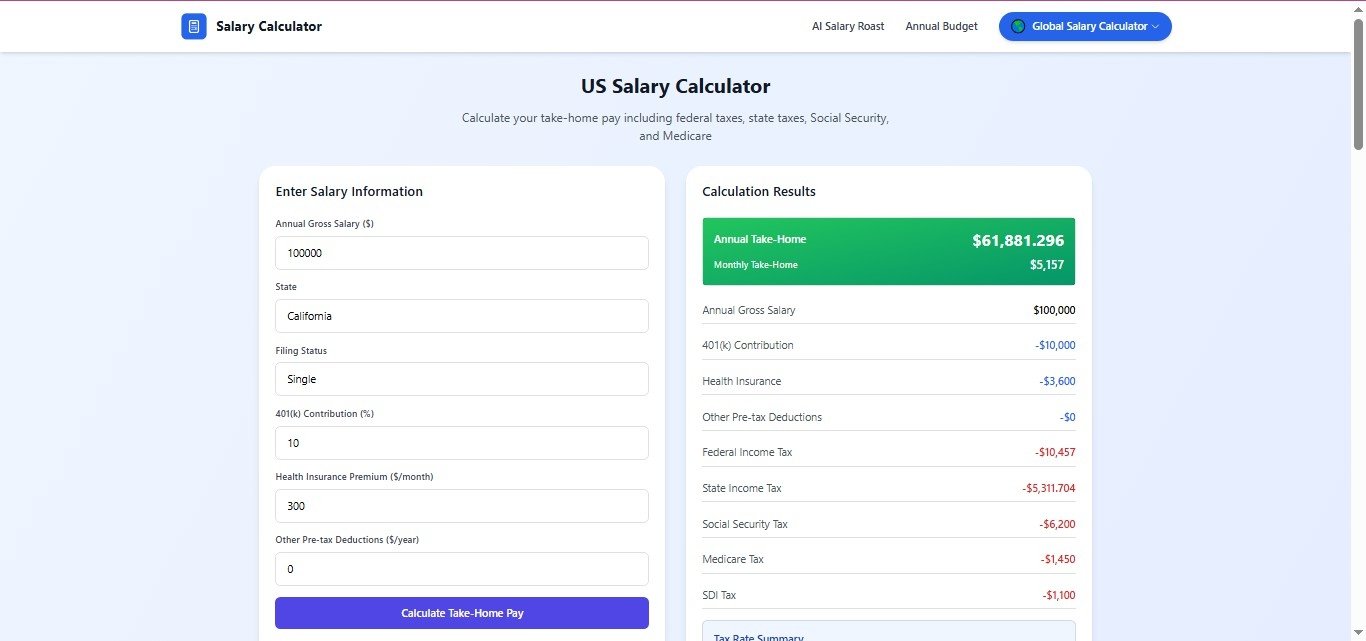
Here's what I actually built and what it does differently. The calculator takes a base salary and runs it through a variable stack: federal tax brackets, state or provincial rates, FICA or equivalent social security contributions, pre-tax retirement deferrals, health insurance premiums paid through payroll, voluntary deductions, and then applies the correct tax treatment to each. It spits out a net monthly figure with a full breakdown. I wrote it in Python using pandas for the bracket calculations, with a JSON file holding current tax tables updated quarterly. For the user side, I kept it as a simple web form. Input fields for gross annual salary, filing status, state, 401k percentage, health insurance cost, and any extra pre-tax deductions. The backend returns a table showing gross, total deductions, net, and effective tax rate. One edge case that nearly broke the initial build: dual-income households where one spouse maxes out a 401k and the other doesn't contribute at all, but they file jointly. The standard deduction changes, and the bracket thresholds shift based on filing status, not just income level. If you calculate each spouse separately and then combine, you get the wrong number. I had to restructure the logic to run joint calculations first, then split the net between the two if needed. Took me three days to fix because the original code treated every row as an independent single filer.
How to use this properly
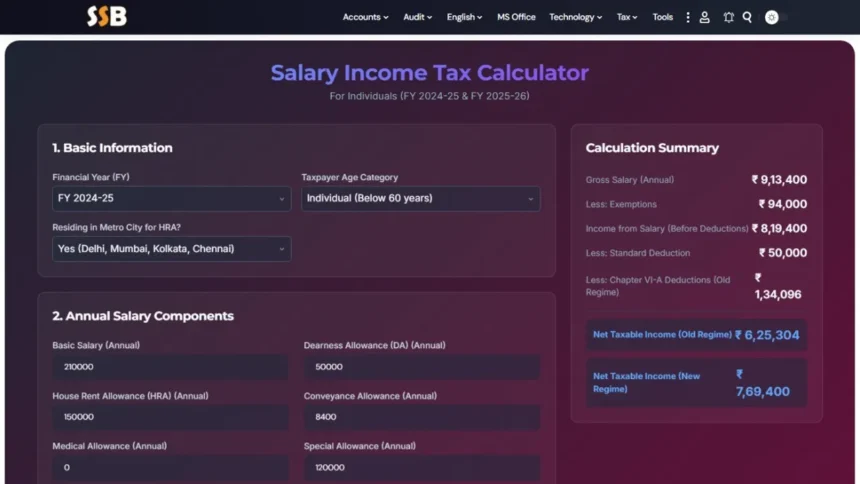
Get the exact gross annual amount before any deductions. Payroll processors sometimes list a different number on stubs depending on pay frequency, so verify against your offer letter or W-2, not your direct deposit. Enter your filing status correctly. Married filing jointly versus married filing separately can change your effective rate by a full percentage point or more in certain bracket transitions. Most people just pick the default and move on, which is why their calculator results feel off. Include every pre-tax deduction you have. Roth 401k goes after tax, traditional 401k goes before. Confusing the two is extremely common and throws the entire calculation off. Same with HSA contributions and flexible spending accounts. These reduce your taxable income, not your gross pay.
Get the Full Details
Don't forget local taxes if you live in a city or county with earned income tax. Pittsburgh, New York City, and Columbus all have municipal taxes that most national calculators ignore entirely.
What this won't do for you
It won't predict your exact take-home on payday. That depends on bonuses, overtime, stock options, and whether your employer uses a retroactive tax method that recalculates mid-year. It also doesn't handle self-employment income or gig work without additional modules, because self-employment tax is a completely separate beast. If you're a contractor or freelancing, use a different tool. This is built for W-2 employees with standard payroll setups. Running freelance income through this will underestimate your actual tax liability by roughly 15 to 20 percent because it skips the self-employment tax calculation entirely. The calculator also assumes you're not in a special bracket situation like AMT, Kiddie tax, or high-income phase-outs on itemized deductions. Those require manual adjustments and aren't worth automating for most users anyway.
A counter-intuitive thing most people miss
Raising your 401k contribution from 5 percent to 10 percent doesn't always save you money in the short term the way people expect. If you're near a bracket threshold, the extra pre-tax deduction drops your taxable income enough to push you into a lower bracket, which sounds good, but the state tax calculation in some jurisdictions doesn't mirror the federal bracket shift exactly. You might see a smaller state tax break than expected, making the net benefit slightly less than your mental math suggests. Not a huge difference, but noticeable if you're trying to decide between increasing retirement savings versus directing that cash toward taxable investments. Another thing: people treat the effective tax rate as a fixed number. It's not. It changes every time you adjust deductions, filing status, or income level. A tool that gives you one static rate and never updates it when you change inputs is essentially useless for planning purposes.
Where to get it
I published the source code and the compiled web version on GitHub under an MIT license. The link is in the repo description. The live version is hosted on a small VPS, so if it goes down, check back. I'm not paying for enterprise hosting, just running a basic Node.js server with a SQLite backend for saved calculations. Your data stays on your machine unless you choose to upload a JSON export, and even then it's stored locally, not sent to any third party. If you want the desktop version instead of the browser tool, there's an Electron build in the releases folder. It's heavier but works offline once installed.
Final notes on accuracy
The tax tables are current through the 2026 filing year. I update them whenever the IRS or relevant state agencies publish changes. If you're calculating for a future year that hasn't been announced yet, you'll need to manually adjust the bracket thresholds using the inflation multiplier the IRS publishes each October. For most people, this calculator gets you within a few dollars of your actual take-home per paycheck when everything is entered correctly. If you're more than five percent off after double-checking your inputs, the issue is usually an omitted local tax or a misclassified deduction, not a bug in the calculator itself.