Figure out what you're actually bringing home from each paycheck
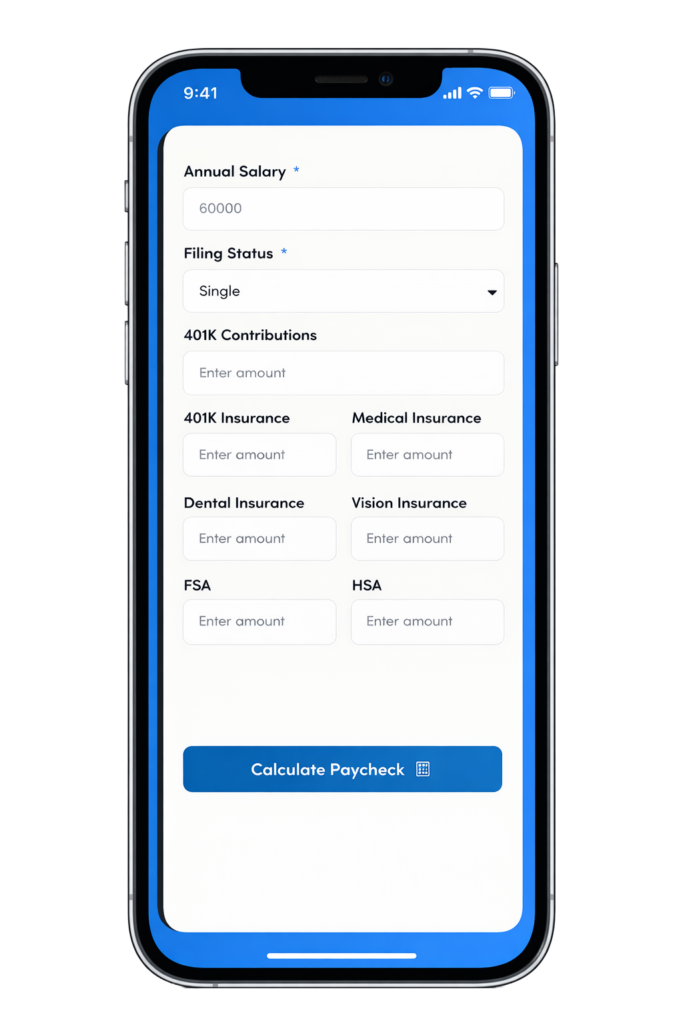
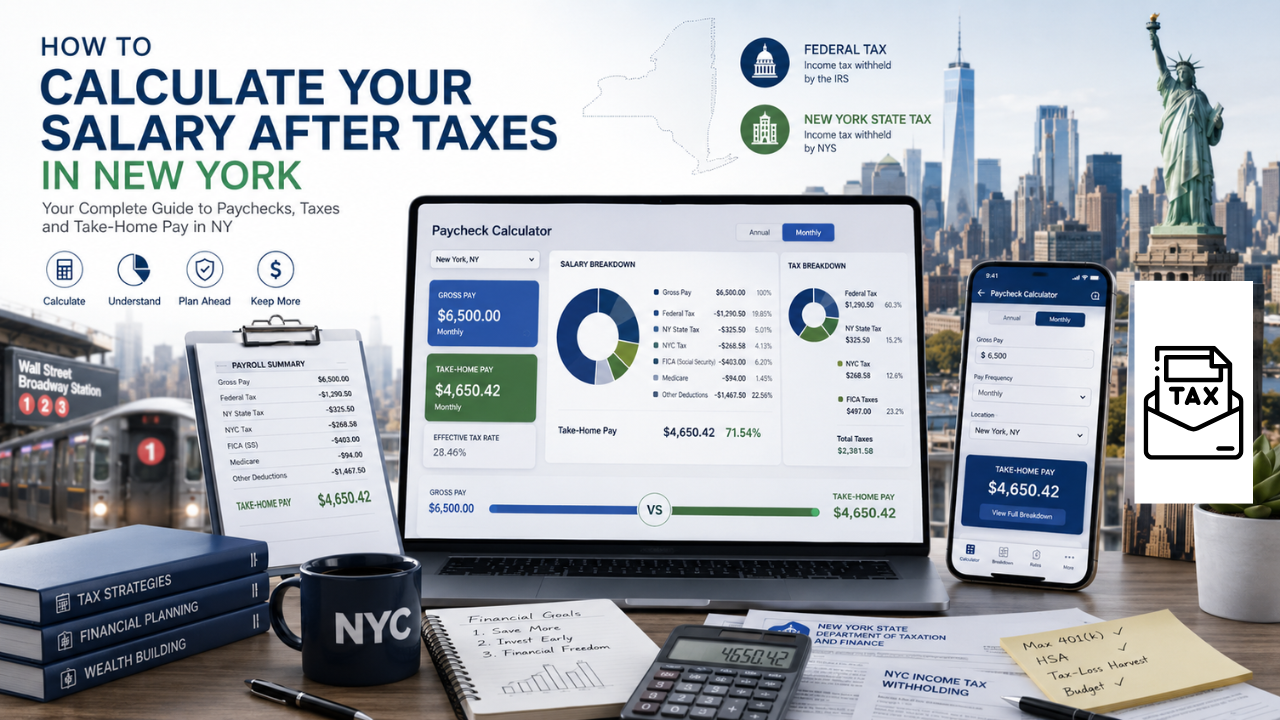
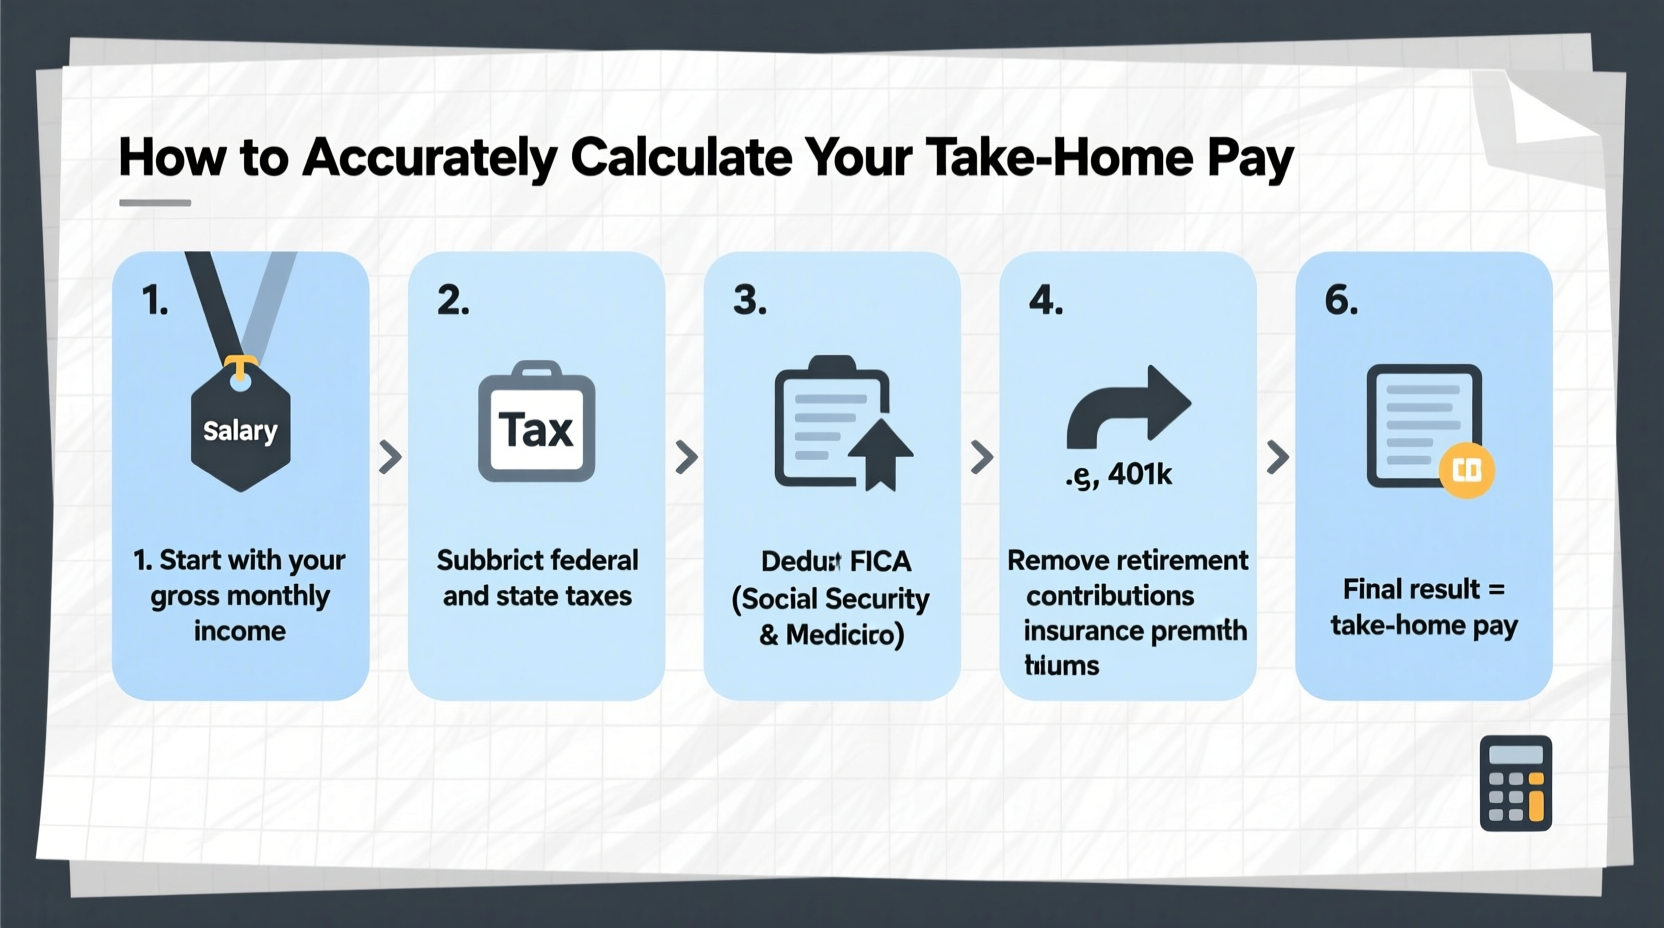
Most people in New York City look at their gross salary, do a quick mental division by twelve, and have no idea where the money went. I've been running payroll for companies across multiple jurisdictions for over a decade, and the single biggest source of confusion I see is around how much New York actually takes out before it hits your bank account. Let's walk through the mechanics of this. The calculator itself isn't rocket science, but the inputs matter a lot more than most people realize. You need your annual gross salary, your filing status, your pre-tax deductions like 401k contributions or HSA payments, and whether you're a city resident or a non-resident working in Manhattan. Those last two variables change everything. Here's the basic flow: federal income tax gets pulled first using your W-4 elections and the standard withholding tables. Then FICA kicks in at 7.65%—that's Social Security at 6.2% and Medicare at 1.45%. After that comes the New York state tax, which uses its own graduated brackets and withholding tables separate from the federal ones. And finally, if you live inside the city limits, the New York City resident tax hits you on top of everything else at rates ranging from about 1.5% to 3.88% depending on your income level. Non-residents who work in NYC still owe the city tax, but only on income earned within the city, and the calculation works differently.
I ran into a real headache last year with a contractor who was working remotely from New Jersey but had his payroll processed through a New York entity. He was getting hit with NYC resident tax on his full salary because the payroll software defaulted to treating him as a city resident. What actually applied was the non-resident rule, which meant the city tax was prorated based on where he physically worked. The fix was to manually override his withholding code in the payroll system and make sure his W-4 had the correct multi-state designation. Took about twenty minutes, but his pay stubs were wrong for three consecutive periods until we caught it.
Working through a concrete example
Take someone making $85,000 a year as a NYC resident, filing single with no dependents, contributing 5% to a 401k, and nothing else pre-tax. That's $70,780 in taxable income after the deduction. Federal withholding lands around $9,800 annually depending on the exact paycheck frequency. New York state tax comes out to roughly $3,900. The NYC tax portion is about $1,850. FICA is $5,414.55. Your annual take-home would be approximately $64,835, which breaks down to about $5,403 per month before any post-tax deductions like health insurance premiums or wage garnishments. Now compare that to someone at the same salary who lives in Brooklyn but works in Westchester. The NYC resident tax disappears entirely. The New York state tax stays the same. Federal and FICA don't change. That person keeps roughly $1,850 more per year, all because of where they live, not where they earn.
Get the Full Details
Common mistakes that bleed money
The biggest issue I see is people ignoring the Additional Medicare Tax. Once your wages exceed $200,000 in a calendar year, there's an extra 0.9% Medicare tax that the employer is supposed to withhold. It's not automatic in every system, and if your payroll processor doesn't flag it, you'll be under-withheld and owe it come April. The same goes for the NIIT—Net Investment Income Tax—which triggers at modified AGI thresholds of $200,000 for singles and $250,000 for married filing jointly. Neither of those shows up on your pay stub. They only surface when you file your return. Another thing people consistently mess up is the NYC school tax. It's separate from the municipal income tax and applies to residents and non-residents who work in the city. The rate is 0.33% on income up to $170,000 for single filers, then it phases out completely once you cross certain income levels. I've seen seasoned employees get confused when they see it on their stub and assume it's another layer of city tax when it's actually a separate line item with its own phase-out rules.
What these calculators can't do for you
Be honest about the limitations. A paycheck calculator will give you a solid estimate, but it cannot account for every variable that affects your actual take-home. Things like variable overtime hours, commission structures that push you into different tax brackets mid-year, bonus withholding rates that differ from regular wages, employer-specific benefit deductions that vary by plan, and any local taxes from towns or villages within New York State that have their own income tax overlays. The calculator gives you a baseline. If your compensation has any of those moving parts, your real take-home will diverge from the estimate, sometimes significantly. For anything beyond a straight salary with standard deductions, the most reliable approach is pulling your actual pay stubs from the last quarter, entering those real numbers into a spreadsheet, and working backward from what was actually withheld. That gives you the true effective rate, which is what matters when you're budgeting or making financial decisions. A calculator is fine for rough planning. Pay stubs are what tells you the truth.