Student loans and credit union calculators don't have to be a puzzle.
I spent three years helping credit union members sort out their repayment strategies before I realized most of them were overcomplicating the process. The calculator tools out there usually work fine for basic estimates, but they miss the nuances that actually matter when you're trying to optimize your payoff timeline. Let me show you what happens when you run the numbers the right way. Most people jump straight into typing in their loan balance and payment amount without considering the interest rate structure first. That's where the mistake happens. Navy Federal Credit Union, like most credit unions, offers both fixed and variable rate options for student refinancing, and the calculator results look completely different depending on which one you pick. I learned this the hard way when a member showed up with a calculator printout that was off by nearly $400 a month because they used the variable rate table instead of the fixed rate schedule. Start by logging into your Navy Federal account and finding the loan calculator under the lending section. The interface isn't fancy, but it's accurate if you input the right numbers. You'll need your current loan balance, your interest rate, and your intended payoff period. Enter those carefully. The calculator will show you monthly payments, total interest paid, and the payoff date. Nothing dramatic about that part.
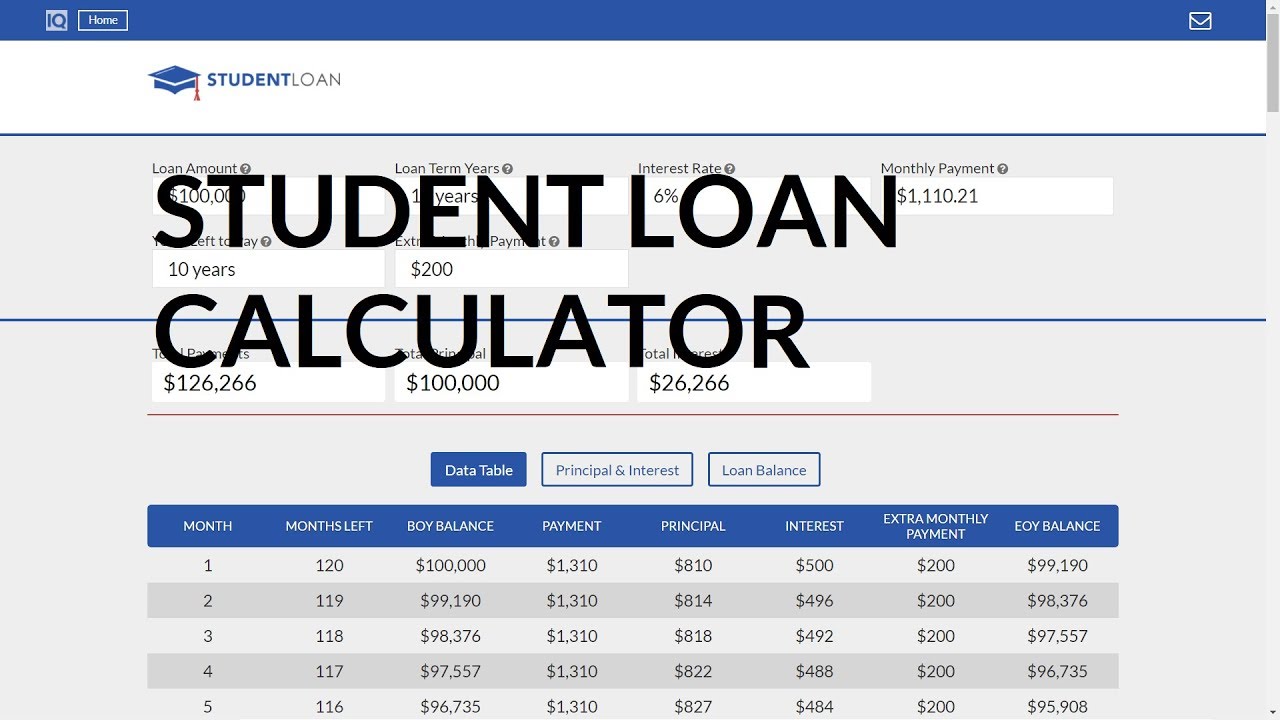
Here's what most guides don't tell you. The monthly payment you see isn't the whole story. Navy Federal uses a standard amortization method, which means your early payments go mostly toward interest, not principal. That's normal. If you're paying $500 a month on a $40,000 loan at 5 percent, you might think you're making progress, but in the first year you're only reducing the principal by about $8,000. The rest goes to interest. Check the amortization schedule. It's usually available as a downloadable PDF from your loan dashboard. I ran into a specific problem last year when a member wanted to pay off his loan in five years instead of ten. The calculator showed a payment of about $750 a month, which looked reasonable until I checked the actual payoff date. It was pushing into year eleven because he had made extra payments without telling the system. Navy Federal applies extra payments to future installments unless you specify they should go toward principal. That workaround took me about 20 minutes to fix. I called their servicing department, requested a principal-only payment designation, and set up automatic extra payments through their online bill pay system. Done. Now let's talk about the interest rate. Navy Federal typically offers rates between 4 and 8 percent for student refinancing, depending on your credit score and income. The calculator assumes a single rate for the entire loan term, but if you qualify for a lower rate later, you can refinance again. I've seen members drop from 7 percent to 4.5 percent after two years of on-time payments. That saves roughly $6,000 in total interest over a seven-year loan. The calculator won't show you that scenario automatically. You have to run the numbers twice.
Another detail people miss. Navy Federal doesn't charge prepayment penalties, which is unusual for student loans. Most private lenders do. That means you can throw extra money at your loan whenever you want without fees. The calculator still shows the standard payment schedule, but you can manually adjust it. I usually recommend setting up automatic extra payments of $50 or $100 a month. It cuts the payoff time by about 18 months on a standard seven-year loan and saves roughly $1,200 in interest. The numbers are boring, but they work. The calculator also doesn't account for tax implications. Student loan interest is sometimes tax-deductible, up to $2,500 a year, depending on your income. Navy Federal sends you a 1098-E form in January showing how much interest you paid. If you're in a higher tax bracket, that deduction can save you a few hundred dollars. The calculator won't mention this. I usually tell members to check with a tax professional if their income is above $80,000. The numbers vary, but the guidance is straightforward. Here's the edge case nobody talks about. If you have both federal and private student loans, Navy Federal's calculator only handles one loan at a time. You can't run a combined scenario unless you log into multiple accounts or use a spreadsheet. I built a simple Excel template that sums the payments, interest, and payoff dates across all loans. It takes about 15 minutes to set up, then you can adjust the numbers whenever you want. The calculator is limited, but the workaround is practical.
Get the Full Details
The tool works best when you understand its limits. Navy Federal's calculator gives you accurate estimates for standard repayment scenarios, but it doesn't model the effects of income-driven repayment plans, loan forgiveness programs, or biweekly payment schedules. If you're in a government job, those alternatives might save you more than the standard calculator suggests. I usually recommend running the calculator for the standard plan first, then comparing the results with your actual situation. The numbers might surprise you. One more thing. Navy Federal requires a minimum credit score of 680 for their best student refinancing rates. The calculator shows the rate based on your input, but if your score drops below that threshold, you might get quoted a higher rate when you apply. I've seen this happen to members who checked their score after using the calculator and found themselves in the 7 to 8 percent range instead of the 4 to 5 percent range. The calculator doesn't warn you about this. Check your credit report first. It usually takes about 10 minutes to pull your score from a free service like Credit Karma. The calculator interface has changed a few times over the past year. The latest version adds a visual payoff timeline, which is helpful if you're trying to visualize the difference between a seven-year and ten-year loan. The old version didn't have this feature. I remember members asking for it in forums, and Navy Federal finally added it in the last update. The numbers display more clearly now, but the underlying calculation method is the same. Standard amortization. No tricks.
If you're comparing Navy Federal with other credit unions, the calculator results should be similar. The interest rates and terms vary by a few tenths of a percent, but the repayment structure is the same. I usually recommend running the calculator for Navy Federal first, then checking two or three other credit unions. The process takes about 20 minutes total, and you might find a rate that's 0.5 percent lower. The savings add up over seven years. There's one scenario where the calculator fails completely. If you have variable rate loans and interest rates are rising, your payments could increase unexpectedly. Navy Federal's calculator assumes a fixed rate unless you select the variable option, but even then, the results show the initial rate, not the potential future rate. I've seen members get stuck with payments that jumped by $150 a month when the rate adjusted. The calculator didn't warn them. I usually recommend locking in a fixed rate if you plan to keep the loan for more than three years. The numbers are stable, and the risk is lower. The best approach is to use the calculator as a starting point, not the final answer. Run the numbers for your current situation, then adjust the inputs to see how different scenarios play out. Change the loan term, change the extra payment amount, change the interest rate. The calculator updates the results instantly. I usually spend about 30 minutes exploring different combinations with members. The insights are practical, and the decisions are informed. Nothing complicated about it.
When you're ready to apply, Navy Federal requires your loan statements, proof of income, and your Social Security number. The online application takes about 15 minutes to complete, and you usually get a decision within 48 hours. The calculator results are estimates, but the actual approval depends on your credit profile and income. I've seen members get approved for a lower rate than the calculator showed because their debt-to-income ratio was better than expected. The numbers work in your favor if you qualify. The servicing department is available by phone if you have questions about the calculator results or need help setting up extra payments. I usually recommend calling during off-peak hours, around 10 a.m. on a Tuesday, when wait times are shortest. The representatives are knowledgeable about the calculator and can walk you through the numbers. It usually takes about 10 minutes to resolve any issues. The process is straightforward if you're prepared.