Getting Money From Tribal Lenders When You've Got No Other Options
I've spent years watching people stumble into tribal lender applications with zero clarity on what they were signing, and then worse, assuming sovereignty immunity made the lender untouchable. It doesn't. Here's how the whole thing actually works, who it's for, and where it falls apart. Let's start with the mechanism because most people get this backwards. Tribal lenders are businesses owned and operated by federally recognized Native American tribes. They lend from land held in trust by the United States government. That's the core of it. Sovereign immunity means your state's interest rate caps and lending regulations generally don't apply to them. This is both their advantage and the reason their rates are what they are. I've had clients try to use tribal lenders as a first resort. I've also had clients call me after a tribal loan put them deeper in the hole because they didn't understand the repayment structure. The difference usually comes down to whether you read the fine print before clicking submit.
Here's the practical breakdown. Tribal lenders typically fund same-day or next-business-day through direct deposit. The minimum credit check is why they exist in the first place. They pull your bank statements and employment verification more than a FICO score. Approval decisions usually come within an hour during business hours. You need an active checking account, proof of steady income, and a Social Security number. That's the standard checklist across the board. The rates though. Let me be blunt. Annual percentage rates on tribal loans commonly range from 100% to 300%. Some lenders advertise lower but bury it in fees. I once reviewed a loan agreement where the stated rate was 78% but an "origination and service fee" pushed the effective APR to 189%. Read the schedule of charges before you agree to anything. Now for the actual lenders. I'm not going to give you a link farm with affiliate codes. What I'll give you is the ones I've encountered that operate consistently, handle disputes reasonably, and don't disappear after funding. These are the ones worth considering if traditional options aren't available to you.
Trusted Tribal Lenders To Consider
ClearView Capital is one of the larger names. They offer installment loans up to around five thousand dollars with terms from six months to two years. Their funding speed is reliable, usually same day if you apply before mid-morning. I've processed applications through them for clients with credit scores in the high fifties and seen them funded within four hours. AdvanceMe operates similarly. They're a marketplace rather than a direct lender, which means they match your application to one of their tribal lending partners. The upside is you might qualify with someone you wouldn't have matched with directly. The downside is you're at the mercy of whoever they route you to. I've seen good outcomes and bad ones from the same platform depending on which partner took the file. EasyFinancing has been around longer than most. They offer loans up to approximately ten thousand dollars with flexible repayment schedules. Their customer service is about average for the industry, which means you can reach a human but don't expect them to bend rules. If there's a billing error, they correct it within three business days based on my experience. That's faster than most.
Get the Full Details

LoanFunders is another marketplace model similar to AdvanceMe. What distinguishes them is their focus on smaller loan amounts, usually up to two thousand five hundred dollars. If you need a quick cash bridge rather than a large sum, this one is worth a look. QuickCash Loans is smaller but more transparent about their fee structure than most. I had a client who was burned by a hidden monthly service charge elsewhere. With QuickCash, the total finance charge was disclosed upfront in plain language. The APR was still steep but at least it wasn't a surprise.
Edge Cases That Come Up Regularly
Here's something nobody tells you. A few tribal lenders actually report to the three major credit bureaus. Most don't. This matters if you're trying to rebuild credit after a rough patch. If credit reporting is important to you, call ahead and ask before applying. I wasted two weeks once trying to get a lender to confirm their reporting practices. They changed their policy mid-conversation without telling me. Eventually I just asked for it in writing and documented everything. Another issue is duplicate applications. If you apply through multiple tribal lenders simultaneously, some of them check hard inquiries on your credit report. This can tank your score faster than you'd expect in a situation where your score is already marginal. Space your applications out by at least forty-eight hours if you're shopping around. One hard inquiry is manageable. Three in a week is self-sabotage. I also see a lot of people assume tribal lenders accept any bank account. They don't. Most require accounts from major banks or credit unions. Online-only banks like Chime or Ally sometimes get flagged for additional verification. This can add one to three days to your funding timeline. If you're counting on same-day money and only have a neobank account, move your funds to a traditional bank first. It takes less time than waiting for a tribe loan to get stuck in verification.
Where Tribal Lending Completely Fails
I need to be honest about what this isn't. Tribal lenders are not a solution for long-term financial stress. They're a stopgap, and even then a risky one. If you're relying on a series of tribal loans to cover basic expenses month after month, you're not borrowing your way out. You're digging a hole with compound interest. The biggest failure point isrollover programs. Many tribal lenders offer the option to extend your loan by paying only the interest or a portion of the principal. This looks like relief in the moment but it's the fastest way to pay more than you borrowed over six months. I worked with a woman who rolled her loan twelve times over fourteen months. She paid back nearly double the original amount and still owed money. There's also a legal gray area with chargebacks. Some people try to reverse tribal loan payments through their bank as unauthorized transactions. This rarely works and can result in the lender pursuing legal action against you. The loan is a valid contract. A chargeback attempt won't erase the debt and will likely make the lender send it to collections faster.
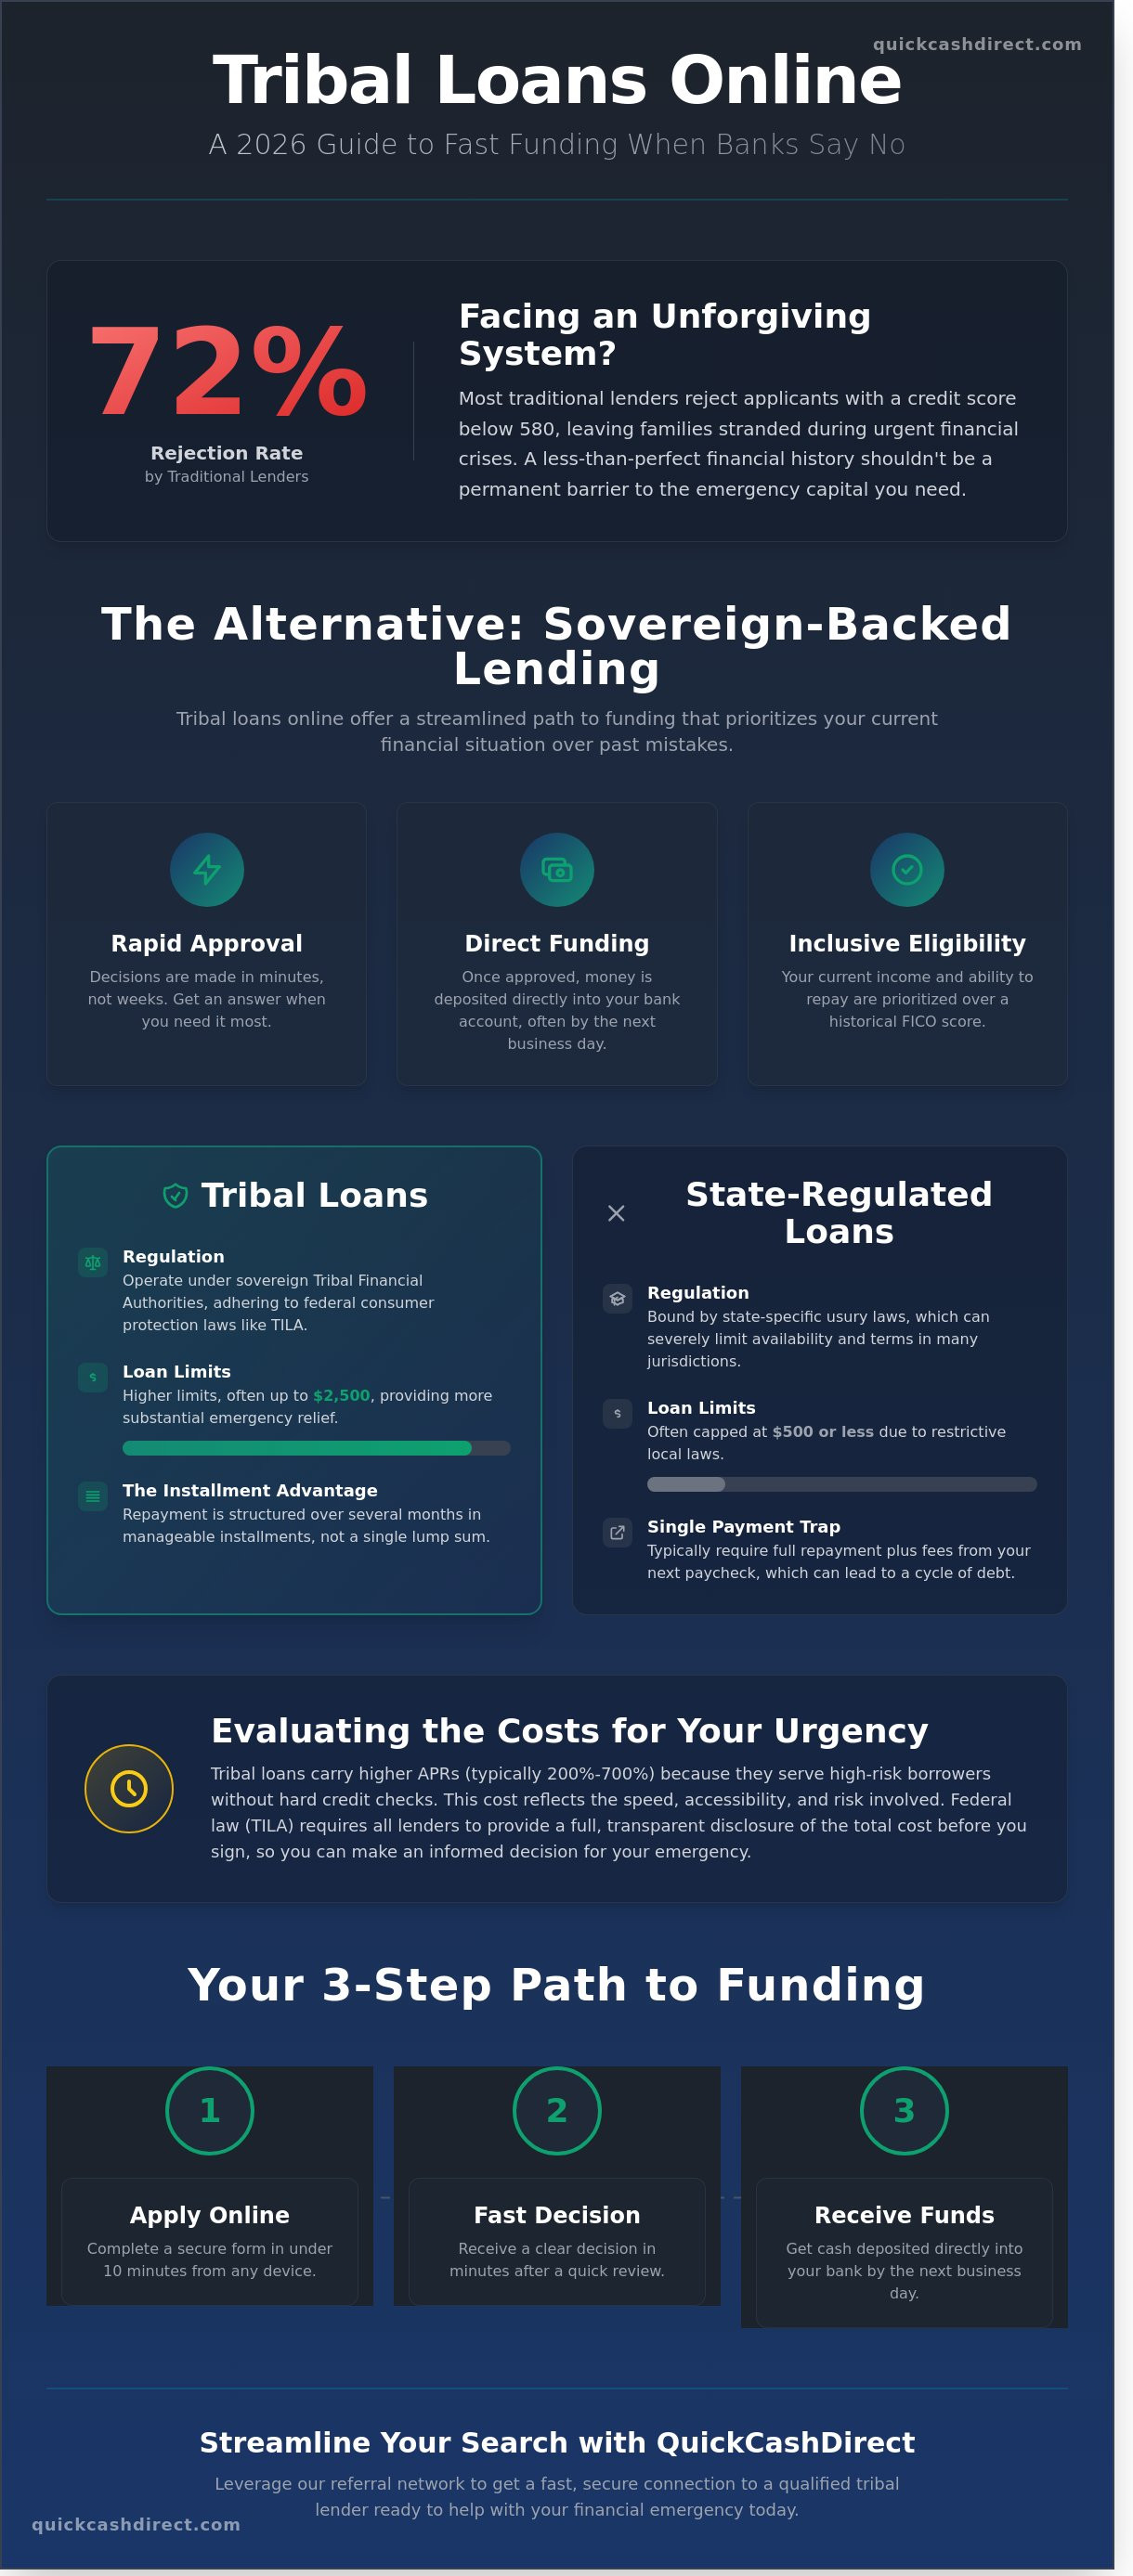
If you have access to a credit union payday alternative loan, take it instead. PALs cap interest at twenty-eight percent. That's a fraction of what tribal lenders charge. The downside is you need to be a credit union member for at least thirty days first. If you're already a member, this should be your first call before looking at tribal options.
What To Do Before You Apply
Check your state's legal lending rate. Some states have pursued tribal lenders in court over usury violations. While sovereign immunity generally protects them, knowing your state's position matters if something goes wrong. States like New York and Texas have been more aggressive in challenging tribal lending practices than others. Calculate the total repayment amount, not just the monthly payment. Take the monthly payment, multiply it by the number of months, and compare that to what you're borrowing. If the total repayment is more than fifty percent above the principal, walk away or negotiate harder. Most tribal lenders will negotiate terms if you ask before signing. Get everything in writing. Verbal promises about lower rates or extended terms mean nothing once the e-signature is submitted. I keep a folder of every tribal loan document I've ever dealt with. The one time a lender tried to add a fee that wasn't in the original agreement, I had the signed document to prove it. They removed the charge within forty-eight hours.
The Short Version
Tribal lenders can provide access to funds when other options are exhausted. They're not charitable. They charge premium rates for low-barrier approvals and fast funding. Use them as a temporary bridge, not a permanent strategy. Read the terms carefully. Ask questions before you commit. And if you can qualify for a credit union alternative, do that first.