Understanding Gross Income From Actual Experience
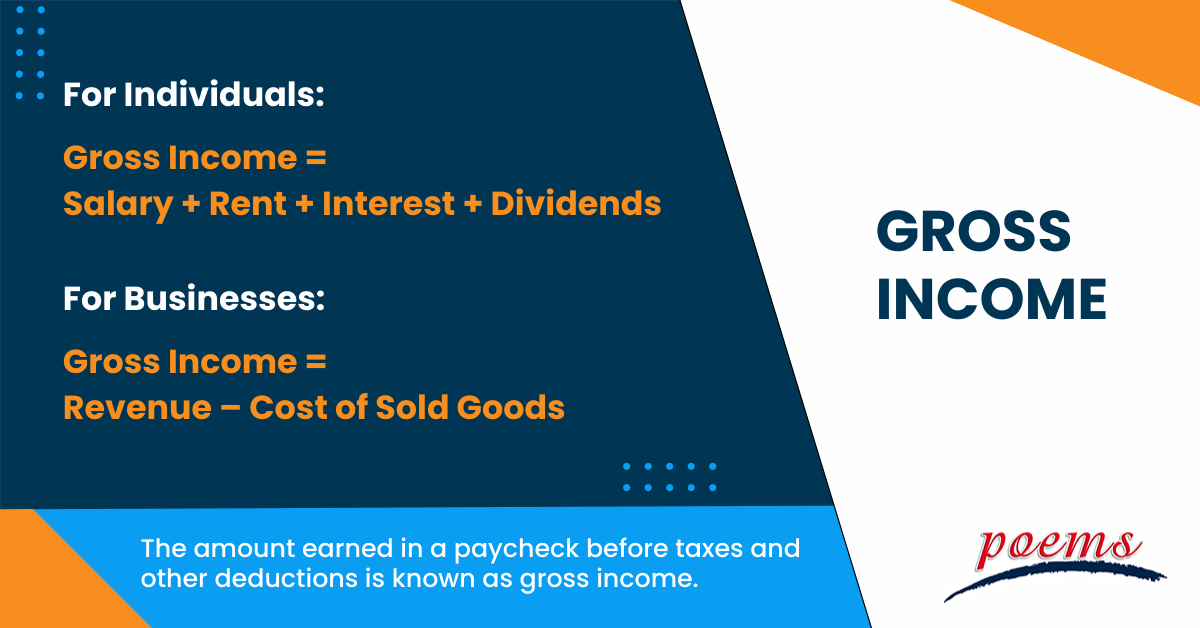
Most people confuse gross income with net income or with their take-home pay. I spent years doing payroll calculations before realizing how many individuals and small business owners get tripped up by this distinction, and it still surprises me how often that confusion leads to real financial headaches later on. Let me walk through the mechanics without oversimplifying things. Gross income is the total money you earned before any deductions, taxes, or contributions are removed from your paycheck. That is the complete amount sitting at the top of your pay stub or business revenue statement. For a W-2 employee, this number appears in Box 1 of the W-2 form, though there is a critical distinction between Box 1 gross wages and Box 3 wages subject to Social Security tax, which can differ if you have pre-tax contributions like a 401(k) or health insurance premiums. For freelancers and business owners, gross income means total revenue from all sources before subtracting any business expenses or cost of goods sold. Let me be direct about a common calculation error I see repeatedly. People often add their net pay and their taxes and forget to include employer-paid benefits, stock options, or non-cash compensation in their gross income total. If you receive a company car, health insurance paid by your employer, or matched retirement contributions, those values may or may not be part of your taxable gross depending on the benefit type, but they are absolutely part of your total compensation picture. The IRS requires these to be reported on your W-2 in Boxes 12 and 15a through specific codes, and missing them skews your actual gross income downward.
I dealt with a specific edge case recently involving a contractor who was classified as a 1099 independent worker but received expense reimbursements directly from clients. He was calculating his gross income by only adding his invoiced labor charges, completely omitting the reimbursement amounts that his clients paid directly to his credit card for travel and equipment. Those reimbursements, totaling approximately twelve thousand dollars that year, were indeed part of his gross income according to IRS guidelines, and he owed additional self-employment tax on that amount when he filed his return. The workaround was straightforward: I had him pull every single bank deposit from his business account for the year using a quick query in his accounting software, then cross-reference those deposits against his invoiced amounts to identify the gap. That process took about twenty minutes and caught several smaller discrepancies as well. Going forward, he set up his accounting software to flag any deposit that does not match an invoice, which eliminates the guesswork entirely. Here is something that rarely gets explained clearly. Your yearly gross income is not always the same number across different contexts, and that matters significantly when you are applying for loans, calculating child support, or determining eligibility for government assistance programs. A mortgage lender will look at your gross income differently than the IRS will. Lenders typically want to see two full years of documented gross income from tax returns, but they will add back certain non-recurring deductions and sometimes use your most recent pay stubs if they show a higher figure than your tax returns. The IRS simply looks at what you reported on your returns. These discrepancies are normal, but they become problematic when you are using one number to qualify for something while the other number disqualifies you elsewhere. For business owners operating pass-through entities like S corporations or LLCs, the situation gets more complicated. Your gross income includes your share of business profits, but it also interacts with how you structure your own compensation between salary and distributions. Taking a smaller salary and larger distributions can lower your self-employment tax burden, but it creates a lower reported gross income on your personal return. This is a legitimate tax strategy used by many business owners, but it absolutely impacts loan applications and any calculation that relies strictly on gross income figures.
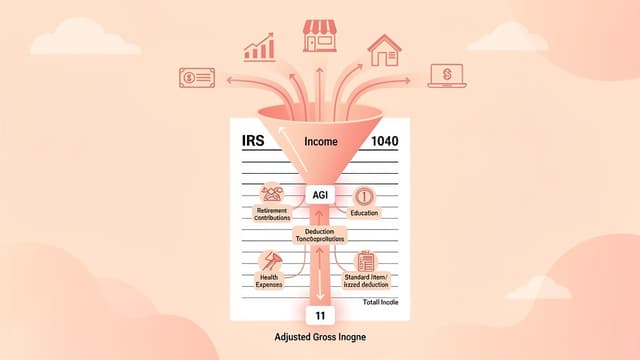
Another practical consideration that people overlook involves foreign income and currency fluctuations. If you earn income in a foreign currency during the tax year, the IRS requires you to convert it to U.S. dollars using the applicable exchange rate for each transaction or an annual average rate if you choose that method consistently. I worked with a consultant who earned income in euros and British pounds throughout the year. She had converted everything at a single average rate for the year, which was acceptable to the IRS, but she needed documentation of her chosen methodology ready for potential audit review. Without that documentation on file, the valuation of her foreign income would have been entirely subjective and potentially incorrect. The calculation itself is usually simple arithmetic, but gathering all the correct source documents is where the real work lies. For employees, start with your W-2 forms. Box 1 gives you your taxable gross wages. Add any taxable fringe benefits, unemployment compensation received, and any other income reported on Schedule 1 of Form 1040. For self-employed individuals, start with your gross receipts or sales from Schedule C, then subtract cost of goods sold if applicable, and add any other income items from Schedule 1. The resulting figure on line 11 of Form 1040 is your total gross income for the year as the IRS sees it. There is a practical limitation to relying solely on gross income as a measure of financial health. It completely ignores your expense structure, debt obligations, and tax bracket. A person earning eighty thousand dollars gross with thirty thousand in business expenses and high medical costs is in a fundamentally different position than someone earning the same gross with minimal expenses. Gross income is useful as a standardized comparison metric, particularly for qualification purposes, but it should never be the only number you consider when evaluating your financial situation. Pair it with your net income and your disposable income after all obligations to get an accurate picture of where you actually stand.
Get the Full Details
Practical Steps For Accurate Calculation
Gathering Your Source Documents
Collect all W-2s, 1099s, K-1s, and any other income statements your payer is required to send you. If you are self-employed, pull your profit and loss statements from your accounting software and reconcile them against your bank and credit card statements. Discrepancies between your records and your actual bank deposits are the most common source of errors, and catching them early prevents problems at filing time. Most people spend about three hours doing this reconciliation properly, but automating the bank feed connection in your accounting software reduces that to roughly twenty minutes on initial setup and minimal ongoing effort. Input all gross income figures into a tax preparation program or spreadsheet. Do not round numbers to neater figures, even if it feels easier. Tax software and the IRS expect exact dollar amounts down to the cent. If you are working with an accountant, provide them with the raw data and let them handle the categorization. Trying to pre-categorize everything yourself often introduces errors that take longer to fix than if you had just passed the unstructured data through in the first place. Keep your documentation organized for at least three years from your filing date, which is the standard statute of limitations for most IRS audits. Digital copies stored in a backed-up cloud folder work fine, but retain the original documents if you receive them on paper. The IRS accepts digital copies, but having the originals protects you in edge cases where image quality or file corruption becomes an issue during review.