How The Home Depot Credit Card Actually Works When You Need It
The Home Depot consumer credit cards come in two main flavors: the regular store card and the Pro X card for contractors and serious DIYers. The store card gets you a special financing offer on purchases over $500, usually 24 months interest-free if you pay it off in time. That's the headline feature, but the real mechanics matter more than the marketing. You apply at the register or online, and approval can be instant or take a few days. When approved, your credit limit is often low at first—maybe $500 to $2,000 unless you have good credit to begin with. The standard APR runs around 26.99%, which is standard for store cards but painful if you miss the promo window. Here's where people screw up: they think the promotional rate means they can carry a balance forever. It doesn't. Miss one payment, and retroactive interest gets applied to the entire original purchase amount. That's not a soft launch penalty, it's a full hit to the original principal plus accrued interest from day one. I learned this the hard way back in 2019 when I put a $3,200 kitchen cabinet order on the card for the 24-month promo. Life happened, a payment got missed by three weeks, and suddenly I owed nearly $400 in retroactive interest on top of what I already paid down. I called customer service, explained the situation, and they did adjust the late fee but not the retroactive interest. The workaround? Set up autopay for at least the minimum amount before the billing cycle closes. That eliminates the single biggest risk factor.
The Pro X card is different and honestly better if you qualify. It offers volume pricing on select items—usually 5-10% off beyond what's already marked down. You get a free Pro toolbox and access to contractor pricing on Lumber and tool rental. The credit terms are the same as the consumer card, but the volume discounts stack in a way that actually matters for people buying materials regularly. I've seen contractors save $600 to $1,200 a year just from the volume pricing alone, which offsets the card's high APR if you're carrying a balance. One thing almost nobody mentions: the Home Depot card does not help your credit score the way a regular credit card does. Most store cards only report to one or two of the three major bureaus, and sometimes not at all unless you carry a balance. If you're using the card primarily to build credit history, you're better off with a secured card from a major bank. The Home Depot card is a financing tool, not a credit-building tool. Another counter-intuitive point: the special financing offer sometimes applies to products that aren't on sale, but it never applies to gift cards, cash advances, or balance transfers from other cards. Home Depot will not let you use the card to pay off debt from another card. The offer is strictly for purchases made at Home Depot locations or on homedepot.com.
If you're doing a big project and the math works, here's the sequence that actually protects you. Get pre-qualified online first so you know your likely limit before you walk into the store. Then negotiate with the sales associate—sometimes they can match or beat competitor pricing even when the card is involved. Put everything eligible for the promo on the card, track the payoff date in your calendar with two reminders (one at 6 months and one at 12 months for the 24-month deal), and pay extra whenever possible. Extra payments go toward principal first, which reduces the total interest if the promo expires before you're clear. The biggest limitation is that the card only works at Home Depot. If you're buying appliances from Lowes or lumber from a local supplier, this card is useless there. For a mixed-project budget, you're better off using a rewards credit card for the non-Home Depot purchases and reserving the store card strictly for the larger, finance-eligible items. That way you're not leaving money on the table with generic rewards cards on purchases where the store card's promo terms actually save you dollars. Also, the credit limit you see when approved might not be enough for your project. A bathroom remodel can easily run $8,000 to $15,000. If your card limit is $3,000, you either split the purchase across multiple transactions (which complicates the financing math) or you pay the difference with another method. Don't assume the approved limit covers your whole job. Check it against your estimate before you start buying.
Get the Full Details
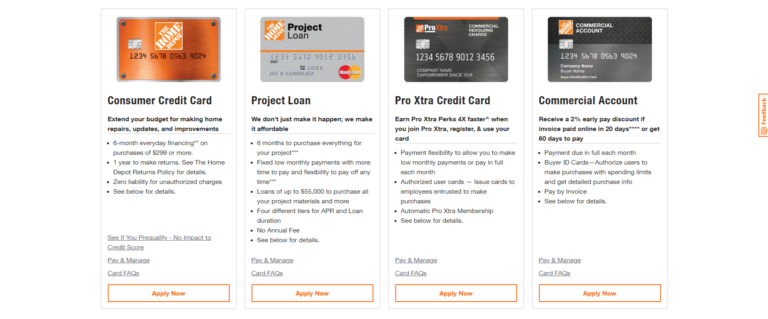
For the Pro X card specifically, the volume pricing requires you to be approved as a Pro customer, which means providing a business license or contractor number. Some people fake this by using a side-hustle LLC they formed for a single project. It works technically but it's fraud if you're not actually running a business. Home Depot does cross-reference Pro accounts sometimes, and they've been known to close accounts and void discounts when they catch it. Don't risk it. Bottom line: the card is useful when you have discipline and a clear payoff plan. It's dangerous when you treat the promotional rate like a free loan. The Pro X card is worth the application if you're buying materials regularly. The consumer card is fine for one-off projects under $5,000 that you can clear within the promo window. Beyond that, look at a personal loan from a credit union, which typically offers lower rates and no retroactive interest traps.


