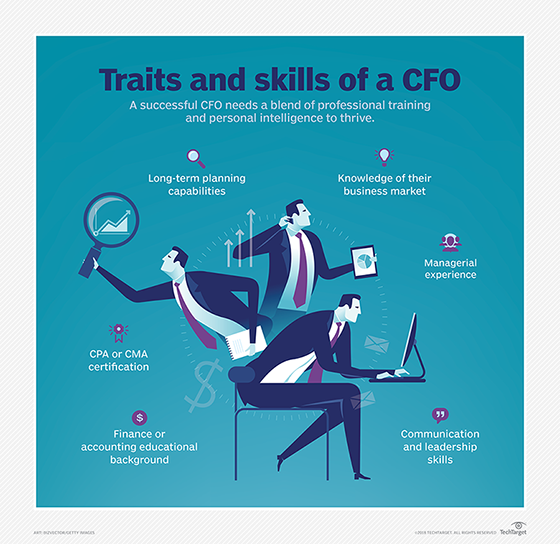
What the CFO role actually looks like on a Tuesday
A lot of people treat the CFO as some distant executive who signs off on big purchases and stares at spreadsheets in a suit. That isn't wrong, but it misses most of what the job takes up. The day-to-day is more about making sure the numbers don't contradict themselves when you're answering three different board questions at once. I spent years working under a CFO who would get visibly frustrated during quarterly reviews not because revenue was down, but because two departments had different definitions of "gross margin" and nobody had caught it before the meeting. We spent forty-five minutes reconciling one line item. That's the real work more often than the cinematic version of financial leadership.
The Ultimate Guide To Unveiling The CFO Unlocking The Power Of The Chief Financial Officer
This guide is just a straightforward look at what a CFO does, how they do it, and why the job is harder than the title suggests. There are no frameworks with four pillars. There is just the actual mechanics. Before a CFO can do anything strategic, they need reliable data flowing through the company. I remember one company I worked with where the revenue figure in the CRM didn't match the revenue figure in the billing system, and nobody knew which one the bank used to approve their credit line. That kind of gap is a liability even if the difference is small, because it means no one can trust the reports when something actually matters. The practical approach is to pick a single source of truth for each category and document it. Revenue comes from one system. Expenses come from another. Fixed costs get separated from variable costs in a way that stays consistent month to month. When you build that foundation, most of the downstream problems stop existing on their own.
This usually cuts the closing process from around ten days down to about four, depending on how messy the data was to start with.
Get the Full Details

How CFOs actually control cash flow
Cash flow management is where the CFO role becomes visible. It is less about forecasting perfection and more about understanding timing. You can be profitable on paper and still run out of money if your receivables stretch too long while your payables stay short. I have seen CFOs use a simple aging schedule for receivables, tracked weekly, and that one practice alone kept a mid-size company from hitting a cash crisis twice in a single year. They would flag accounts past sixty days and escalate collections before the relationship got damaged. The alternative is waiting until the bill is ninety days old, which is when you start losing leverage. The same logic applies to payables. Paying too early is leaving money on the table. Paying too late risks supplier relationships and sometimes late fees that add up faster than people expect. The CFO's job is to find the window where both sides work, and that requires discipline more than talent.
Building reports that people actually read
Most internal financial reports are ignored because they try to show everything. A CFO who wants attention should write the opposite way. One page for the executive team. Clear headers. No footnotes unless they change the conclusion. I developed a habit of starting every report with the single number that matters most for that period, then explaining why it moved. Revenue up twelve percent? Here is the breakdown by segment. Margin compression? Name the cost driver and what we are doing about it. When you give a conclusion first, people either agree or ask pointed questions, and either way you save time.
Where the CFO role hits real limits
No amount of financial skill fixes a broken business model. I watched a CFO at one company spend six months trying to optimize working capital while the core product was losing market share every quarter. The numbers looked fine on paper, but the company was bleeding customers. Financial optimization cannot compensate for a fundamental strategy problem. The same thing happens in reverse when leadership treats the CFO as a gatekeeper rather than a partner. If the CEO never shares competitive pressures or operational risks ahead of time, the CFO is making plans based on incomplete information. That creates friction, and the financial output suffers because it was built on a foundation someone else failed to disclose. Another limitation worth noting is that CFOs control budgets, but they do not control execution. A well-structured financial plan falls apart if the team responsible for delivery lacks clarity or resources. The CFO can flag the risk, but they cannot fix the operational gap alone.

Practical tools most CFOs end up relying on
The core stack is usually not complicated. A budgeting module inside the ERP, a reconciliation tool for monthly close, a cash flow dashboard that updates weekly, and a forecasting model that allows scenario changes without rebuilding the sheet from scratch. One detail that matters more than people think is version control on the forecasting model. I once opened a file that someone had copied and edited without tracking changes, and we wasted an entire afternoon reconciling three different versions of the same quarterly projection. A naming convention and a shared folder structure prevent that mess.
When to bring in outside help
Not every company needs a full-time CFO from day one. Startups often get by with a fractional CFO who comes in twice a month to review cash flow and challenge assumptions. That arrangement usually works until revenue crosses the point where daily financial decisions require someone physically present or immediately available. Conversely, some larger companies hire a senior CFO but fail to give them enough authority over operational decisions. The role becomes ceremonial instead of functional. The fix is straightforward in theory but hard in practice: the CFO needs direct access to the data and a seat at the table where strategy gets decided, not just where the final numbers get approved.
Bottom line
The CFO role is less about unlocking power and more about maintaining control over information, timing, and risk. The people who do it well tend to be the ones who pay attention to small inconsistencies before they become big ones. They also know when the numbers are lying to them, usually because someone defined a metric in a way that looks good but means nothing. If you are trying to understand the CFO function in your own organization, start by asking which reports are actually used and which are just filed away. The answer to that question reveals more about the real role than any job description ever will.