Understanding the Ulta Beauty Credit Card Program
The Ulta Beauty credit card program is actually two separate cards issued by Comenity Bank, not one monolithic product. The entry-level option is the My Ulta Credit Card, which requires a minimum of 500 loyalty points in your Ulta Rewards account before you can even apply. The higher tier is the Ultamate Credit Card, available to members who have reached the Ultamate Rewards level (2,000 points). Knowing which card you qualify for matters because the rewards structure, sign-up bonuses, and ongoing benefits differ between them. I picked up this distinction the hard way during a routine application. I had roughly 1,200 points after about a year of casual shopping, which put me squarely in the middle zone. I tried applying for the Ultamate version because the sign-up offer looked better. The application was instantly declined with a generic message that mentioned nothing about point eligibility. After calling customer service, the representative confirmed I was ineligible for the higher-tier card due to insufficient loyalty points, and redirected me to the My Ulta Credit Card instead. The workaround was simple: I just waited a few more months of normal purchases to push past 2,000 points, then reapplied. No appeal process exists for this particular restriction. It's a hard gate on Comenity's side.
The Ultimate Guide To Ulta Beauty Credit Card Unlocking Exclusive Benefits And Rewards
How the Rewards Structure Actually Works
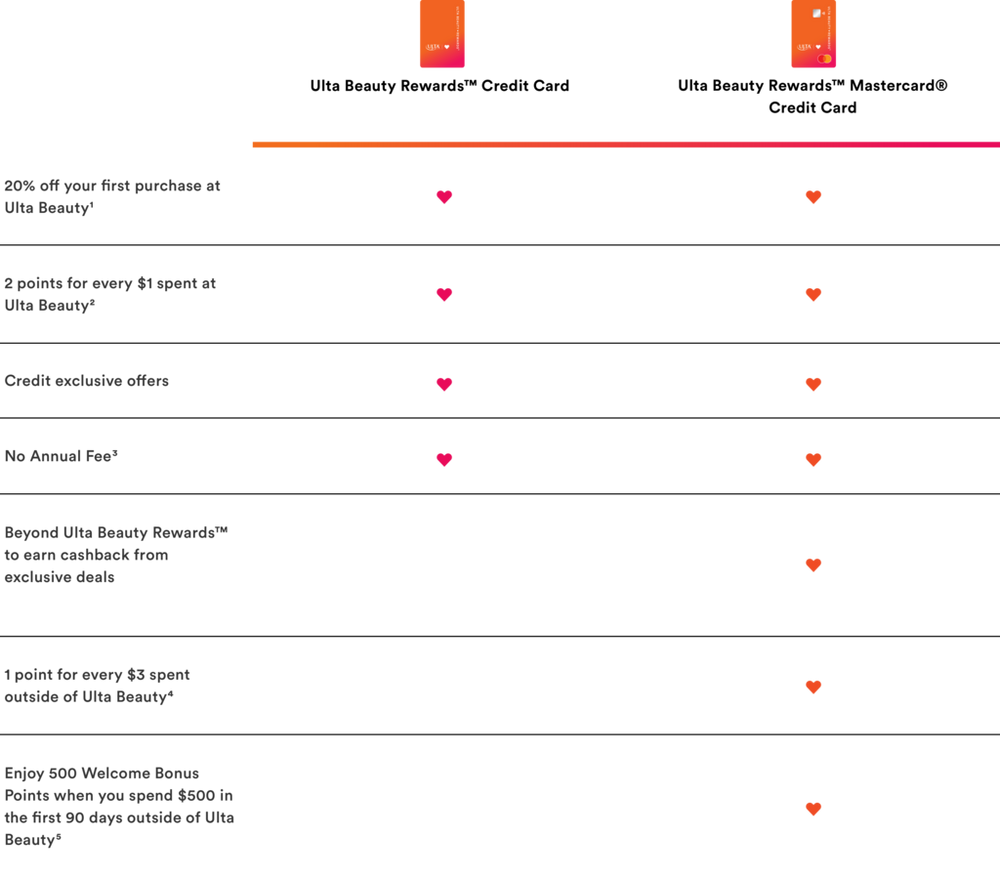
The point-earning mechanics are straightforward on paper but have some quirks in practice. The My Ulta Credit Card earns 2 points per dollar spent on Ulta brand products and 1 point per dollar on everything else, including salon services, treatments, and third-party items. The Ultamate Credit Card bumps the base rate to 2x points on all Ulta purchases, regardless of brand, and 1x on everything outside the store. This means if you regularly buy drugstore brands at Ulta like CeraVe or e.l.f., the Ultamate card gives you double points on those too, whereas the lower-tier card does not. A sign-up bonus currently runs around 20% off your first purchase of $75 or more with the My Ulta card, and roughly 30% off the same threshold with the Ultamate card. These promotions shift quarterly based on Comenity's marketing calendar, so the exact percentage will vary when you apply. I've tracked the offers going from 20% down to 15% and back up again across different application windows. The 30% offer tends to appear during holiday seasons and Ulta's anniversary events in May and October.
The Point System and Redemption Math
Ulta's points operate on a 100-points-per-dollar basis for redemption, but each point is worth significantly less than that ratio suggests. Specifically, 100 points equal $3.50 off a purchase, which works out to roughly 0.35 cents per point. When you're earning 2x points on eligible purchases, your effective discount rate is about 0.7% back on those transactions. That's not aggressive compared to cash-back cards in the 2-3% range, but the value proposition shifts when you factor in the sign-up bonus and the birthday gift, which I'll cover next. The birthday reward is one of the more useful perks that people consistently undervalue. My Ulta members receive a free gift during their birthday month, and Ultamate members get a larger gift selection plus an additional 20% off a single item on their birthday. I calculated this at roughly $15 to $25 in value depending on what you claim, which translates to about 4,000 to 7,000 bonus points you wouldn't otherwise earn. It's a meaningful bump if you plan to shop anyway.
Get the Full Details

Exclusive Perks Beyond Points
Besides the point multiplier and birthday rewards, the cards offer access to Ulta's sales events and early access to product launches for high-tier members. There's also free standard shipping on all online orders for cardholders, which saves roughly $7 to $10 per order if you don't hit the free shipping threshold through spending alone. That $7 saving represents about 2,000 points at face value, though technically it's a service benefit rather than a point earning mechanism. The free shipping benefit has a practical limitation worth noting. If you're ordering from multiple Ulta websites — like the US and Canadian sites — the benefit may not carry over between regions. I learned this when a friend in Canada tried using the US card's free shipping and got charged anyway. The benefits are region-locked to the point account's country of origin.
Application Process and Credit Considerations
Applying for either card happens through Comenity Bank's portal and requires a soft or hard credit pull depending on whether you're just checking your eligibility or submitting a full application. The soft pull shows your pre-qualified offers without affecting your score. The hard inquiry drops your credit score by roughly 5 to 10 points temporarily. If you already have a solid credit profile, this is negligible. If you're actively applying for other credit products like a mortgage, spacing out these inquiries by several months is the practical move. The approval process typically returns a decision within minutes. When approved, your digital card is available immediately in the Ulta app for online purchases, and a physical card arrives within 7 to 10 business days. Some users report that the digital card can take up to 24 hours to activate in certain cases, usually when there's a mismatch between the application address and the address on file with Comenity. Double-check your billing address before submitting to avoid this delay.
Common Pitfalls and Edge Cases
One issue that comes up repeatedly involves point posting delays. Purchases made right before your statement closes might not show up in your rewards balance until the following cycle, which can throw off your redemption math if you're counting on a specific point total for a redemption event. I had this happen once when I was trying to redeem 3,500 points for a $12.25 discount during a promotional window. The points from my last three transactions hadn't posted yet, so I fell short by about 800 points and missed the redemption. The workaround is to check your projected balance in the Ulta app rather than relying on the displayed number, since the app sometimes shows pending transactions that haven't officially posted to your rewards ledger. Another pitfall is assuming that gift card purchases earn rewards points. They do not. If you buy an Ulta gift card with your credit card, those dollars generate zero points. This isn't unique to Ulta but it's easy to overlook if you're trying to maximize point accumulation on a large purchase. I've seen people accidentally funnel thousands of dollars through gift cards thinking they were earning double points, when in fact they were earning nothing on that portion of the spend.
When the Card Makes Sense and When It Doesn't
The Ulta credit card is worth carrying if you shop at Ulta regularly and can absorb the sign-up bonus plus ongoing point earnings to offset the opportunity cost of not using a higher-reward cash-back card elsewhere. For someone spending $500 per month at Ulta on the My Ulta card, that's roughly 1,000 points per month or about $3.50 in monthly savings. Over a year, that's $42 in point value plus the birthday gift and any sign-up bonus you capture. Not bad for a card you'd likely have anyway. The card falls apart as a strategy if your Ulta spending is sporadic or minimal. The annual fee is zero for both cards, so there's no direct cost to holding it, but there's an indirect cost in terms of credit utilization and the opportunity cost of using a 1% to 2% effective rewards card instead of a 2% to 5% cash-back alternative for your non-Ulta purchases. Keep the Ulta card for Ulta spending and use a different card for everything else. Mixing them up and charging groceries on the Ulta card is a common mistake that quietly erodes your total rewards earnings. If you find yourself shopping at Ulta frequently but want stronger returns, consider pairing the card with a general cash-back card and only charging Ulta purchases to the credit card. This hybrid approach preserves the sign-up bonus and the point multipliers on eligible purchases while protecting your overall rewards rate across all other spending categories. It requires a bit more discipline at checkout but the math works in your favor consistently.