Logging Into TIAA Retirement: What Actually Happens When You Try
I have helped enough people troubleshoot their TIAA accounts to know that the login process itself is straightforward but the stuff after that is where most people get tripped up. The portal works, it just requires you to pay attention to a few details that are easy to miss on your first try. Here is how you actually get in and what you need to do once you are there. First, go to mia.tiaa.org. That is the current My TIAA portal. Older links to tiaa.org/logmein still redirect there but they just add an extra step. Use the direct URL and stop wasting time watching the browser spin.
You will need your Net ID and password. If you set these up years ago and never logged back in, your credentials might still work but the security questions can be painful to reconstruct. I had a client who lost access because she had changed her email address twice and forgotten which one was registered. She spent forty minutes on the phone with TIAA support before realizing she could reset through the "Forgot your password" link using her phone number on file. The phone verification route is faster than the email reset if your email is outdated. Just make sure your mobile number is current in the system first or you are going in circles. Two-factor authentication is mandatory now. After you enter your credentials, you will get a push notification through the My TIAA mobile app or a six-digit code. The app method is cleaner. The SMS method works but carriers sometimes delay those texts by thirty seconds to a minute, and the login window times out after three minutes of inactivity. I have seen people lock themselves out by trying to re-enter codes while the session was already expired. Wait for the full push notification to arrive and approve it within the app rather than refreshing the page repeatedly.
What You Actually Need to Do Once You Are In
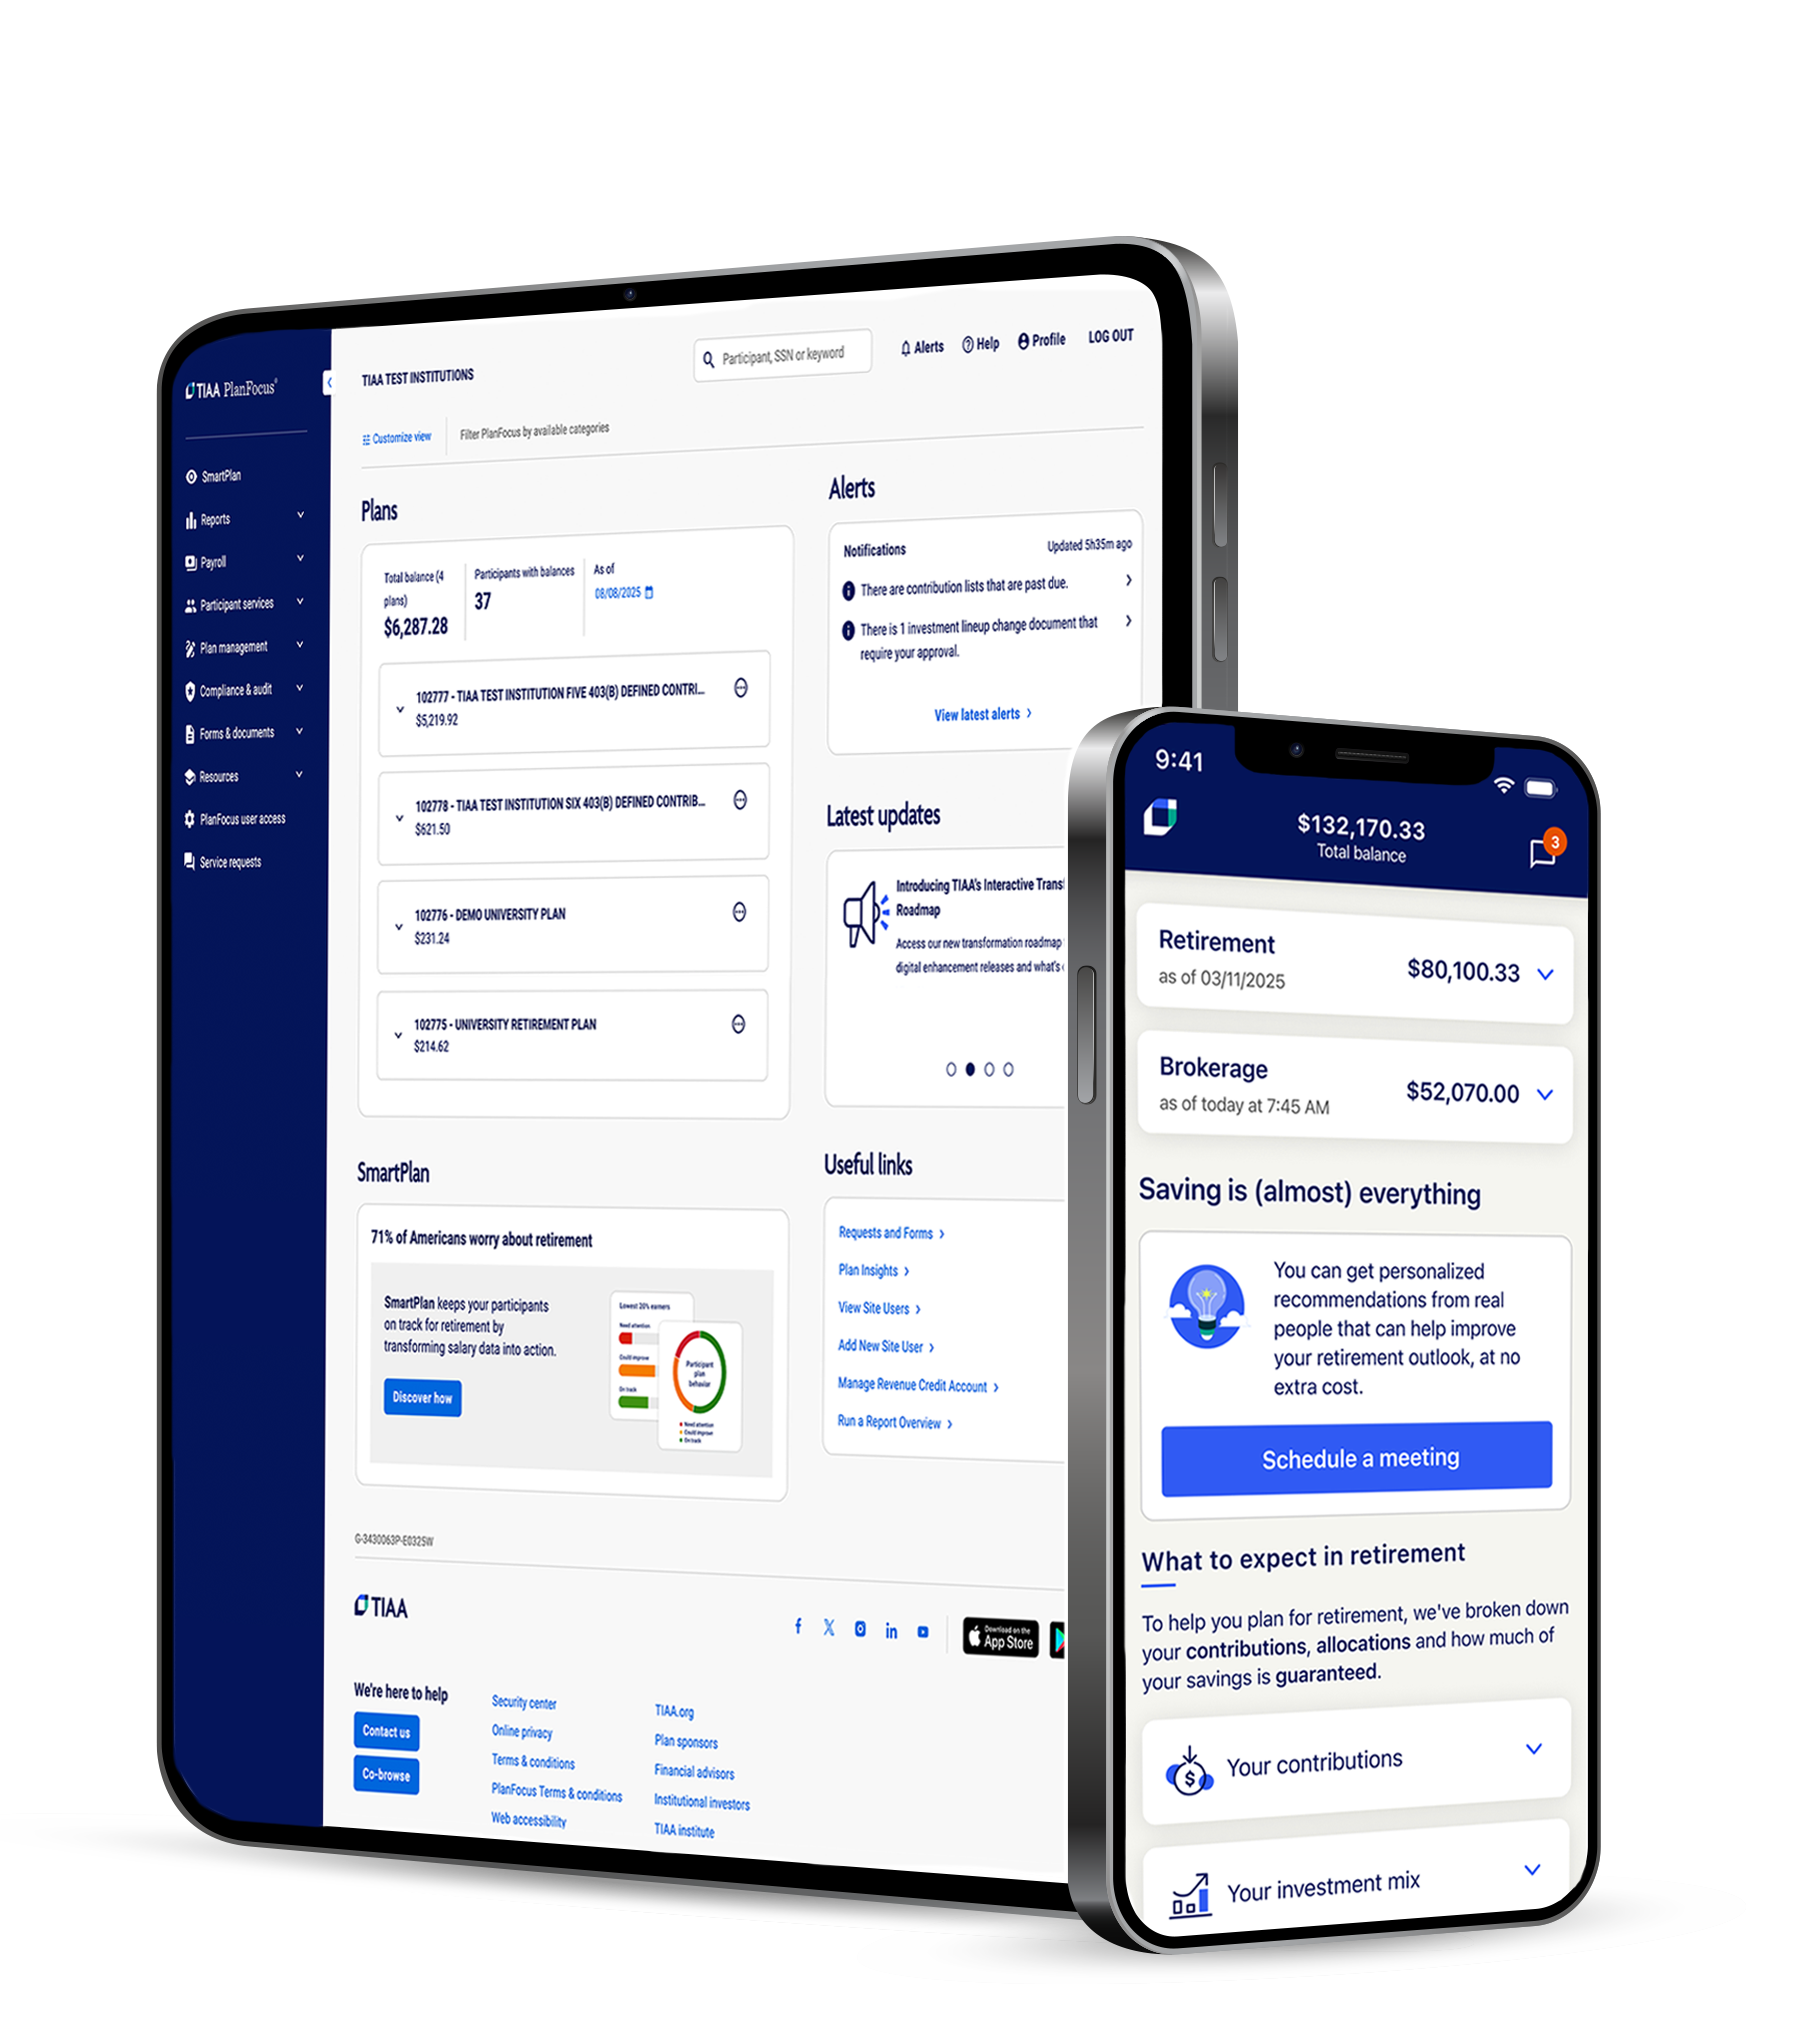
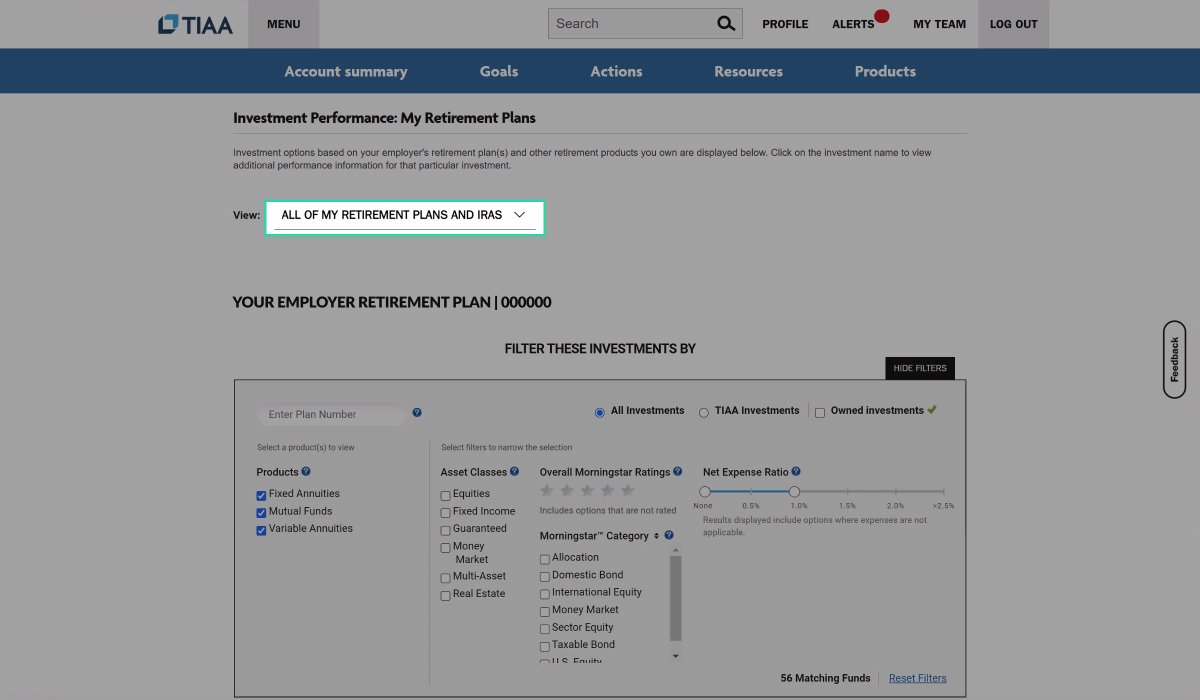
Getting logged in is the easy part. The real work is understanding what you are looking at. The dashboard shows your total portfolio value across all account types. This includes traditional 403(b) plans, 401(a) government accounts, employer-sponsored 457 plans, and annuity products. The aggregate number is useful but it does not tell you much on its own. You need to click through each account to see allocation breakdowns, fees, and beneficiary designations separately. The "Change Investments" section is where people make costly mistakes. The interface lists every fund available in your specific plan, which can be anywhere from twenty to sixty options depending on your employer's choice. I have watched people move money into higher-fee active funds without checking the expense ratio. TIAA offers both their proprietary CREF and S&P 500 index funds and third-party funds. The third-party ones often carry expense ratios above one percent while TIAA's own index funds run under zero zero five percent. Over twenty years, that difference compounds into tens of thousands of dollars. It is not dramatic language, it is just basic math.
Get the Full Details

Here is something most people miss. TIAA lets you set up recurring investment transfers inside the platform. You can direct a portion of your paycheck into any fund automatically. The default is usually to deposit everything into the target date fund you selected when you enrolled, but you can override that immediately. I recommend reviewing this setting within thirty days of logging in for the first time. If you have been contributing blindly to a high-fee fund, changing that redirect takes effect next pay cycle and costs nothing. The document library under "View Documents" contains annual statements, tax forms, and plan summaries. PDF downloads are instant but they do not stay organized. Your browser folder gets cluttered quickly. I set up a simple naming convention on my end years ago where I save every statement as the date plus account type. It sounds trivial but finding a specific 2019 1099R form during tax season saved me an hour of digging through unmarked files. TIAA keeps statements online for seven years, which is plenty, but having a local copy is still worth it.
Pain Points and Where the Platform Falls Short
I want to be blunt about what does not work well. The mobile app is functional but it lacks several features that exist in the web version. You cannot change investment allocations from the app. You cannot request distributions from the app. You cannot view detailed fee breakdowns for individual fund holdings. If you need to do any of that, you have to use a desktop browser. That is a genuine limitation, especially for people who manage their accounts primarily on their phones. Customer service wait times are another issue. During open enrollment periods and end of fiscal year, calling TIAA can mean a thirty to forty minute hold. The online chat feature is marginally better but sometimes routes you to someone who cannot access certain account details without a callback request. The workaround is to file a secure message through the portal before calling. Those messages get responses within two business days and they create a paper trail, which matters if you ever need to dispute a transaction or prove that you requested a change. Beneficiary designation changes are another area where the process is slower than it should be. The online form exists but depending on your state and plan type, TIAA may require a notarized signature or a printed form mailed in. Some states recognize the electronic submission, some do not. I learned this the hard way when a client uploaded a beneficiary update and assumed it was final. Three weeks later she got a call asking for a notarized copy because her state required it. The update was not processed yet and the old beneficiary remained on file. Always check the confirmation email carefully. It will explicitly say whether additional documentation is needed or if the change is immediate.
Advanced Settings You Should Review Periodically
Once per year, go into account settings and verify three things. Confirm your tax withholding elections are still correct. Make sure your direct deposit for distributions, if you have one, points to the right bank account. Check that your emergency contact on file is up to date. The rollover feature is also worth understanding if you change employers. TIAA allows you to roll over assets from other qualified plans, but you have to initiate the request yourself through the "Transfer and Rollover" section. The process typically takes ten to fifteen business days if all paperwork is in order. If the old plan administrator is slow responding, it can stretch to three weeks. Keep a record of when you submitted the request and follow up once if nothing moves after ten business days. RMD (Required Minimum Distribution) calculations are handled by TIAA automatically once you turn seventy three. You do not need to calculate anything yourself. TIAA sends a notice each January with your specific distribution amount based on your account balance and life expectancy factor. Pay attention to that number. Taking less than your RMD triggers a fifty percent penalty on the shortfall. That penalty is brutal and entirely avoidable if you file the distribution request before the deadline.

Bottom Line
TIAA Retirement login gives you access to a platform that is competent but not intuitive. The basic steps are simple: go to the site, enter credentials, complete MFA, and navigate the sections you need. The harder part is understanding the differences between fund options, watching for hidden fees, and keeping your personal information current. The system does what it is supposed to do. It just expects you to be the one doing the work of paying attention.