Setting Up Direct Deposit at Wells Fargo
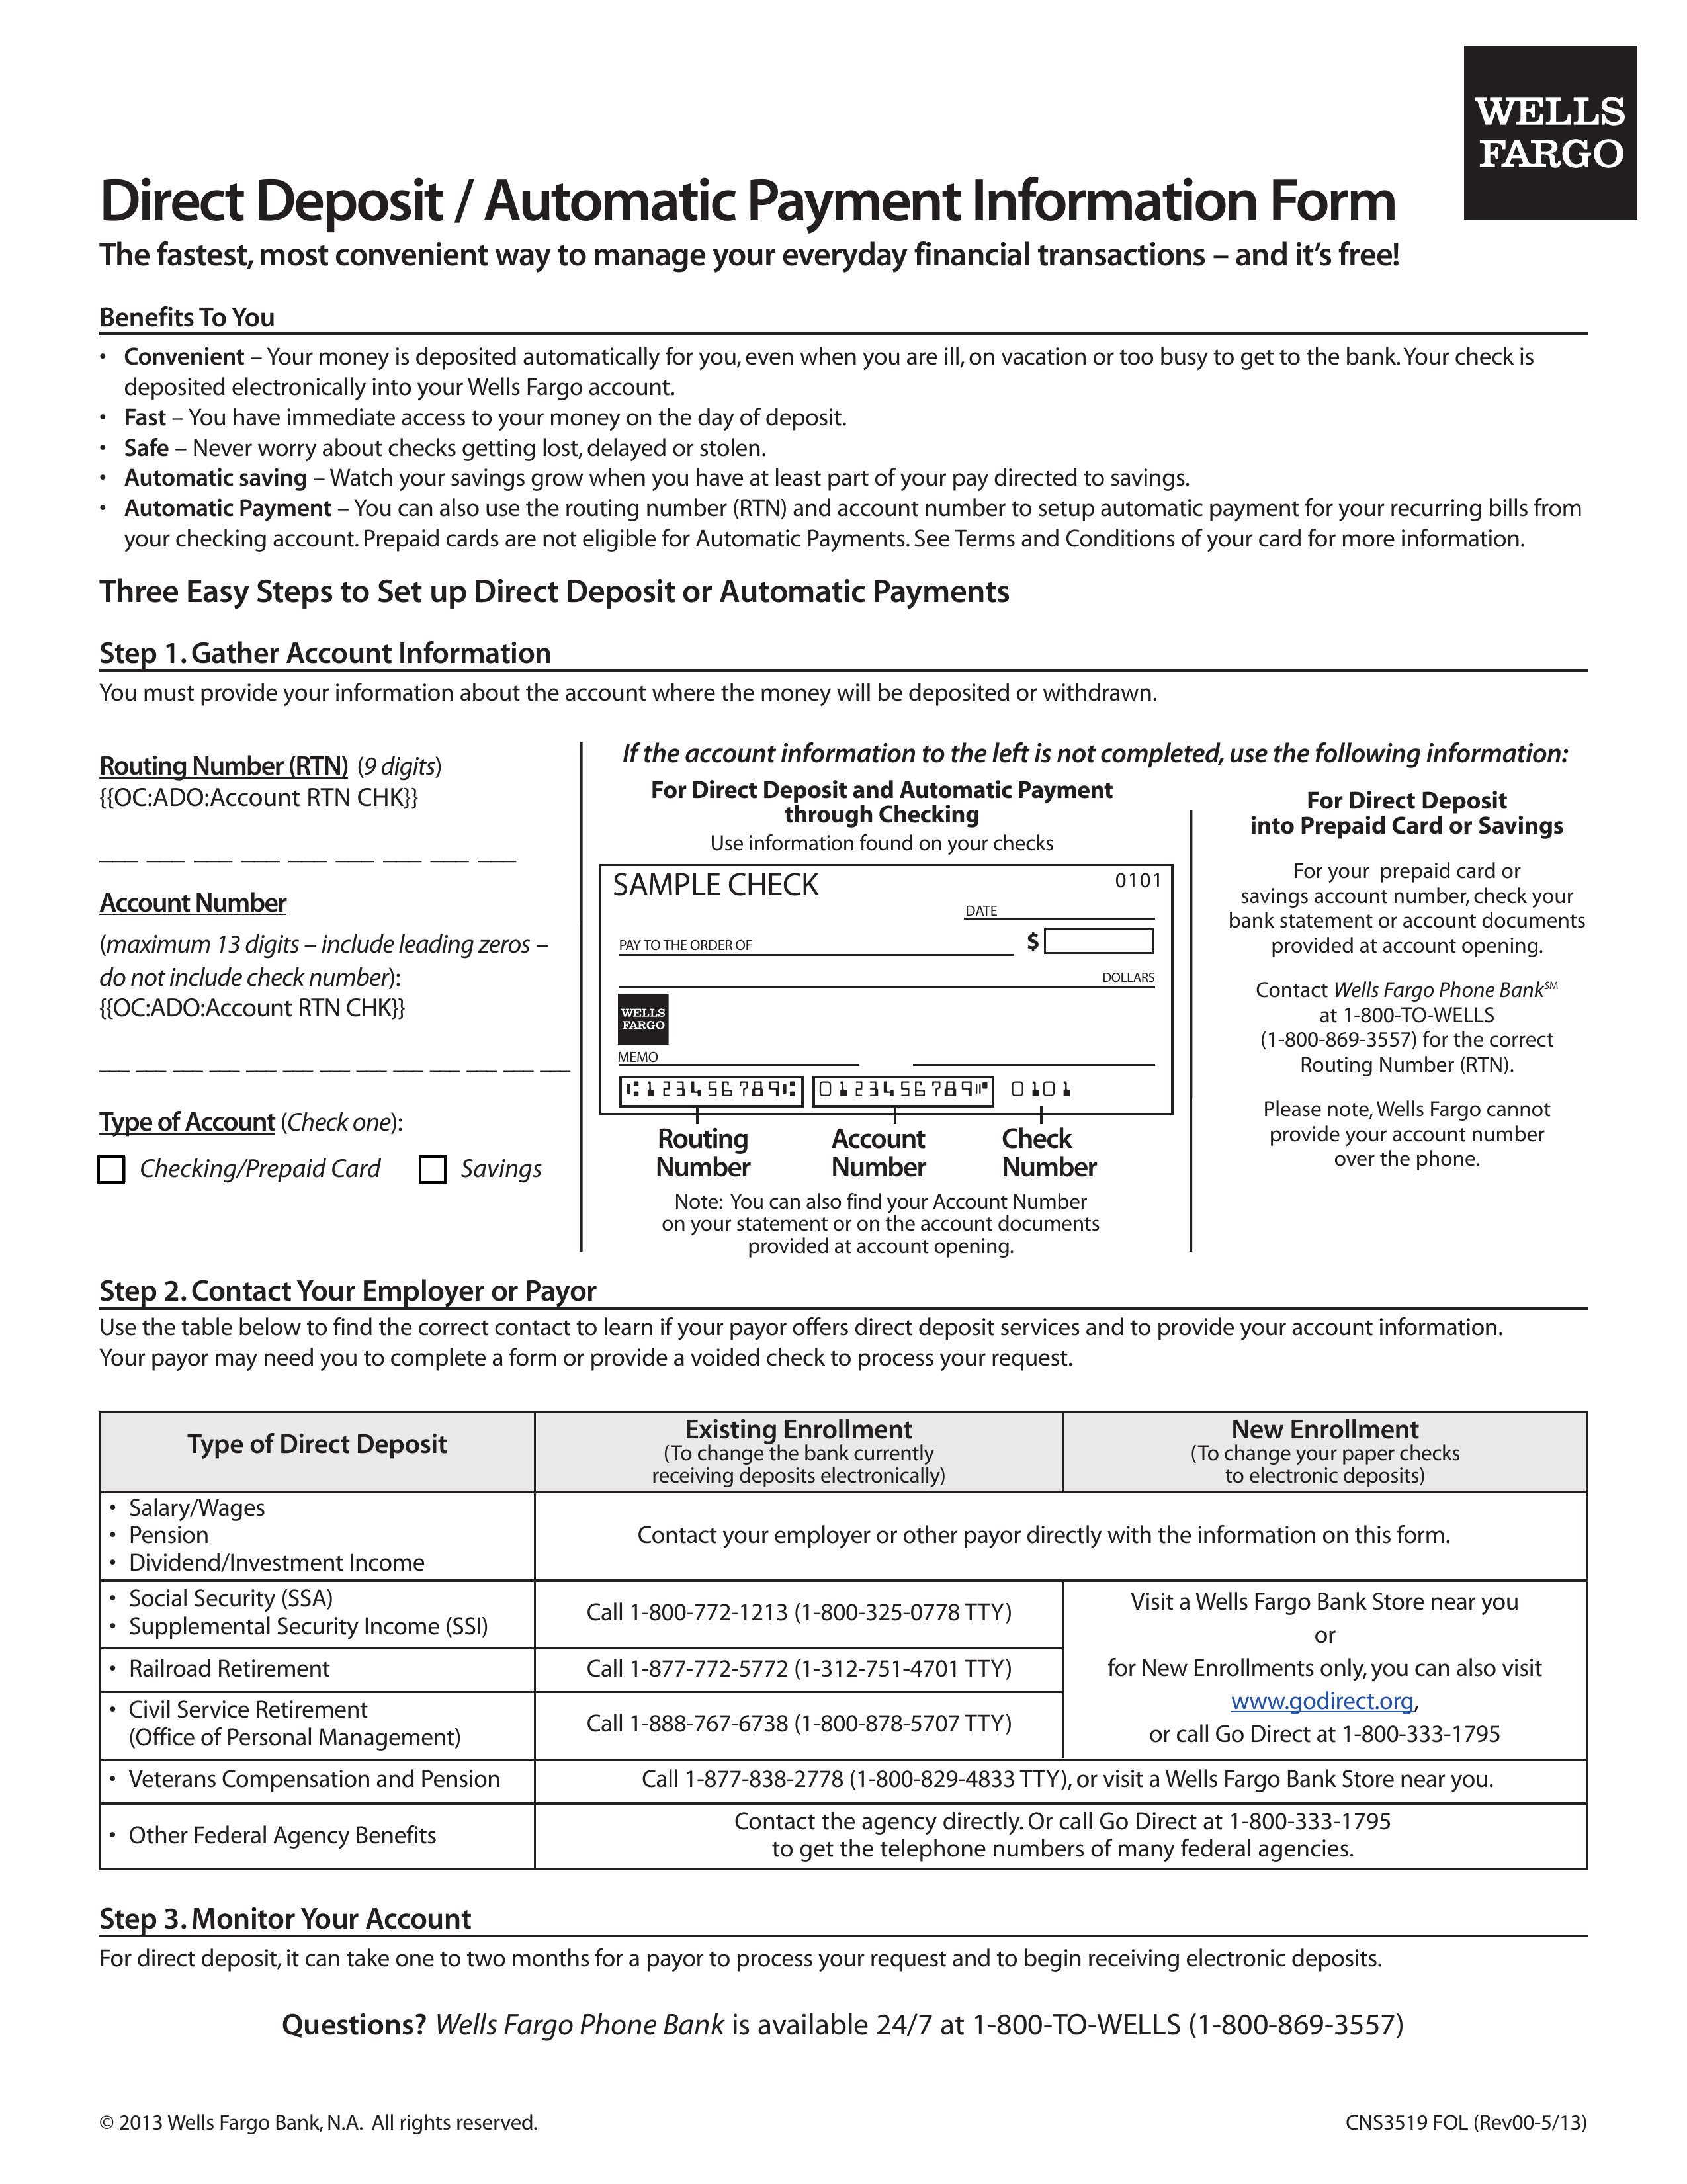
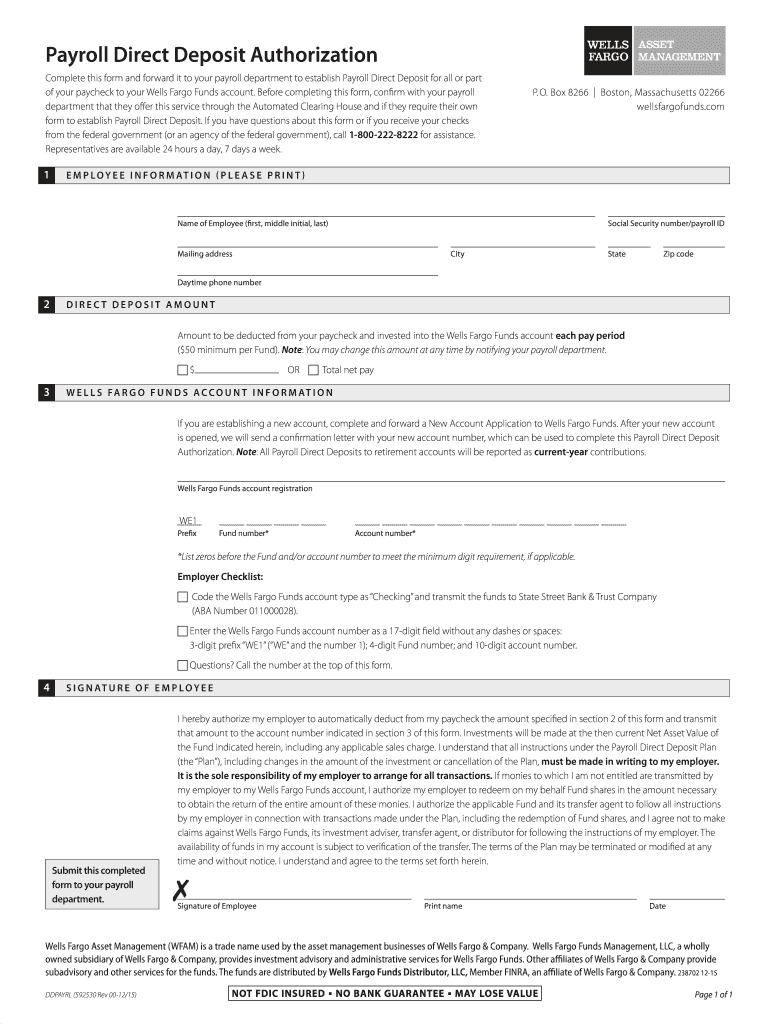
The direct deposit setup process at Wells Fargo is straightforward if you know which fields actually matter. Most people mess this up by rushing through the form and then wondering why their first deposit gets rejected. I've been doing this for years across different banks, and Wells Fargo has some quirks that aren't obvious unless you've hit them head-on. Let me start with the form itself. Wells Fargo doesn't actually have a single official PDF form you download and mail in. What most people are referring to is the Direct Deposit Authorization form that's available either through online banking under the account settings, through the mobile app, or as a fillable document you can get at a branch. There's also the W-4 form employers give you, but that's for taxes, not for setting up the deposit itself. The Wells Fargo form typically requires your routing number, account number, account type (checking or savings), and the effective date for the first deposit. Some versions also ask for a voided check or direct deposit authorization letter from your employer. The routing number is 121042882 for most accounts, but I've seen this trip people up before because it varies depending on the state where you originally opened the account. If you're unsure, log into online banking and check your account details—don't guess. Using the wrong routing number is the number one reason direct deposits get rejected or delayed by several business days.
Here's a specific scenario I ran into recently. A coworker filled out the form and used the standard routing number but submitted it on a Friday afternoon. The deposit was supposed to hit Monday but didn't arrive until Wednesday. Turns out, he had selected the wrong account type on the form—he put savings when his direct deposit account was actually checking. Wells Fargo's system flagged the mismatch and held the deposit for manual review. It took three business days to sort out. The fix was simple: call the number on the back of your card, explain the situation, and have them update the account type on file. But the moral here is to double-check everything before you submit. Especially the account type field. It's easy to gloss over and it will cost you time later.
Filling Out The Form Correctly
When you're filling out the Wells Fargo direct deposit form, pay attention to these details. The routing number should be your bank's ABA routing number, not your branch's number. They can be different. Your account number needs to match exactly what's on file—no spaces, no dashes. Wells Fargo systems can sometimes auto-format this, but if you're handwriting it or copying from paper, enter it exactly as it appears on your checks or in your online banking dashboard. For the account type, select checking if that's what you use day-to-day. Savings accounts have withdrawal limits under Regulation D, though that rule was suspended during the pandemic and may have been reinstated since. If your employer sends your paycheck to a savings account, you might hit those limits and get fees or returned transfers. I'd recommend checking your account type rules before designating savings for direct deposit. There's also the matter of the effective date. If you submit the form mid-month and your employer processes payrolls on the 15th and the last day of the month, your first deposit might not show up until the next cycle. Some employers accept the form electronically through their payroll provider, which can be faster than mailing a paper copy. If you have access to your employer's payroll portal, use that. It usually processes the setup within one to two business days instead of the week or more it can take with paper forms.
Get the Full Details

Troubleshooting Common Issues
If your direct deposit hasn't appeared after what should have been enough time, here's what to check before calling anyone. First, verify that your employer actually submitted the deposit. Sometimes the holdup isn't on Wells Fargo's end—it's on the payer's end. Contact your payroll department and ask them to confirm the submission date and the details they used. Ask for a trace number or confirmation code if they provided one. Second, check your Wells Fargo online account for any pending transactions or holds. Sometimes deposits show up as pending before they post. Third, look at your account settings in the app or on the website to make sure the direct deposit authorization is listed and marked as active. If it shows as inactive or missing, the system hasn't properly linked your employer's information to your account. One thing Wells Fargo does differently from some other banks is that they offer a feature called "Direct Deposit Alert" in the mobile app where you can see when a deposit is incoming and its expected arrival time. I've found this useful for tracking deposits that seem slow. If the alert says the deposit is "in transit" and it's been more than two business days, that's when you should start calling.
Another edge case worth mentioning: if you recently changed your account or closed an old one, the direct deposit authorization might still be tied to the previous account number. I ran into this myself when I merged two accounts during a bank restructuring. My old direct deposit link was still active in my employer's system, pointing to a now-defunct account number. The deposit bounced back to the employer, who then had to reprocess it. The fix required both me updating the account info in my employer's payroll system and Wells Fargo terminating the old authorization. It took about five business days from start to finish. If you've made any recent changes to your accounts, confirm with your employer that they have the correct routing and account numbers before your next pay period.
What The Form Doesn't Cover
The Wells Fargo direct deposit form won't tell you about split deposits, where part of your paycheck goes to one account and part to another. If you want that, you need to set it up through your employer's payroll system, not on the form itself. Similarly, the form doesn't handle international direct deposits or foreign currency payments. Those require a different process altogether and usually involve additional documentation like an International ACH file or a SWIFT code. Also, if you're setting up direct deposit for something other than a paycheck—like a government benefit or tax refund—the process is the same, but the timing can be different. Government deposits sometimes take longer to verify, especially for first-time setups. The IRS and state agencies often run additional fraud checks on new direct deposit arrangements, which can add a day or two to the processing window. Don't panic if your first government deposit is late. It's normal.
Verification And Security
Wells Fargo may require identity verification before activating a new direct deposit, especially if you're setting it up online for the first time or if the deposit amount is unusually large. They might call you to confirm details, ask for a photo of your ID, or require you to visit a branch. This is standard security practice and not something to worry about. It usually takes less than ten minutes if you have your documentation ready. Some people also ask whether they need to provide a voided check alongside the form. Wells Fargo generally doesn't require this if you're setting up the deposit through their online or mobile channels, since they can pull the routing and account numbers directly from your profile. But if you're submitting a paper form by mail or in person, bringing a voided check can speed things up. It eliminates any chance of a typo in the account number. One last practical note: if you're ever unsure about the routing number for your specific account, don't rely on generic lookup tables online. They're often outdated. Log into your Wells Fargo account, go to the account details page, and pull the routing number directly from there. Or call customer service and ask them to read it back to you. It's a two-minute call that prevents a two-week headache later.