How The Sephora Visa Actually Works In Practice
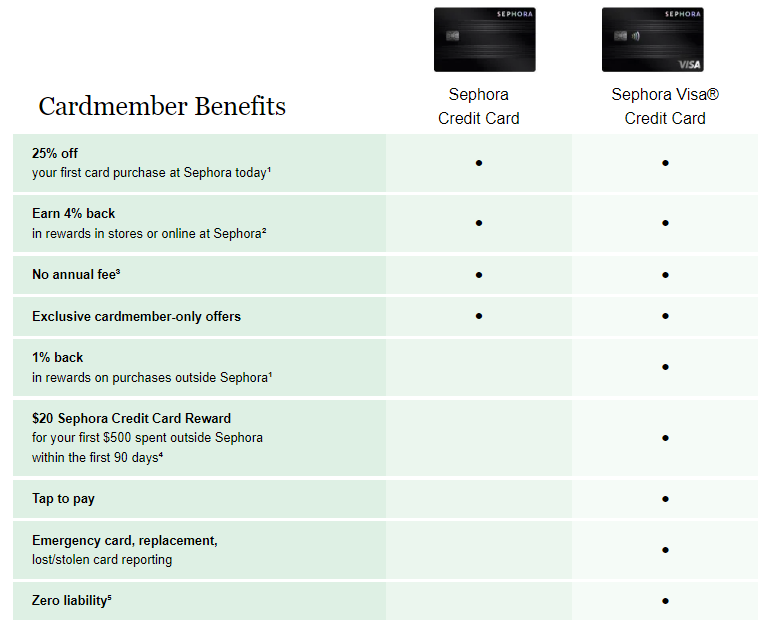
I used to hand out Sephora gift cards like candy when my sister turned 16. Now I handle credit card applications for a living and I still recommend the Sephora Visa to people who shop there weekly. The card itself is straightforward. You earn 2x points on Sephora purchases, 1x everywhere else, and the signup bonus is typically 3,000 points after spending $500 in the first three months. That 3,000 point threshold translates to roughly $75 in beauty credit, which covers a single high-end perfume or two mid-range products. Here is what most people miss about this card. The Beauty Insider tier system stacks on top of the card rewards, which means you are technically earning double benefits simultaneously. The card points go toward Beauty Insiders, but your shopping velocity still counts toward Rouge status. I have watched people hit Rouge level within eight months by combining regular Sephora trips with this card. The math works. $1 spent equals 1 Beauty Insider point regardless, and the card's 2x multiplier runs on top of that separate ledger. The annual fee is zero. That is the main reason this card exists and why it stays competitive despite the reward rate being lower than cash-back cards aimed at groceries or gas. It is a co-branded card designed to keep you locked into one retailer. The downside is obvious if you compare it to a Chase Sapphire or American Express Gold. You will earn less on non-Sephora spending. A flat 2% cash-back card beats this on general purchases every time.
What You Need To Apply
Chase issues this card. That means you need a decent credit score, preferably above 670, though the approved range often starts around 640 for borderline applicants. You also need a Social Security number and a checking account since Chase will verify identity through their usual channels. The application takes about four minutes online. The decision is instant in most cases. I have seen declined applications happen because of Chase's internal scorecard rather than the credit score itself. Recent hard inquiries, new accounts, or high utilization ratios trigger those automated declines more often than people expect. One practical note: if you apply and get declined, do not reapply the same month. Chase has a 5/24 rule that counts any personal credit card opened in the past two years. Getting declined generates a hard pull anyway. Wait until the inquiry ages out or your utilization drops below 30% before trying again.
Redeeming Points Without Losing Money
The reward tiers are 3,000 points for a $75 Beauty Credit, 6,000 for $160, 12,000 for $350, and 25,000 for a $750 credit. Here is where people make mistakes. The Beauty Credit only applies to specific purchases at Sephora. It does not cover shipping fees or certain third-party items depending on the region. I learned this the hard way during a Black Friday order when I tried to apply a $350 credit toward a purchase that included a non-eligible brand and got hit with a $12.99 shipping charge that the credit would not cover. The workaround is simple. Check your cart for any items marked as ineligible before redeeming. Sephora's site will show a warning message if an item cannot be purchased with Beauty Credit. Remove those items, use a separate payment method for them, and apply the credit to the eligible portion. Alternatively, split the order into two transactions if the cart is too messy to sort through quickly. It takes an extra click but saves frustration.
Get the Full Details

The Real Perk Most People Overlook
Early access to sales. Sephora sometimes opens VIB Rouge or Beauty Insider exclusive sales to Visa cardholders 24 hours before the general public. This matters more than the points on high-drop days. Limited edition palettes sell out within minutes during these windows. I grabbed a Pat McGrath palette at the VIB sale price during a cardholder preview and it was sold out to everyone else by afternoon. The savings from early access alone justify keeping the card open even if you stop using it for points. If you shop at Sephora less than twice a month, the opportunity cost is real. A card earning 3% back on everything plus 4% on dining and travel will outperform this by a wide margin. The Sephora Visa shines for people who already spend $200 to $400 per month at Sephora. At that spend level, you are pulling out $48 to $96 annually in excess rewards compared to a standard rewards card, not counting the signup bonus. Below $150 per month, it becomes a mediocre secondary card at best. Another limitation: the card does not offer foreign transaction fee waivers. If you shop Sephora internationally, you will pay an additional 3% on every purchase. This makes it a poor choice for travel-related Sephora runs. The Chase Sapphire Preferred or Reserve both waive foreign transaction fees and earn better transfer rates, so those cards serve that purpose far more efficiently.
A Quick Note On Points Expiration
Beauty Insider points do not expire as long as you earn or redeem at least once every 18 months. The Sephora Visa points follow the same calendar. Keep an eye on this if you stop shopping at Sephora for a while. One small purchase or a redemption will reset the clock. I let mine lapse once after moving countries and lost about 8,000 points that I had been saving for the $350 tier. It was a stupid mistake that took me three months to recover from.