How PNC CD Rates Actually Work Right Now
PNC Bank's certificate of deposit offerings are not particularly exciting compared to some online competitors, but they do serve a specific kind of customer. If you already bank with PNC and prefer dealing with a physical branch network, their CD rates are acceptable. If you are shopping purely on yield, you will likely find better numbers elsewhere. I want to walk through what you need to know before putting money into a PNC CD, because there are a few things that trip people up. Let me start with a practical detail most people miss. PNC offers two different CD tracks: their standard CDs and their Online Exclusive CDs. The Online Exclusive rates are usually a few basis points higher, but they require you to open and manage the account through PNC's digital platform. This does not mean much more than navigating their website, but if you primarily bank in branch, you might never see the better rate. When I was managing a client's treasury work a few years back, they had hundreds of thousands tied up in standard branch CDs while the online variant was paying noticeably more. They had been using the branch for decades and simply never checked. PNC CD terms typically range from six months to ten years, though the longer terms often have weaker rates than you would expect. The current rate environment has flattened the CD curve somewhat, meaning the premium for locking in six years is marginal compared to two years. That is different from the pre-2022 landscape where longer terms paid meaningfully more. Now you have to look at the actual annual percentage yield rather than assuming the longer the commitment, the better the return.
One structural detail that matters more than most retail investors realize: PNC has a tiered rate structure within each CD term. This means that once your deposit crosses a certain threshold, the rate jumps. The tier boundaries are not always published prominently on the rate sheet. For a standard five-year CD, the jump from the first tier to the second might occur at twenty-five thousand dollars or fifty thousand, depending on the promotion cycle. If you are working with a larger sum, splitting it across multiple tiers can meaningfully improve your overall yield without changing your term at all. I use a simple spreadsheet to map out the tier breakpoints and calculate the weighted average yield for each scenario before I recommend anything to a client. It takes about ten minutes and it changes the outcome more often than you would think.
Understanding the Early Withdrawal Penalty Structure
This is where PNC CDs differ from some online alternatives and it is worth reading carefully. The early withdrawal penalty on a PNC CD is calculated using a formula based on the number of months remaining in your term and the interest that would have accrued. For terms under six months, the penalty is typically seven days of interest. For terms between six months and ten years, it is usually ninety days of interest. For ten-year CDs, it can be one year of interest. The counter-intuitive part is that the penalty is not a flat fee. It is computed on the accrued interest at the time of withdrawal. In a rising rate environment, your CD may have accumulated modest interest, so the ninety-day penalty eats into a small pool and leaves you with most of your principal intact. In a falling rate environment where your CD locked in a high rate and has been compounding nicely, the penalty feels harsher because you are losing out on the opportunity to reinvest at the new higher rate while also paying the penalty. I had a client who pulled a three-year CD early when rates had already ticked up because she needed liquidity for a business expense. The penalty plus the reinvestment at a lower rate created a double hit that took nearly two years to recover from. She learned to keep a separate liquidity reserve before committing to a CD term. Another thing PNC does that is worth noting: they allow you to waive the early withdrawal penalty under certain hardship circumstances, but the bar is high and the process is slow. Medical emergencies, disability, and a few other situations qualify, but you need documentation and the review process can take thirty to forty-five days. Do not treat this as a backup plan for a CD you might need to access early. It is not reliable enough for that purpose.
Get the Full Details
Certificate Laddering With PNC CDs
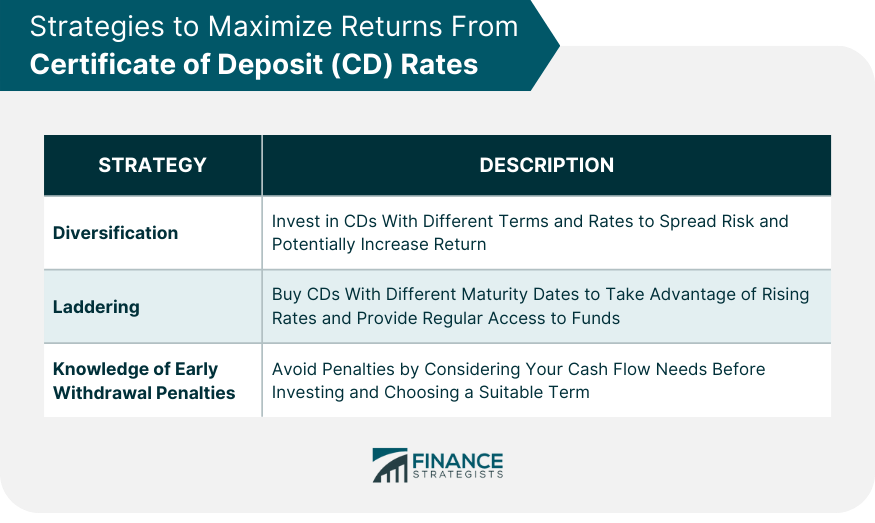
The laddering strategy works with any CD provider, including PNC, but the mechanics matter. You divide your capital across CDs with staggered maturity dates. A common setup is four equal portions maturing at one, two, three, and five years. As each CD matures, you reinvest it at the next rung of the ladder. This gives you liquidity access points every year while keeping most of your capital working at longer-term rates. Here is the practical issue with laddering at PNC specifically. If you open multiple CDs, each one is a separate account with its own management overhead. PNC does not offer a native ladder product that automates the reinvestment at a predefined schedule the way some online banks do. You have to manually reinvest each matured CD or set up reminders. This is not a dealbreaker, but it is friction. I typically recommend setting calendar alerts sixty days before each maturity date so you have time to compare the rate environment and decide whether to reinvest at PNC or move the funds elsewhere. Rates can shift meaningfully in sixty days. There is also a minimum deposit requirement to consider. PNC's standard CD minimum is usually one thousand dollars, while some promotional CDs require five thousand or ten thousand. If you are working with a smaller total amount, laddering across four or five rungs might mean each rung is too small to benefit from tiered pricing. In that case, a two-rung ladder or even a single well-timed CD may be more efficient. I advise clients to run the math on tier thresholds before committing to a multi-rung structure.
How PNC CD Rates Compare in the Current Market
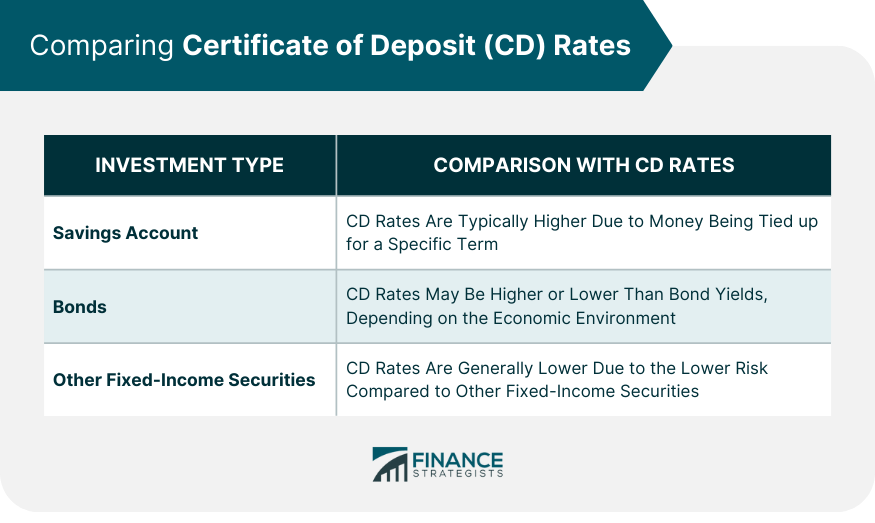
As of mid-2024, PNC's CD rates sit in a competitive but not leading position. National banks like PNC typically offer rates that are lower than online-focused competitors such as Marcus, Ally, or Capital One, but higher than some of the smaller regional banks that struggle to attract deposits. The spread between PNC and the top online rates is usually between fifteen and thirty basis points on a two-year CD and widens on longer terms. On a fifty-thousand-dollar deposit over five years, that spread can translate to several hundred dollars in foregone interest. Whether that matters depends on your situation. If the convenience of having a local branch and existing banking relationship is worth a few basis points, PNC makes sense. If yield is your primary concern, the math points elsewhere. One nuance that rarely gets discussed: PNC sometimes runs rate boost promotions that temporarily elevate CD yields by ten to twenty basis points. These promotions are often time-limited and targeted. You will not find them advertised on the homepage. They appear as email offers to existing customers or as special rates on select CD products during certain quarters. If you are an existing PNC customer, checking your online banking message center periodically can surface these boosts before they expire. I recommend doing this before any major CD purchase decision.
The Rollover Trap Most People Fall Into
When a PNC CD matures, it automatically rolls over into a new CD at the current rate unless you instruct otherwise. This is standard practice across the industry, but it is still the single biggest way retail investors lose money on CDs. The rate at rollover is often materially lower than the rate you locked in originally, especially if the Federal Reserve has cut rates during your CD term. I have seen clients wake up two years after maturity to find their CD had rolled over three times at progressively worse rates while they assumed it was still earning the original yield. The fix is simple: set a calendar reminder for every maturity date and actively decide whether to reinvest, roll over at a different term, or move the funds. The automatic rollover is a convenience feature, not a strategy. I want to be blunt about the limitations. PNC CDs are not ideal if you need maximum yield. They are not ideal if you want fully automated ladder management. They are not ideal if your deposit falls below the tier thresholds and you end up earning the bottom rate across the board. They are also not a good fit if you anticipate needing liquidity before maturity and do not have a separate emergency fund. The early withdrawal penalty is real and it can hurt, particularly on longer terms. If your priority is yield and you are comfortable managing accounts online, I would point you toward dedicated online CD providers first. If you value branch access and have an existing relationship with PNC, their CDs are a reasonable choice provided you stay alert to promotions, tier thresholds, and rollover dates. The difference in outcome between a proactive and passive approach to PNC CDs is significant enough that treating the account as set-it-and-forget-it is a mistake.