Understanding Ocala Zip Code Data for Property Analysis
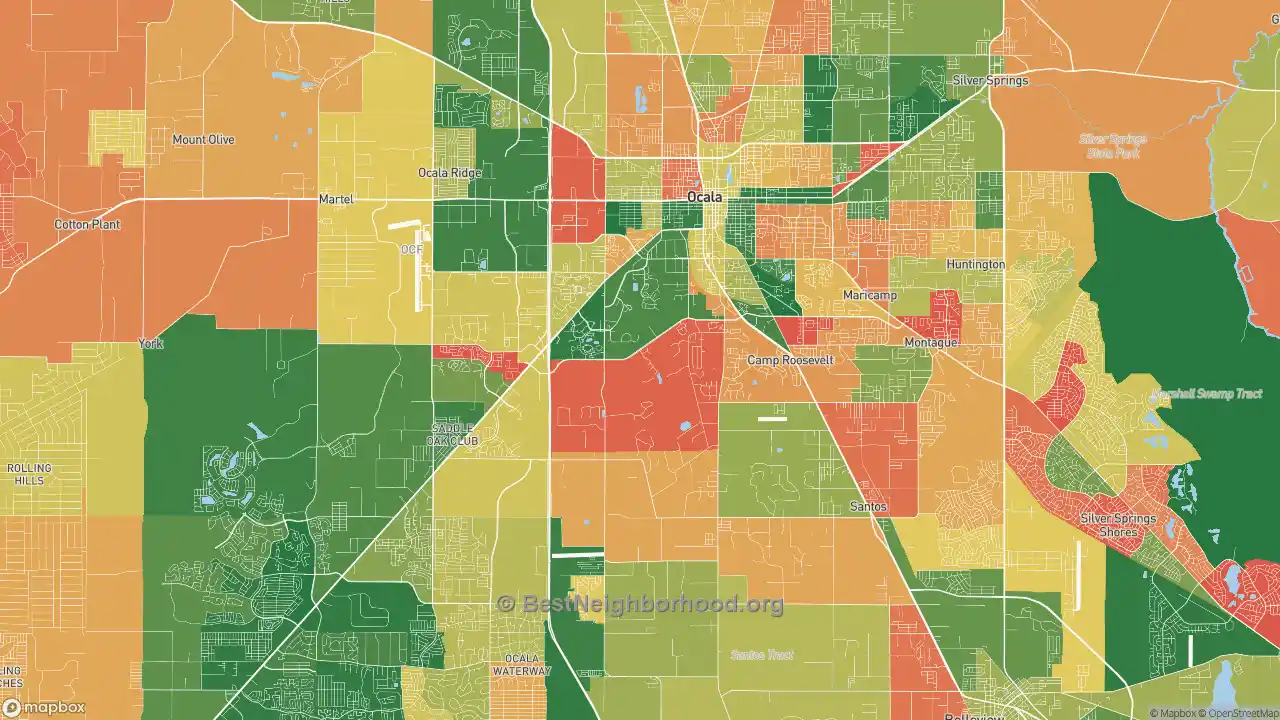
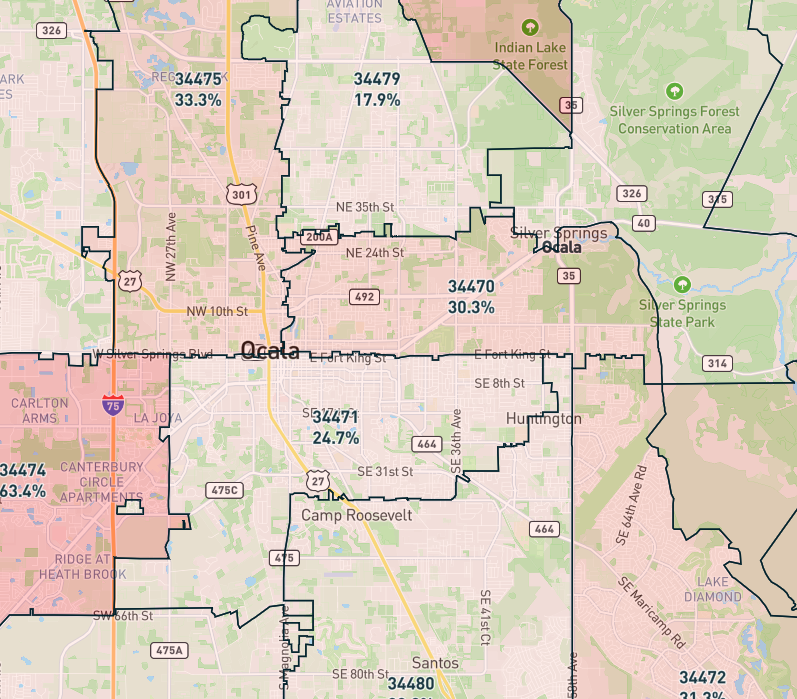
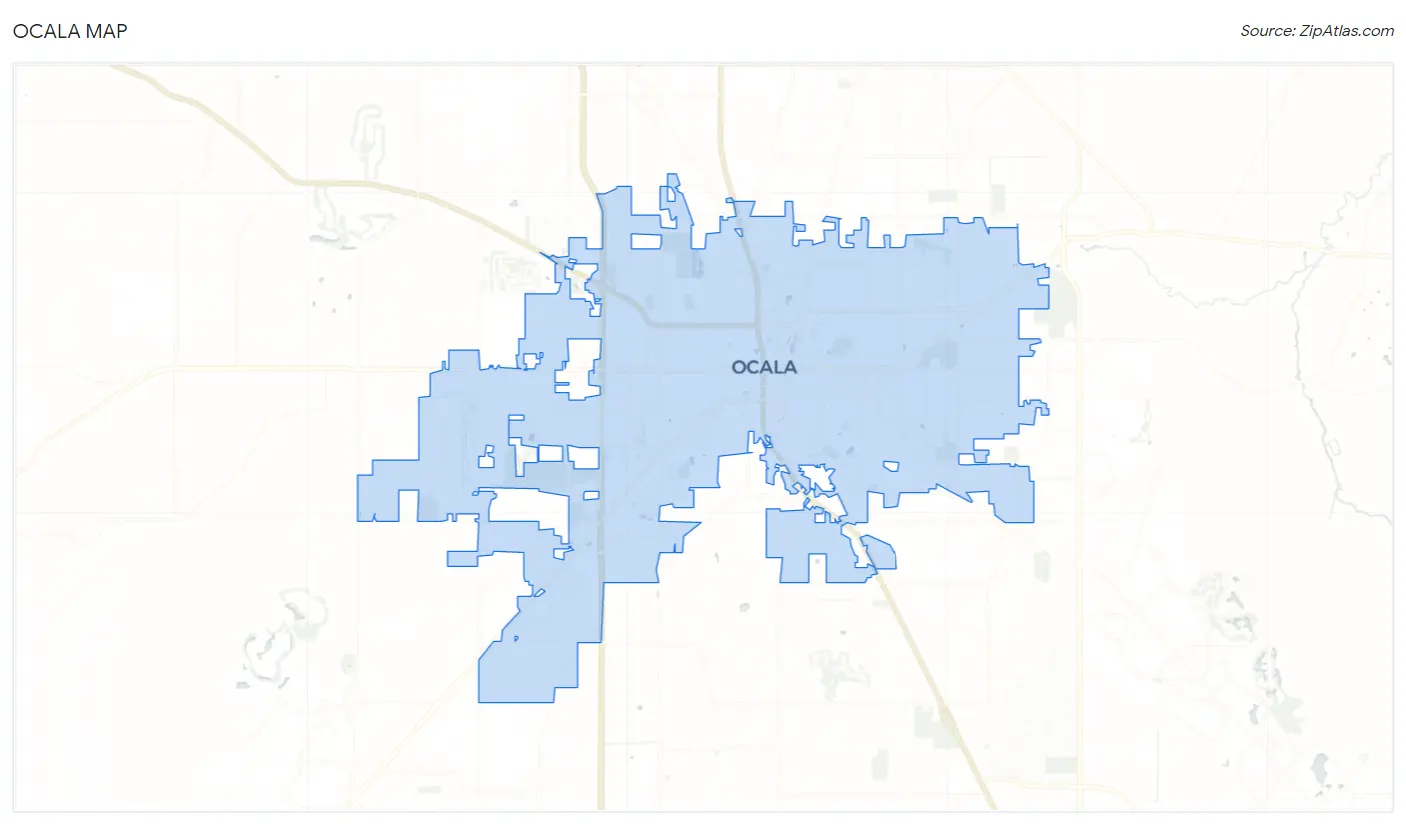
Ocala sits in Marion County, Florida, and its zip code system covers a surprisingly fragmented market. Most people treating this area like a single box are selling themselves short. The zip code 34481 runs north toward Silver Springs and has a different buyer profile than 34480, which overlaps the central business district and older residential cores. 34470 is the newer southern growth corridor where construction starts cluster, and 34471 in the far northwest is entirely different again, with higher acreage parcels and a slower absorption rate. Knowing which boundaries actually matter on the ground is what separates useful analysis from generic reports. When you're pulling data for Ocala, the first thing most people mess up is treating census tract geography as the same thing as zip code geography. They don't align cleanly. You can have a single zip code straddling two distinct census tracts with wildly different median incomes and school ratings. If your analysis stops at the zip code layer, you're missing half the picture. The workaround is simple enough but requires an extra step: map your zip code boundaries to their underlying census tracts using the Census Bureau's crosswalk file, then pull ACS estimates at the tract level instead. It adds maybe twenty minutes to your workflow but makes a real difference in accuracy. I spent three weeks last year working on a portfolio review where every property in question fell within 34481, but half of them were in tract 0419.02 and the other half sat in 0419.03. The published zip code data showed a median household income of about $62,000, but the tract-level breakdown revealed a gap of nearly $18,000 between those two adjacent areas. That $18,000 difference translated directly into a different price ceiling for owner-occupied single-family homes, and I caught it before any offers went out. The buyer thought they were looking at a uniform neighborhood. They weren't.
How Property Values Actually Move in This Market
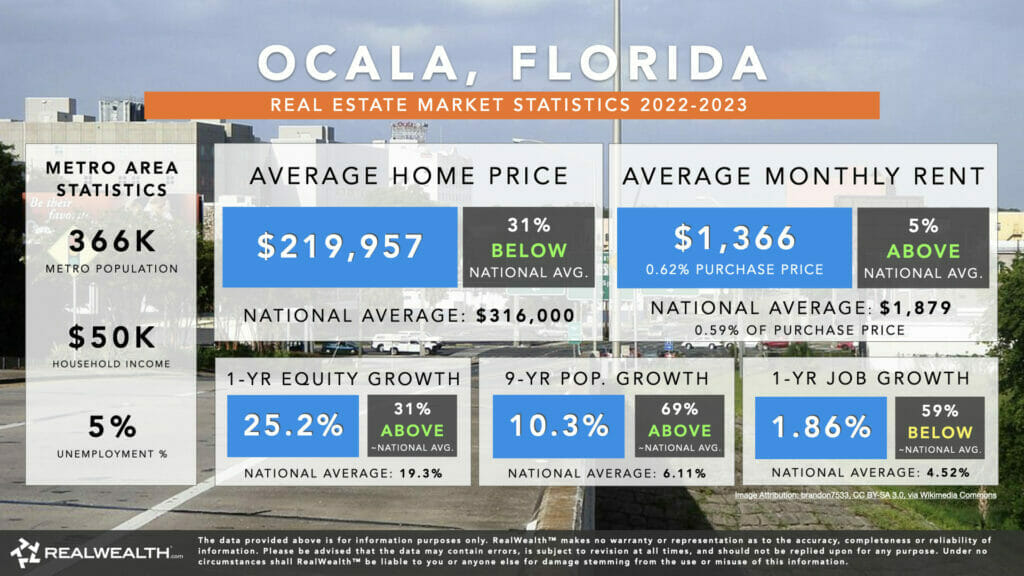
Ocala's housing market doesn't behave like Orlando or Tampa. It's smaller, more locally driven, and far more sensitive to interest rate shifts because the buyer pool skews older and cash-constrained. The median home price in the 34481 area has hovered between $260,000 and $310,000 over the past five years depending on season. Newer construction in 34470 pushes into the $340,000 to $420,000 range, but those homes sit on the market longer during rate hikes because the buyer demographic there relies heavily on conventional financing with tighter debt-to-income thresholds. Here's something nobody puts in the marketing materials: days on market in Ocala correlates more strongly with school district boundaries than with any other single factor. The Marion County Public Schools assignment lines run through several zip codes in uneven ways. A home just two miles from one that's zoned for a higher-rated school can carry a premium of $15,000 to $30,000 purely on that designation. I've seen buyers drive thirty minutes out of their way for a specific school assignment rather than buy closer. It sounds irrational until you talk to the parents making those decisions, and then it makes perfect sense.
Demographic Patterns That Actually Matter
The population breakdown in Ocala's core zip codes skews older than the state average. About 22 percent of residents in 34480 and 34481 are over 65, compared to roughly 17 percent for Florida overall. That matters for property values because it drives demand for single-story homes, lower-maintenance landscaping, and proximity to healthcare facilities. Nearby, 34470 skews younger with families, which explains the stronger demand for three-bedroom minimum layouts and larger lots. Income distribution tells a similar story across these zones. The 34480 zip code has a median household income around $52,000, while 34470 runs closer to $71,000. That 35 percent gap shows up in price per square foot, not just list price. You'll see 34480 properties trading in the $130 to $160 per square foot range for standard condition homes, while comparable homes in 34470 move at $165 to $200 per square foot. These aren't tiny differences. They compound quickly across a portfolio.
Get the Full Details
Practical Steps for Pulling and Using This Data
Start with the Census Bureau's data.census.gov portal. Filter by zip code tabulation area for the four main Ocala codes, then export the ACS 5-year estimates for housing characteristics, income, age distribution, and household composition. Cross-reference those figures against the Marion County Property Appraiser's website for actual assessed values and sale history. The two datasets together give you the full picture: what the area is like statistically, and what it actually sells for transactionally. If you're doing this for investment purposes, add the local Multiple Listing Service data through a service like Attom or CoreLogic if you have access. The MLS feeds show active, pending, and sold listings with price reductions and days on market in real time. Combining that with census tract demographics gives you a view that's roughly three to six months ahead of what most retail investors are working with. Most people just look at the last twelve months of closed sales. That's looking in the rearview mirror.
Where This Approach Falls Apart
The biggest limitation is that zip code and census tract data update on different schedules. ACS estimates roll out every year with a lag, usually for the prior calendar year. Property appraisal data updates continuously but only reflects market value when a sale occurs. In a slow-moving market like Ocala, where some neighborhoods see only a handful of transactions per month, your appraisal-based data can be months old by the time it registers. You're seeing prices from spring when you're analyzing in late summer. Another hard limit: rural edges of 34471 and parts of 34482 outside the urban service boundary don't fit neatly into standard valuation models. These are 5-to-20-acre parcels with septic systems, well water, and variable road access. Their value drivers are fundamentally different from the subdivisions in 34470. Comparable sales are sparse and widely dispersed. The per-acre pricing model breaks down within a few miles because access to paved roads and utility availability swing values dramatically. For these areas, you need to pull individual parcel data from the county GIS and evaluate each property on its own merits rather than relying on aggregate demographic statistics. I ran into this exact problem last year when a client wanted to evaluate three parcels along the 34471 border near the Citrus County line. The aggregate zip code data suggested a stable market with modest appreciation, but two of the three parcels had been on the market for fourteen and eighteen months respectively with no offers. The issue wasn't the broader demographic trend. It was that one parcel bordered a commercial quarry operation and the other had a seasonal water table issue that made the septic system non-compliant under current county codes. Neither of those factors shows up in any demographic dataset. They only show up when you physically walk the property or pull the county engineering records.
What to Do With the Information Once You Have It
Use the demographic and valuation data to build a heatmap. Plot median sale prices per square foot against median household income by census tract for each zip code. The correlation will tell you where the market is value-driven versus where it's status-driven. In Ocala, 34470 shows a strong correlation above 0.75, meaning income is the primary price driver. 34481 and 34480 show a weaker correlation around 0.45, which means other factors like school zones, proximity to Silver Springs, and neighborhood condition play a much larger role than raw income levels. For rental analysis, the same data applies but with a different lens. Look at the ratio of median rent to median home price within each tract. A ratio below 0.4 percent monthly typically indicates a seller's market where buying makes more financial sense than renting. A ratio above 0.6 percent suggests renting is more economical and investor demand may be stronger. In Ocala's current market, most core zip codes sit between 0.45 and 0.55 percent, which is a balanced zone where both strategies work but neither dominates.

Tools and Resources Worth Using
Besides the Census Bureau portal and the Marion County Property Appraiser, the Florida Office of Economic and Demographic Research provides free county and municipal-level data that includes employment projections, population forecasts, and infrastructure spending plans. Those infrastructure numbers matter. When the county plans a road widening or a new water main extension into an underserved part of 34470 or 34482, property values in those immediate corridors tend to appreciate ahead of the construction timeline. I've tracked this pattern across three separate infrastructure projects in the last four years. The appreciation spike averaged about eight percent within twelve months of groundbreaking announcement, not completion. If you're doing this kind of analysis regularly, learning to use QGIS or ArcGIS to overlay parcel data, school boundaries, and census tracts will pay for itself in a single project. It takes about a week of evening work to get comfortable with the interface, but once it's running, pulling a custom map for any Ocala zip code takes roughly fifteen minutes instead of the hour or two it would take by hand.