
NJ Zillow: What Actually Happens When You Try to Buy a House in the Jersey Shore
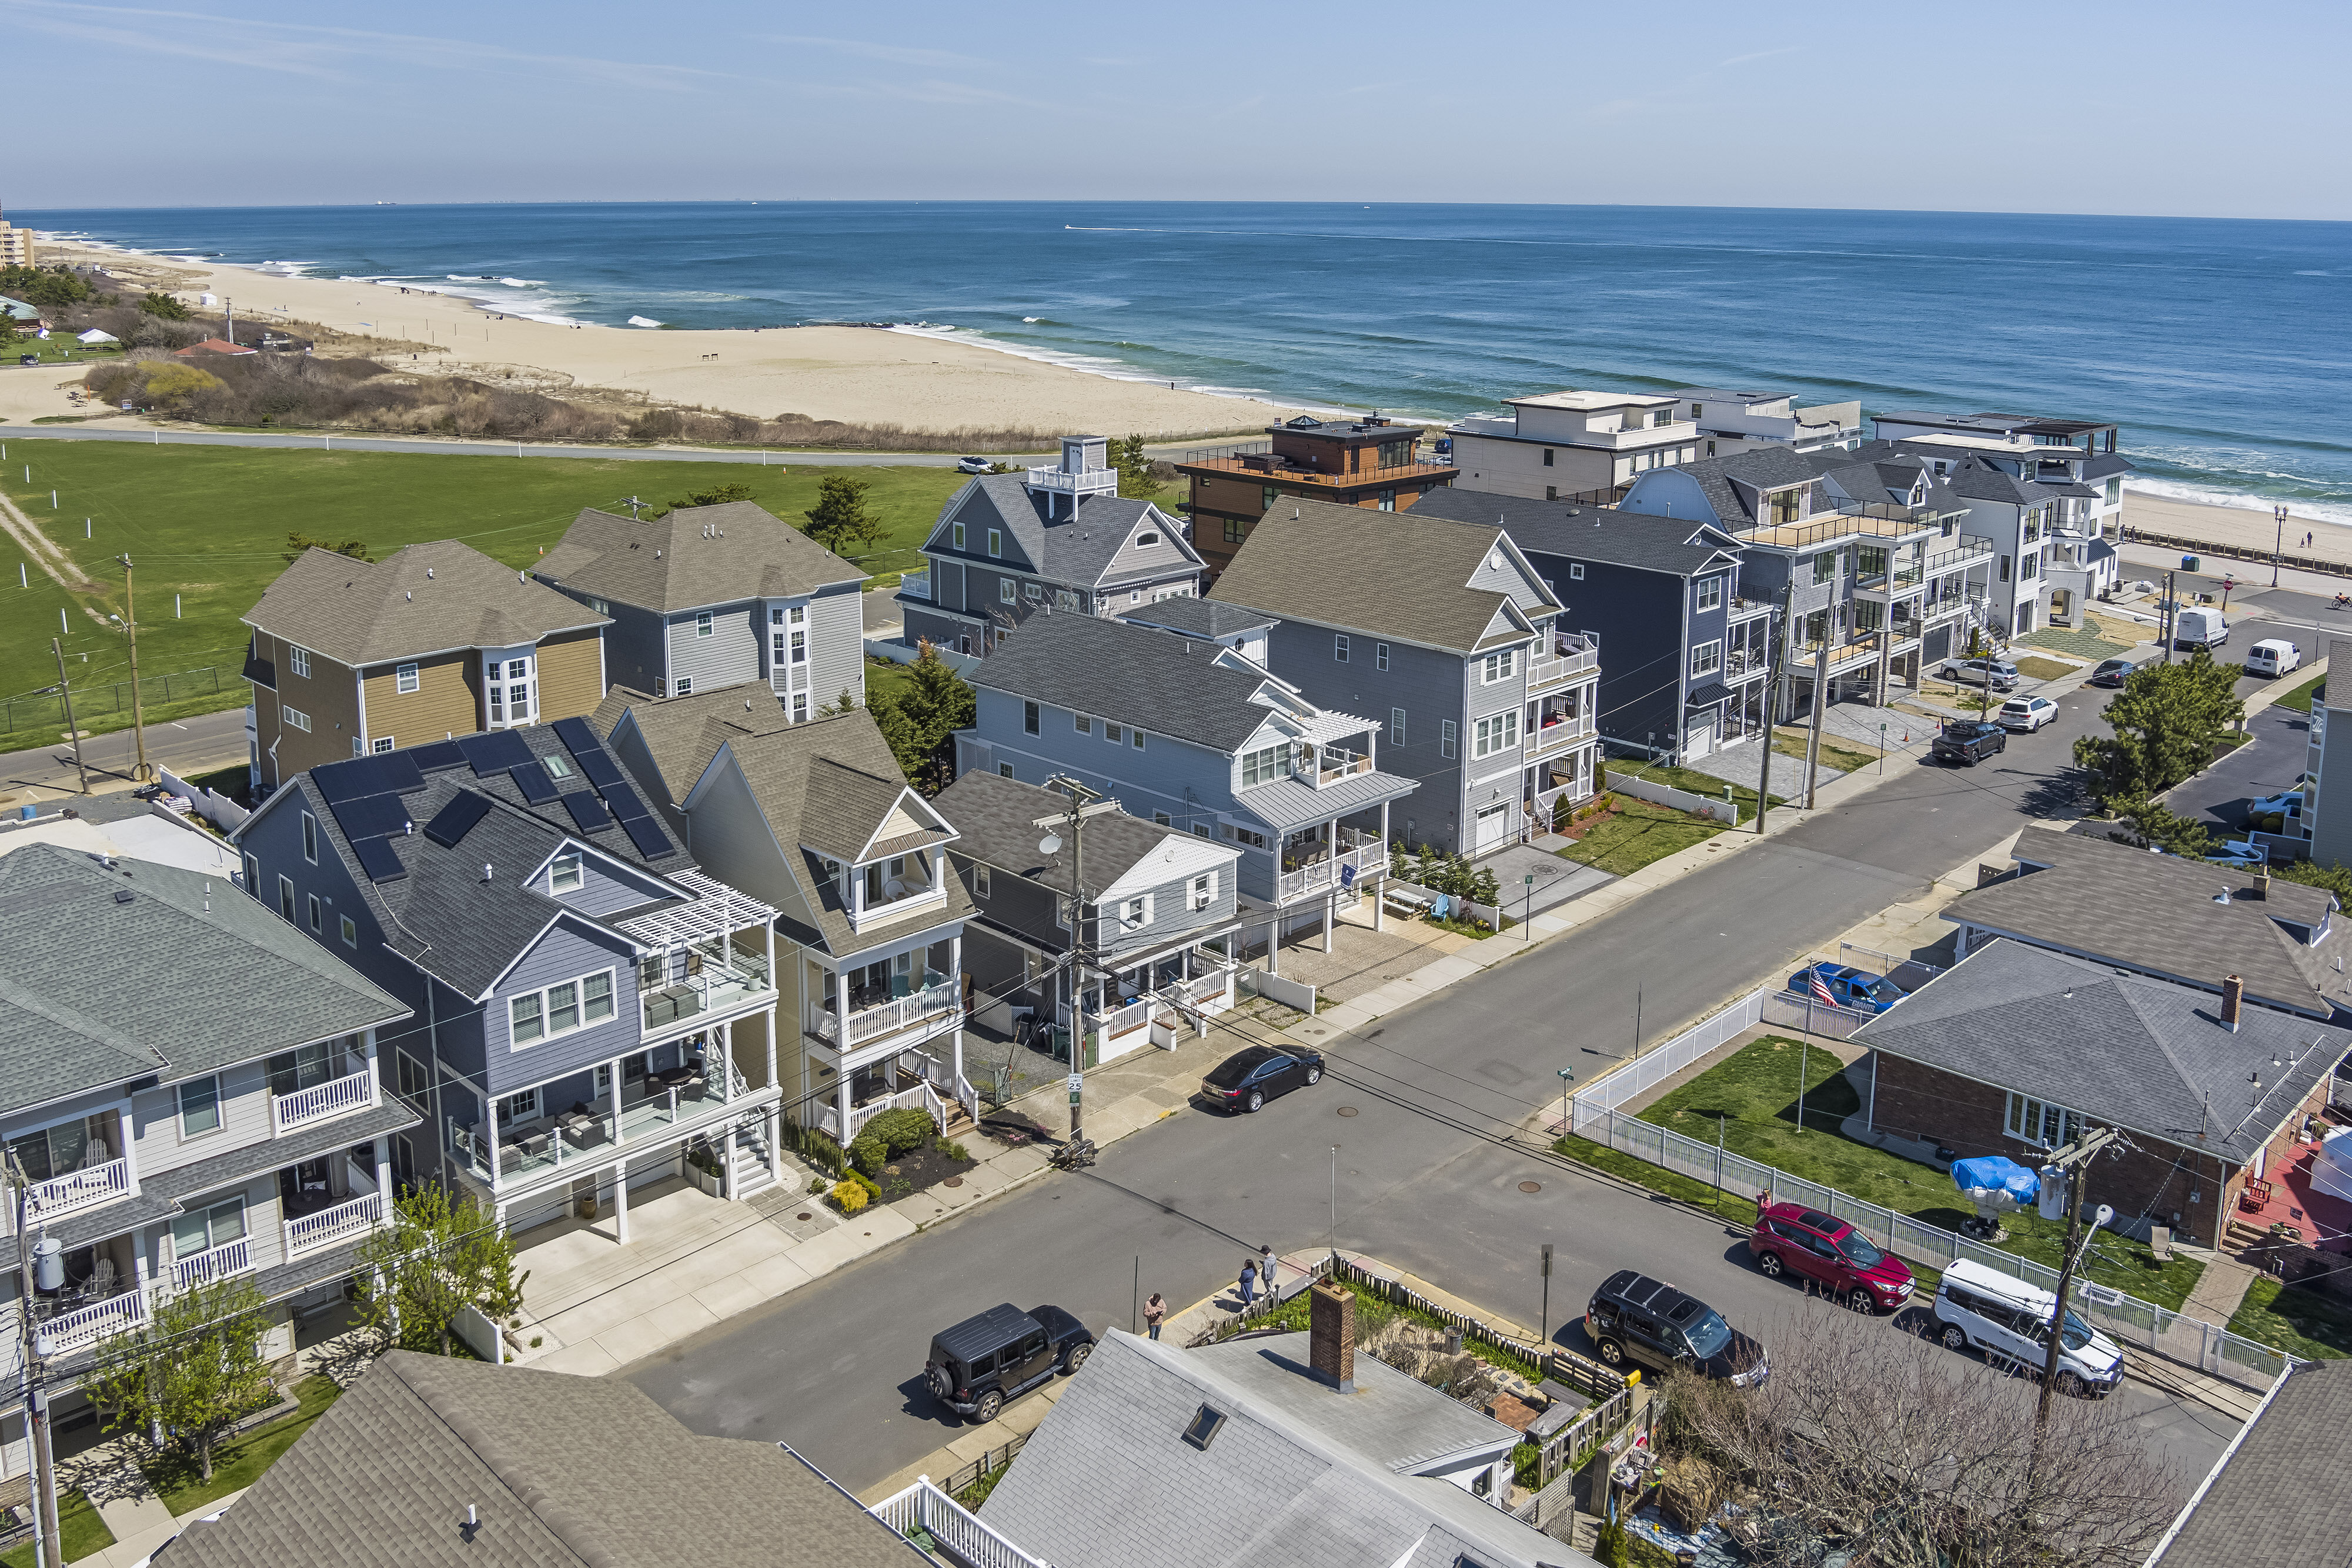
I spent three years working with waterfront properties in Ocean and Cape May counties. You will find that Zillow's listings for New Jersey real estate are not the same thing as the actual market. The platform shows you what sellers want the world to see, not what the property is worth when the inspection comes out. Here is how I actually use Zillow when a client is serious about the Jersey Shore. First, you go to zillow.com and put in your target town. Say you are looking at Avalon or Stone Harbor. You filter for single-family homes, set a price range, and hit search. The results you get are called "listed homes" and they pull from the Jersey Shore MLS through a data feed. But the feed updates once per day, sometimes less. A house that went under contract on Monday might still show as "available" on Tuesday because the listing agent has not updated the status. I always cross-reference with a real-time service like PropertyShark or the county clerk's deed records. This takes about ten minutes and prevents you from falling in love with a house that sold six days ago. My wife once spent two weekends driving up and down Route 9 between Wildwood and Cape May seeing homes that were already escrowed. We laughed about it later, but back then it was expensive and stressful.
How Zillow Estimates Work (And Why They Are Wrong)
Zillow shows a number called the "Zestimate." It is an algorithm, not an appraisal. For Jersey Shore properties, the error margin is usually plus or minus twelve percent. That means a Zestimate of five hundred thousand dollars could be worth anywhere from four hundred forty thousand to five hundred sixty thousand. In the current market, that difference changes whether you can afford the closing costs or not. The algorithm uses recent sales, square footage, and bedroom count. It does not account for elevation, flood zone status, or roof age. These three things matter more than anything else when you are buying coastal property in New Jersey. I had a buyer once who thought he was getting a deal because the Zestimate was thirty thousand dollars below asking. The house sat in Flood Zone AE with a foundation that needed piers. The total repair estimate came to eighty-two thousand dollars. He walked away in the end, which saved him about a year of headaches.
Step By Step Process for Using Zillow in NJ
Step one is setting up alerts. Go to the Zillow app on your phone, save a search, and turn on push notifications. You want to know within the first hour that a new listing hits the market. In competitive areas like Long Port or Northfield, houses move fast. The good ones get ten offers before the weekend. Step two is learning the neighborhood codes. Zillow uses broad labels like "Greater Atlantic City" or "South Jersey Shore." These do not tell you much. I keep a spreadsheet with zip codes, municipality names, and whether the area is in a special flood insurance zone. If a listing says "Wildwood Crest" but the address is actually in the 08260 zip code, you need to verify the flood risk separately. The difference between Zone X and Zone VE changes your insurance premium by two hundred dollars a month. Step three is reading the listing notes. Sellers or agents often hide important details in the description. I look for phrases like "as-is," "sold in current condition," or "no disclosures provided." These mean the seller will not fix anything and may not tell you about past water damage. I have seen this happen in every borough between Seaside Heights and Beach Haven. The workaround is to request the seller disclosure form before you waive your inspection contingency. If they refuse, you walk away. It is not worth the risk.
Get the Full Details
Common Mistakes People Make
Most buyers think the listing price is the starting point for negotiation. In New Jersey, that is rarely true. The actual negotiation starts after you submit an offer, and the terms you include matter more than the number. I always advise my clients to put in a clean offer with no contingencies other than inspection and financing. The seller gets five offers and picks the one with the fewest strings attached. Another mistake is ignoring the HOA. Many Jersey Shore communities have homeowners associations with strict rules about short-term rentals, fence height, and landscaping. Zillow listings rarely mention these restrictions. You have to dig into the HOA documents, which the listing agent should provide but often does not. I spent an afternoon trying to buy a condo in Somers Point only to find out the HOA banned any renovation over five thousand dollars. That killed the project because I wanted to replace the deck. I stopped looking for properties in that particular HOA after that.
When Zillow Fails You Completely
There are situations where Zillow will not help you at all. One is off-market properties. In the Jersey Shore, many sellers never list on the MLS. They sell to neighbors, to relatives, or through word of mouth. If you are looking in expensive enclaves like Brigantine or Absecon Island, you will miss half the available homes if you only use Zillow. Another situation is foreclosure and tax lien sales. These do not show up on Zillow in a useful way. The county courts publish lists, but the format is terrible. I use a service called DriveWealth or just go directly to the county clerk's office. It takes about twenty minutes to get a PDF list of upcoming auctions. You then call the listing agents directly to ask about property condition. Zillow does not have this data at all.
Practical Numbers You Should Know
Buying a house in New Jersey costs more than the purchase price. The transfer tax alone is one point zero three percent of the sale price. If the house sells for four hundred thousand dollars, you pay about four thousand one hundred twenty dollars in transfer taxes. The title insurance is another twelve hundred dollars. Attorney fees run about eighteen hundred dollars because New Jersey requires you to have a real estate lawyer for closing. Inspection costs eight hundred to twelve hundred dollars depending on the size of the home. Appraisal runs five hundred dollars. Total closing costs usually land between three and five percent of the purchase price. If you are financing with a conventional loan, you need a down payment of at least three percent. That means on a four hundred thousand dollar home, you need twelve thousand dollars at closing. Plus the costs above. Most people come in with about twenty-five thousand dollars in cash ready. If you are looking at luxury properties over one million dollars, the numbers scale up linearly.

Final Thoughts
Zillow is a tool, not a solution. It gives you a starting point, not a strategy. The Jersey Shore market moves fast, floods are real, and the paperwork is thicker than in most other states. You need to combine Zillow with county records, local knowledge, and a good attorney. That is how I have done it for three years without losing money on bad deals. If you want a quick summary, go to zillow.com, set up alerts, read the flood zone maps at fema.gov, and call a local agent who actually lives in the county you are buying in. Anything else is just wasting your time.


