Getting Your New Jersey State Refund Right
New Jersey tax season is its own animal. The state uses its own forms, its own definitions for income, and its own set of credits that don't always line up with what you did on your federal return. A lot of people file NJ returns on autopilot after finishing their federal paperwork, and they leave money on the table or make mistakes that trigger audits. I've seen it too many times. The first thing you need to understand is that New Jersey defines taxable income differently than the IRS does. Your federal adjusted gross income is a starting point, but then NJ adds back or subtracts certain items. Social Security benefits, for example, are generally excluded from NJ taxable income even though they're included federally. That's one of the easier wins people miss. Then there are the credits. New Jersey's Earned Income Tax Credit matches the federal credit but uses state-specific income limits, which are different. If you qualify federally, you almost certainly qualify at the state level, but the amount can vary. The state also offers a renter's property tax credit, a homeowner's property tax credit, and various pension/retirement income exclusions. Each has its own eligibility rules and phaseout thresholds.
I spent a couple of years helping people with NJ returns at a free tax clinic, and one thing stuck with me. There was this one guy in his sixties who'd been claiming the full pension exclusion every year without checking whether it actually applied to his situation. His pension was partially taxable at the federal level because he'd made after-tax contributions to his plan. New Jersey allows you to exclude up to $100,000 of pension and retirement income, but only the portion that's actually taxable matters for the calculation. He was excluding too much, which triggered a correction notice from the state. It turned into a three-month headache. The fix was straightforward once we pulled the correct forms, but the point is that people assume the exclusion is automatic when it isn't.
Where People Mess Up
The most common mistake is treating the NJ return as a mere echo of the federal return. You can import federal data into your software, sure, but you have to review every line. NJ has add-backs for things like municipal bond interest from other states, and it has subtractions for things like military pay in certain cases. If you just accept the auto-populated numbers without looking, you'll file with errors. Another frequent issue is the property tax credit. New Jersey residents who rent and pay property tax through their landlord are eligible for a refundable credit, but you have to meet residency requirements and income limits. I had someone try to claim it last year after moving into a new apartment in March. The credit requires you to have been a resident for the entire tax year, so he was ineligible. We caught it before filing. If you've moved during the year, the prorated nature of your residency matters, and the credit usually isn't available unless you were a resident for all twelve months. Withholding is another area where people get tripped up. New Jersey allows you to designate a percentage of your refund to go to the Volunteer Firefighters' Benefit Fund or the Emergency Medical Relief Fund. These are donations, not credits. They reduce your refund dollar for dollar. Some people select them by accident when filling out the form quickly, and then wonder where their money went. Check the schedule. Make sure those boxes are empty unless you intentionally want to donate.
Get the Full Details

The Process That Actually Works
Start by gathering your W-2s, 1099s, and any documentation for deductions or credits you plan to claim. If you itemized federally, you don't necessarily need to do the same for NJ, but you should compare. New Jersey's standard deduction is lower than the federal one in most cases, so itemizing might make sense if you have significant property taxes or mortgage interest. But here's the catch: New Jersey caps certain itemized deductions. SALT deductions are limited, and the threshold for itemizing is lower than federal, so the math needs to be done on the NJ schedule specifically, not assumed from your federal work. Use the NJ Division of Taxation's own worksheets or a reputable tax preparation tool that's specifically calibrated for New Jersey. Generic software that only handles federal returns won't cut it. If you're doing this manually, the instructions for Form 1040NR are essential reading. They're not long, but they contain the nuances that matter. When you enter your numbers, cross-reference every line with your federal return. Look for discrepancies. If your federal AGI is different from what the software calculated for NJ gross income, investigate why. Add back any municipal bond interest from other states. Subtract any military pay if applicable. Adjust for the pension exclusion carefully, making sure you're not excluding nontaxable portions.
Credits That Are Worth Pursuing
Beyond the EITC, New Jersey offers a property tax credit for renters that can refund up to $525 depending on income. Homeowners can get a similar credit, and the amounts are higher. The eligibility is income-based, with phaseouts starting at relatively modest levels, so check the tables in the instructions. If you qualify, it's essentially free money that reduces your tax liability or increases your refund. There's also the exempt organization bond interest exclusion, which applies if you received interest from bonds issued by New Jersey or local municipalities within the state. That interest is taxable federally but exempt for NJ purposes. Claiming it correctly can lower your state taxable income without affecting your federal return. One less-known credit is the one for elderly or disabled taxpayers. If you're 65 or older, or permanently and totally disabled, you may be eligible for an additional exclusion from income. The income thresholds are specific, and the form to claim it is separate. I've seen people overlook this because they assume their income is too high, but the phaseout range is wide enough that mid-income earners can still benefit.
Timing and Submission
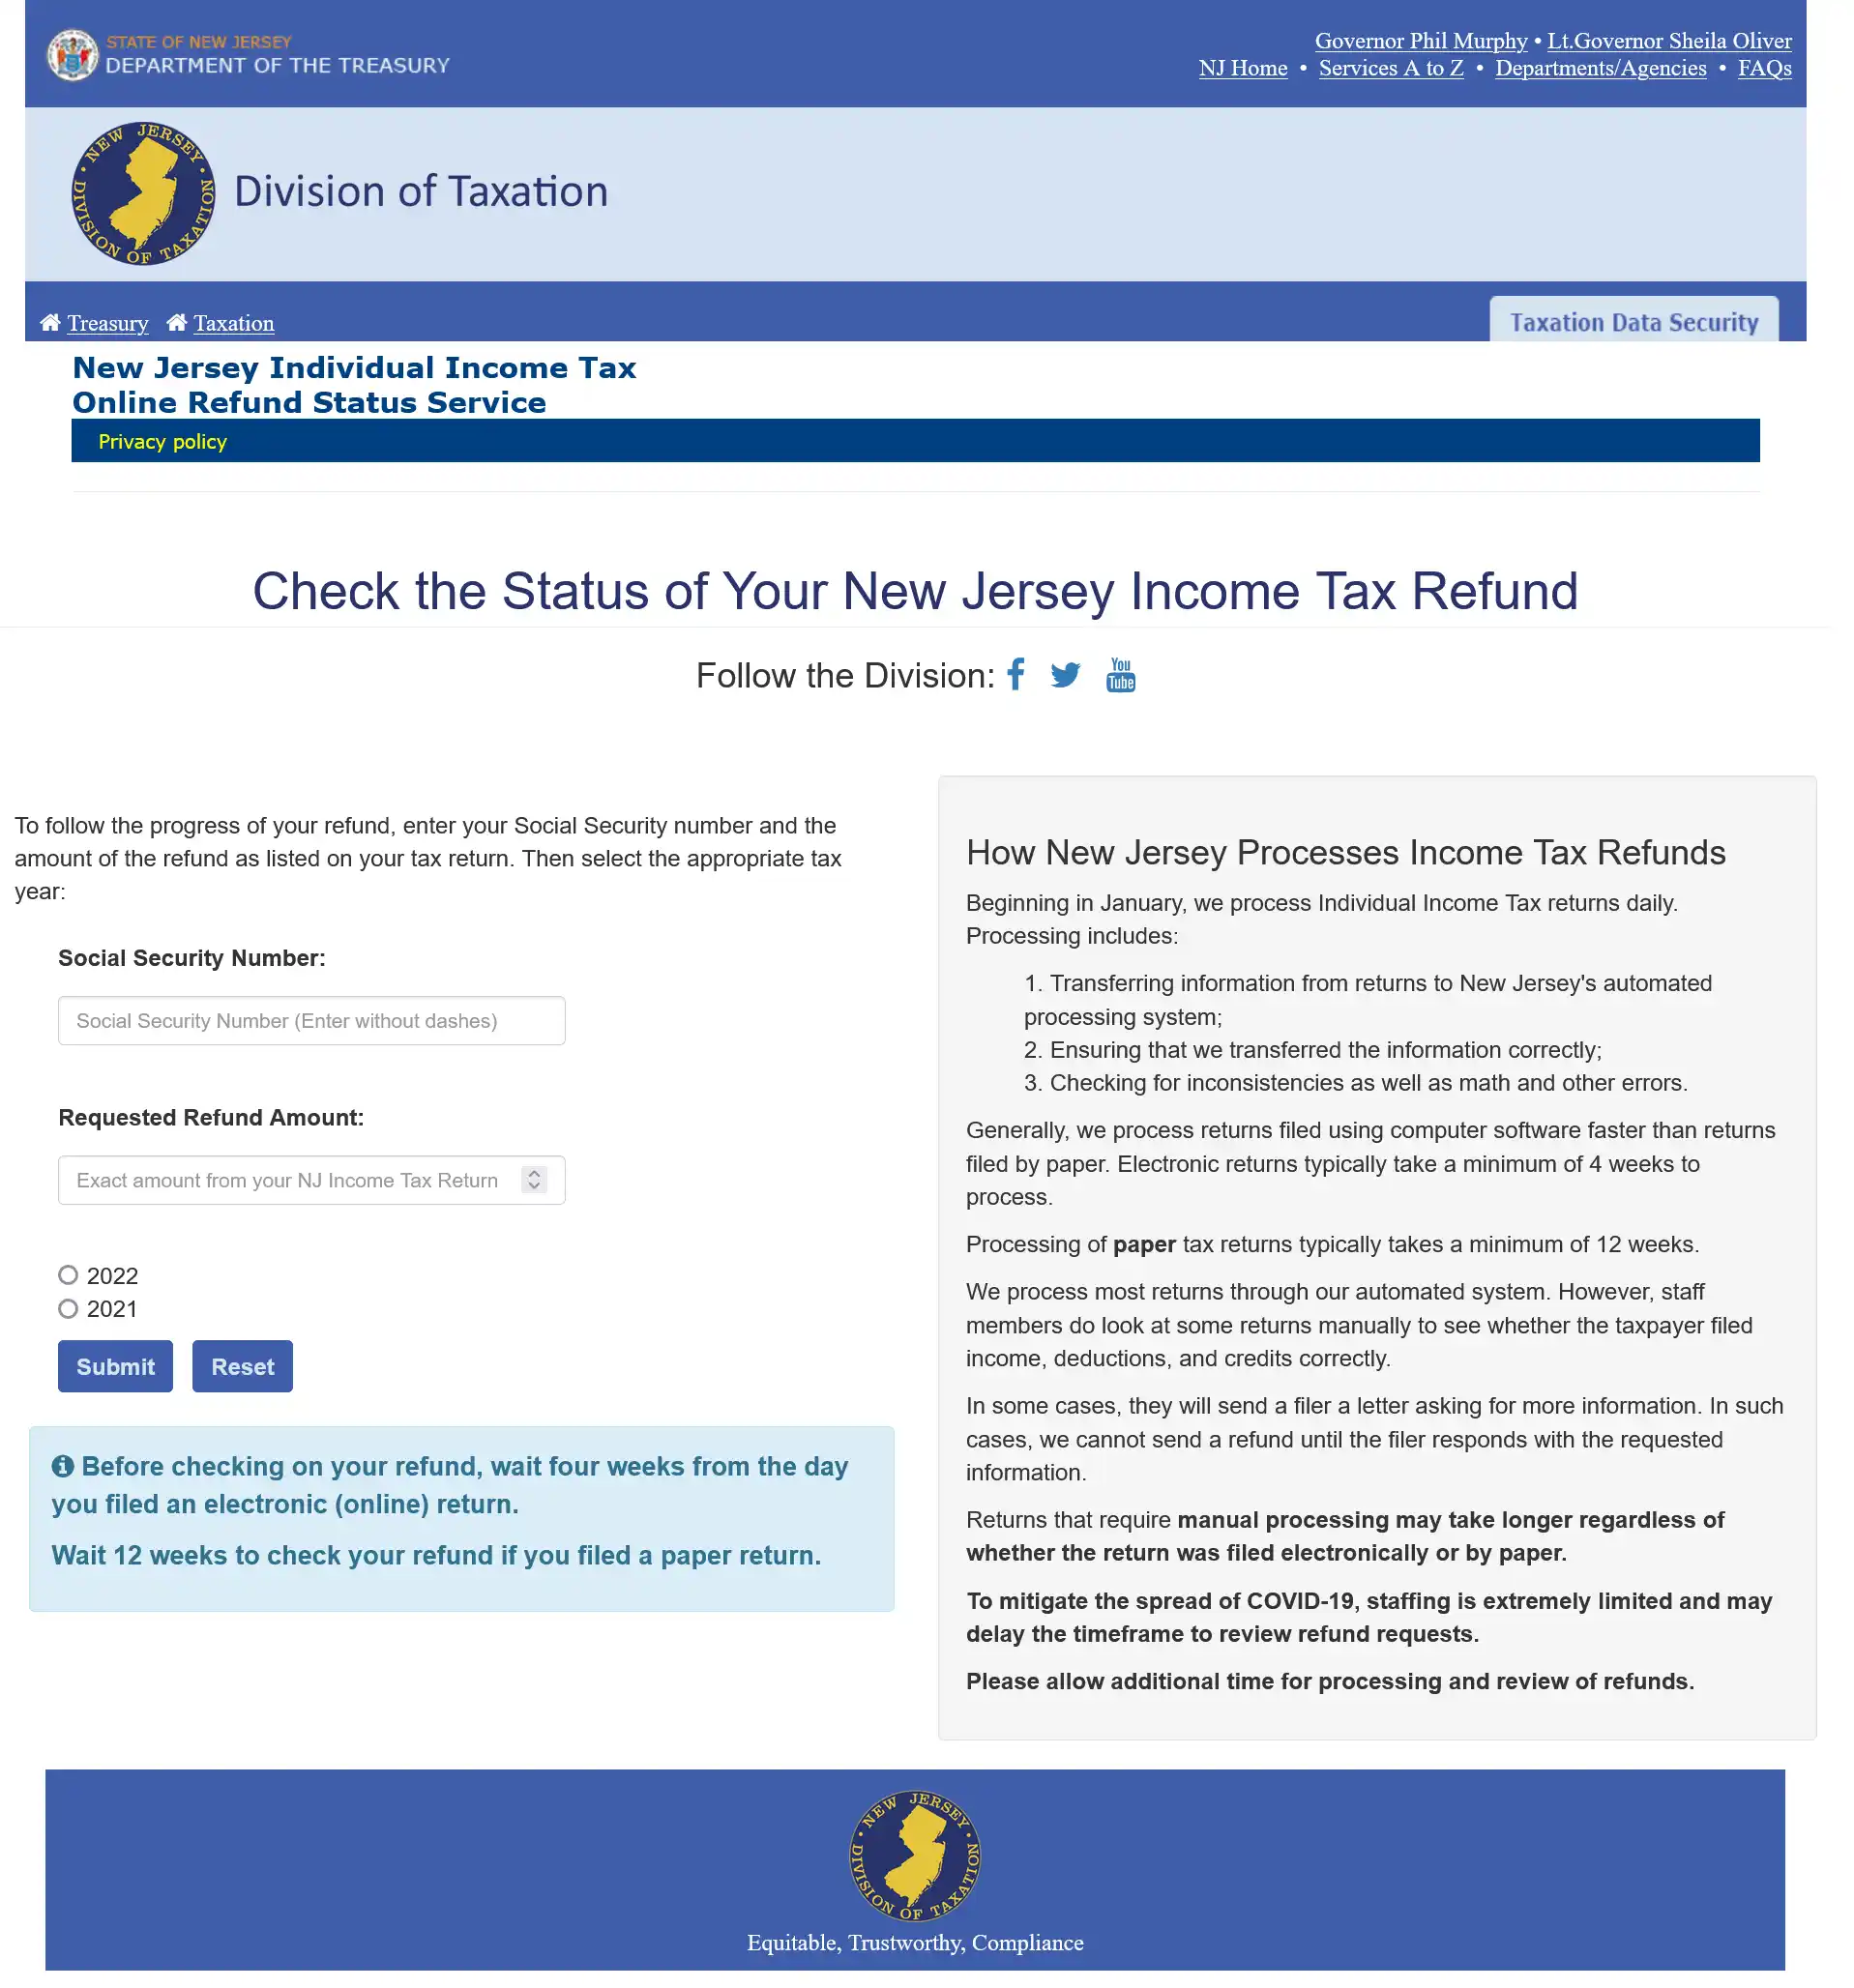
The filing deadline is April 15, same as federal, unless it falls on a weekend or holiday. New Jersey doesn't have a separate extension process that's meaningfully different from the federal one, but if you need more time, you should file Form 4450 for an extension. This gives you until October 15. Interest on unpaid taxes accrues from the original April deadline regardless, so an extension only buys you time to file, not time to pay. If you're owed a refund, filing electronically speeds things up considerably. Direct deposit is the fastest way to receive it. Paper checks can take six to eight weeks from the time the return is processed. The state's online portal lets you check the status of your refund, which is useful if it's been more than ten weeks since you filed and you haven't received anything.

When Things Go Wrong
Errors happen. If the state sends you a notice, don't ignore it. Many notices are automated and can be resolved with a simple response or corrected form. Some people panic and do nothing, which makes things worse because penalties and interest accumulate. Read the notice carefully. It will tell you exactly what the issue is and what you need to provide. I dealt with a case where someone received a notice about a mismatched Social Security number. The name on the return didn't match the SSN in the state's system. It turned out the person had recently changed their name and updated it with the SSA but hadn't updated their NJ withholding information. The fix was submitting a copy of the SSA card and a brief explanation. It took about three weeks to resolve. Ignoring it would have resulted in a refund offset and possible fraud referral. Another scenario is overpayment. If you had too much withheld throughout the year, your refund will be larger, but that's essentially an interest-free loan to the state. Adjusting your NJ withholding allowances on your W-4 can prevent this in future years. Check your pay stubs and recalculate if your refund has been consistently over $2,000 when your tax liability was much lower.
What Doesn't Work
Don't assume that because you got a refund last year, the same strategy will work this year. Life changes affect everything. A raise, a new job, a house purchase, a divorce, a child born. Each of these events can change your filing status, your deductions, your credit eligibility, and your withholding. Filing the same way year after year without re-evaluating is how mistakes compound. Also, don't fall for gimmicks. There are services that promise to maximize your refund through questionable deductions or creative interpretations of the law. Stick to legitimate credits and deductions. TheNJ Division of Taxation has published guides and FAQs that cover most situations, and the state's website has a calculator tool that can give you a rough estimate before you file. New Jersey tax law changes occasionally, so verify that the forms and instructions you're using are current for the tax year you're filing. Older PDFs floating around from previous years might have different thresholds or eliminated credits. Always download the latest version from nj.gov/taxation.