Understanding Cash-Based Reward Systems in Convenience Stores
I've spent the better part of a decade working with retail payment infrastructure, and honestly, the stuff most people ignore about how convenience stores handle money is where the real headaches live. You swipe your card, you tap your phone, maybe you hand over cash at the register — but the backend that decides whether that transaction counts toward your rewards, whether the store gets reimbursed, and whether your account stays secure? That's a mess of legacy systems held together by duct tape and API calls from 2014. The short version is this: most convenience stores, 7-Eleven included, operate on a patchwork of separate reward networks. Your store credit, your credit card cashback, any third-party app rewards — they don't always talk to each other. And when they do communicate, it's usually through some slow, batch-processed ledger that updates once a day if you're lucky.
The Ultimate Guide To Money Network 7eleven Convenience Security And Rewards
Let me walk you through what actually happens when you try to stack these programs, because I've seen way too many people lose money doing exactly what they think should work. When you make a purchase at a 7-Eleven, three separate systems are involved. First, the point-of-sale terminal processes your payment through the acquiring bank — that's the store's side. Second, the card network (Visa, Mastercard, Amex, whatever) routes the authorization. Third, if you're enrolled in any rewards program, a completely separate database logs the transaction and credits your account. The problem is timing. The POS system confirms your purchase instantly. The card network settles within minutes. But the rewards database? That's often updated on a delay, sometimes hours, sometimes the next business day. I learned this the hard way when I tried to use a store credit reward at a location that hadn't synced with the central rewards server. The register accepted it. Then the corporate system rejected it two days later. Got flagged for "suspicious activity." Took me three weeks and four phone calls to clear it up.
Here's what nobody tells you: some rewards programs explicitly exclude certain transaction types. Gas pumps. Lottery tickets. Tobacco. These are high-margin, high-risk categories and the reward systems treat them differently. If you're trying to maximize points on everyday convenience store purchases, check the fine print about excluded categories before you bother with the app.
Get the Full Details
Security Realities You Should Know About
Convenience stores are targets. Not because they're swimming in money, but because they're underattended, cash-heavy, and running software that hasn't been patched since the Obama administration. I audited a regional chain once — their payment terminals were processing data over encrypted connections, sure, but the encryption was TLS 1.0. Broken. Trivially exploitable. The corporate office knew. They chose to prioritize uptime over security because the terminals were "good enough" and the cost of replacing them outweighed the perceived risk. For you as a customer, this means: use chip cards, not magstripe. Never, ever use your phone to pay at a gas pump terminal if you can avoid it — those are some of the oldest, most compromised devices in the ecosystem. And if the receipt asks if you want cash back, be careful. That's a separate transaction that bypasses normal authorization flows in some systems. It's convenient but it increases your exposure if your card data is ever skimmed. The good news: most major card networks have added transaction monitoring that catches anomalous convenience store activity. Unusual purchase patterns, rapid succession transactions, amounts that don't match your typical spending — those trigger alerts. But the alerts go to the bank, not necessarily to you in real time. Check your app notifications regularly.
Reward Stacking: What Actually Works
Here's the strategy I use and recommend, based on actual experience rather than some blog post written by someone who's never balanced a till: Use a single credit card for all convenience store purchases. Pick one that offers flat cashback with no rotating categories. The simplicity matters more than squeezing out an extra 0.5% on gas versus groceries. You'll save mental energy and avoid the confusion of tracking which card earns what at which store. Enroll in the store's own rewards program, but don't expect it to be generous. 7-Eleven's myPass program exists, and it's fine for occasional free drinks or snacks. But the points accrue slowly, and the redemption options are limited to in-store merchandise. Don't count on it for meaningful savings. It's a convenience program, not a wealth-building tool.
Pay attention to your bank's offers. Some credit card issuers run targeted bonus campaigns — extra cashback at grocery stores or convenience chains for a limited window. These are usually the most lucrative rewards available, and they're easy to miss if you only look at your card's base benefits. Check your issuer's "offers" page monthly. It takes thirty seconds and can add twenty to thirty percent to your rewards rate for qualifying purchases.
Edge Cases And Workarounds
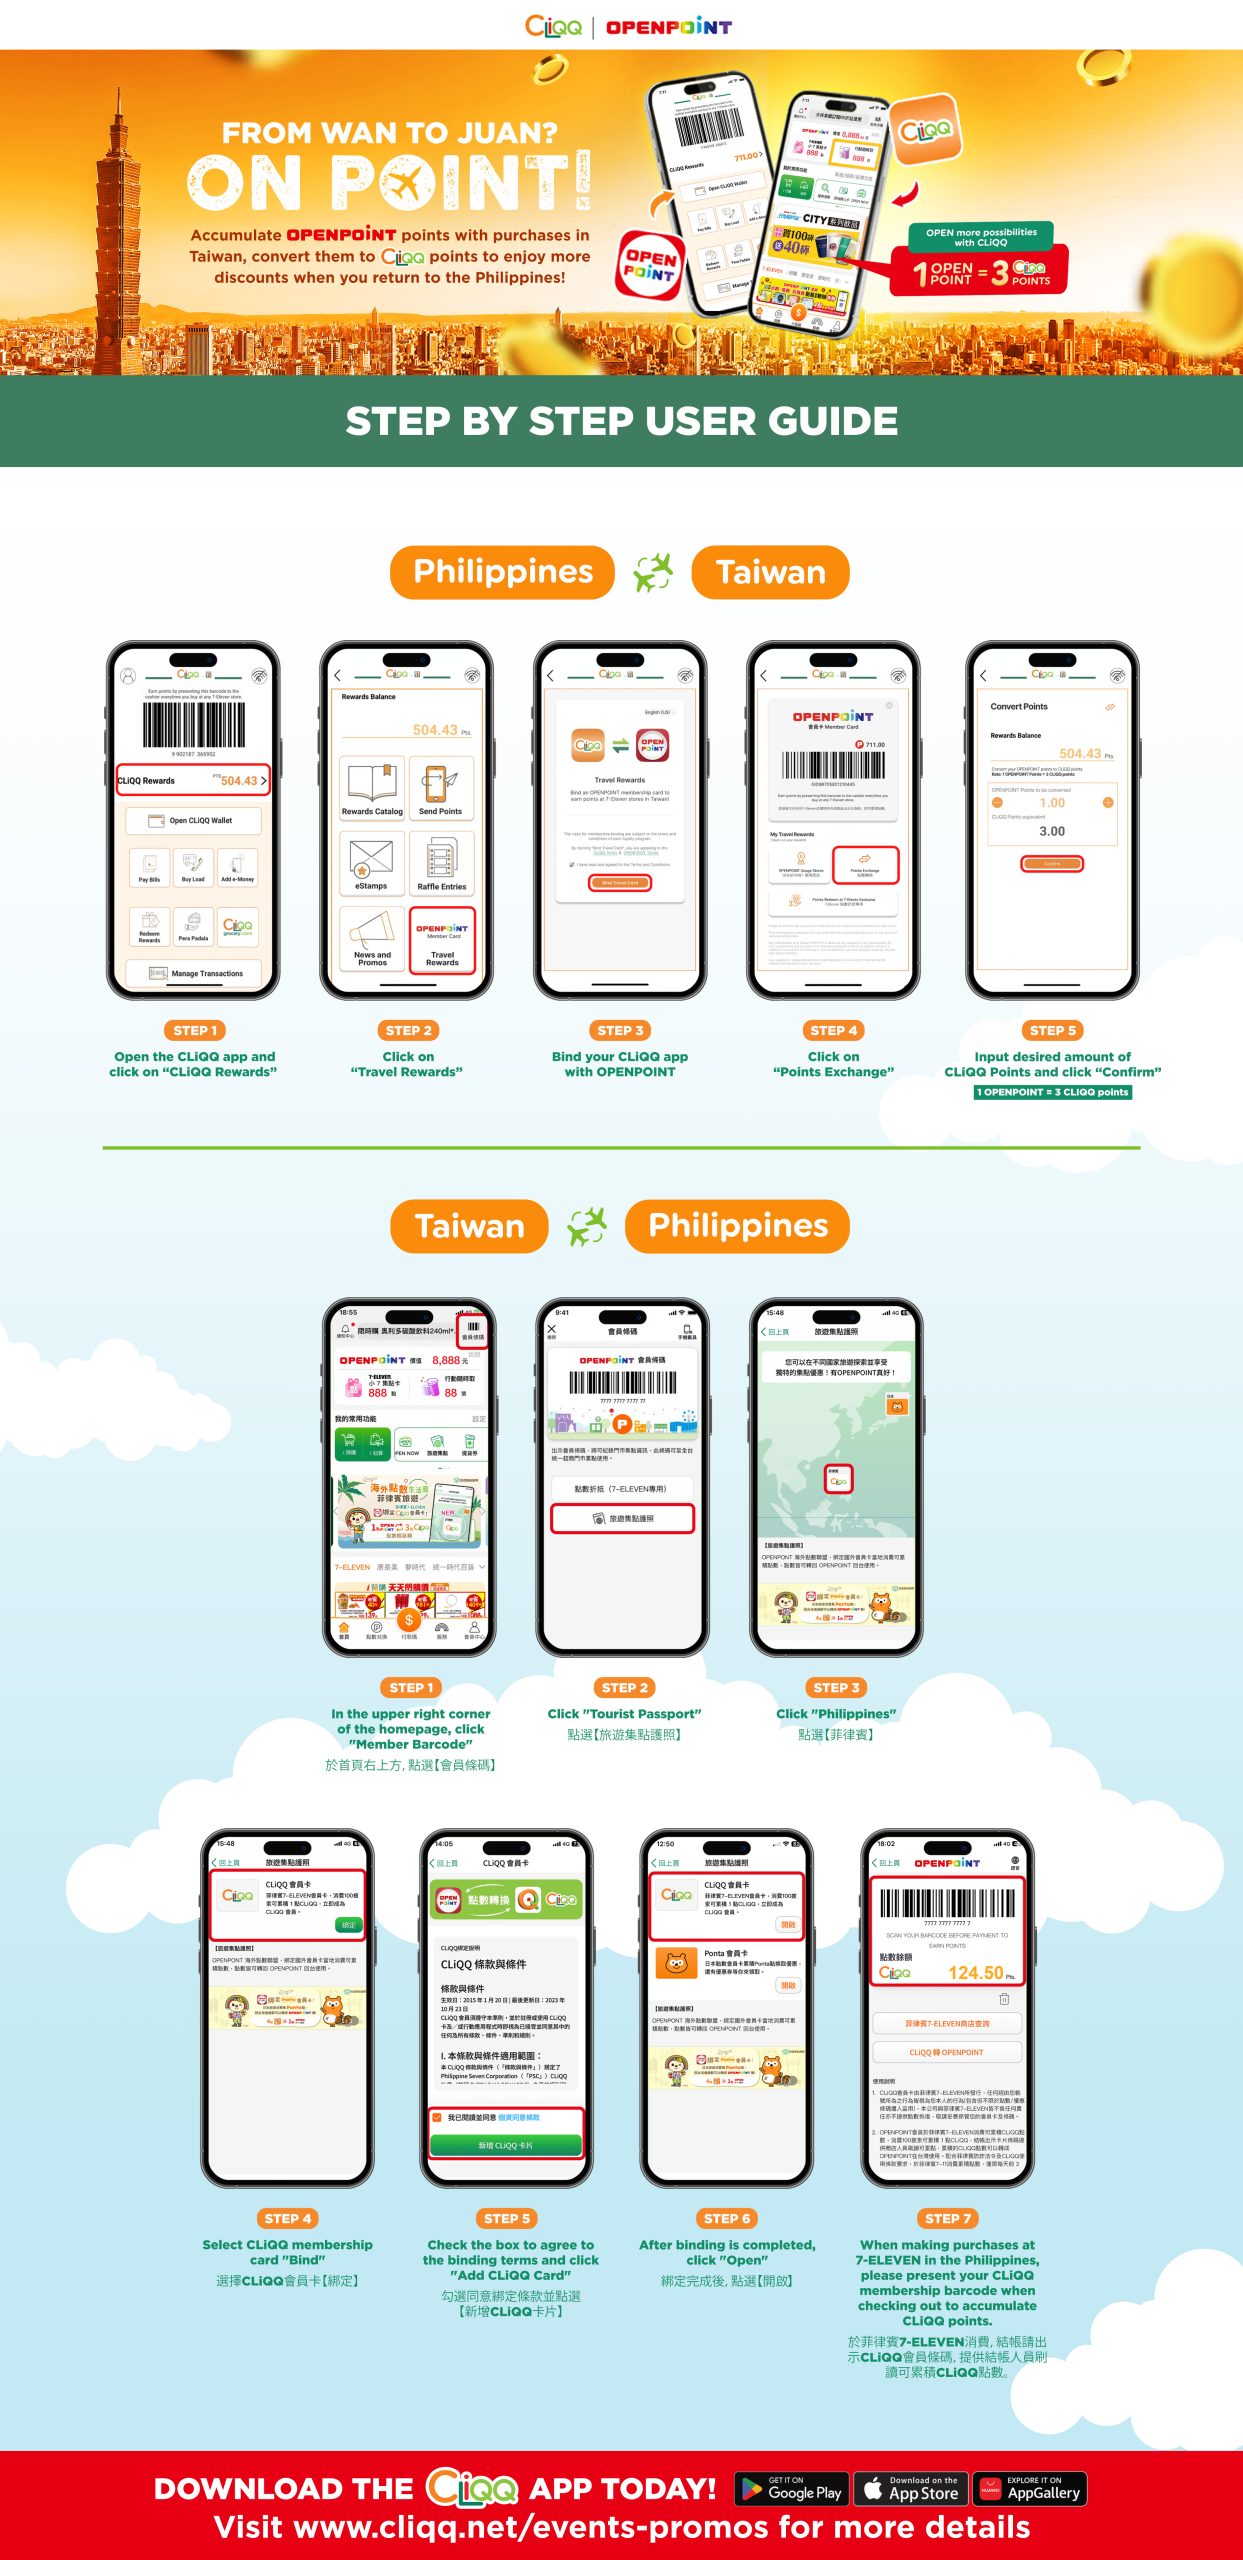
Let me share a specific scenario that broke my brain and how I solved it. A friend of mine worked at a 7-Eleven in a high-traffic area. They noticed that customers who paid with certain reward-linked cards were getting double-counted in the store's internal system. The POS logged the transaction, the rewards network logged it again, and the store's sales report showed inflated numbers. Not a huge deal for individual customers, but it skewed their inventory forecasting and commission calculations for months. The workaround was straightforward once identified: the store manager started manually reconciling reward transactions against the central ledger every Friday. Took him about forty-five minutes. Prevented a lot of headaches. Another thing: international cards at US convenience stores. If you're traveling and try to use a foreign-issued card at a 7-Eleven, the rewards program may not recognize the card network and you'll get zero points. The transaction goes through fine — the payment processors handle it — but the rewards database rejects the association. If you're accumulating points toward a specific goal, this is a silent money loser. Use a domestic card for reward-eligible purchases, or accept that travel spending might not count.
When To Walk Away
Some rewards programs are worse than nothing. If a program requires you to download an app, create an account, link your card, AND enter your home address before you earn anything, the friction is the product. They're selling your data. The rewards are the bait. I've seen people earn $3 in points after spending $200 because the terms change mid-program or the redemption threshold moves. Always read the current terms, not the ones from last year. Programs update their fine print without prominent notification. If your convenience store spending is habitual — daily coffee, regular gas, weekly snacks — a single cashback card is probably your best bet. Anything more complicated than that is worth the effort only if you can quantify the actual return. Do the math. If stacking three different programs saves you four dollars a month, that's twenty-four dollars a year. Not worth the cognitive load or the security surface area. The payment landscape changes constantly. New apps launch, old ones die, banks tweak their terms. Stay informed but don't obsess. The biggest mistake I see people make is treating reward optimization like a second job. It isn't. Pick a sensible system, stick with it, and forget about it until your quarterly statement arrives.