What the Lane Bryant Credit Card Actually Gets You
Most people apply for the Lane Bryant credit card because they saw an offer at checkout — usually something like "save 30% today" or "special financing available." It's a store card issued by Comenity Bank, and it lives in that same tier as almost every other retail credit card you'll find at malls across the country. That means it comes with predictable benefits, predictable limitations, and a credit check that will land somewhere between soft and hard depending on when you apply. I've been helping people sort through these cards for years, and the Lane Bryant one comes up regularly because the target demographic is straightforward. If you shop Lane Bryant frequently, the math can work. If you go there once a year for a specific event, it probably doesn't.
The Ultimate Guide To Lane Bryant Credit Card Benefits Rewards And Eligibility
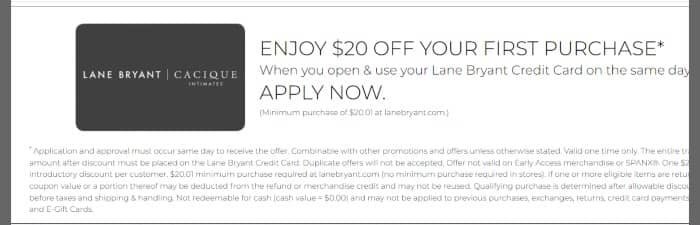
Let's get into the actual terms as they currently stand, because the fine print matters more than the headline offers. The rewards structure is standard for a store card. You earn points on purchases made at Lane Bryant and some associated brands like Moon Mavens and Pretty Plus. The typical rate is around 5 points per dollar spent in-store, with occasional promotional boosts that can push that higher during sale events. Those points translate to a certificate — usually $5 for every 500 points — that redeems toward future purchases. There's no cash-back option, no foreign transaction fee waiver worth writing home about, and no transfer partners. This is a closed-loop rewards system, which means your points are only useful at Lane Bryant stores or on lanebryant.com. The signup bonus is where most people make their decision. It fluctuates, but historically you'll see something in the range of 30% off your first purchase or a guaranteed certificate after spending a certain amount within the first 90 days. I recently had someone ask me about a borderline case where the bonus was advertised as "up to $50 off" — the "up to" meant they had to hit a specific spend threshold that wasn't clearly stated on the promotional page. I recommended they confirm the exact dollar threshold before applying, because the difference between a $30 discount and a $50 certificate on a $200 purchase is meaningful when you're budgeting.
Special financing is another common draw. Lane Bryant periodically offers deferred interest promotions — usually 6 or 12 months — on purchases above a minimum amount, often $299 or $499. Here's the thing most guides don't emphasize enough: deferred interest is not the same as no-interest financing. If you don't pay off the full balance by the end of the promotional period, interest is charged retroactively from the purchase date at the card's standard APR, which sits around 29.99% variable. I've seen people get caught by this more than once. The workaround is simple — set a calendar reminder for 30 days before the promotion expires, and pay down the balance aggressively from month one rather than making minimum payments and hoping for the best. Eligibility requirements follow the standard Comenity Bank pattern. You need to be at least 18 years old, a U.S. resident with a valid Social Security number, and have a bank account in your name. There's no published minimum credit score, but based on what applicants report, you're looking at a fair-to-good credit range — roughly 640 to 700 or above. People with thin files or recent collections have gotten approved, but it's not guaranteed. The application triggers a hard inquiry, and that shows up on your credit report for two years even if you're declined. One practical note about the application process: Comenity Bank's system can be slow to update approval status. I had a client who applied on a Tuesday and didn't get a decision until Thursday. She assumed it fell through and reapplied, which triggered a second hard inquiry. That's unnecessary — wait at least 48 hours before checking status or reapplying. You can call the number on the back of any existing Comenity card to check, or use their online account portal.
Get the Full Details
Other benefits include early access to sales, which for Lane Bryant can mean getting first dibs on seasonal inventory before non-cardholders. There's also a monthly newsletter with exclusive coupons, and occasionally a birthday certificate. These are nice touches but not game-changers. The real value proposition comes down to frequency of use and discipline in paying down balances. Here's the counter-intuitive part that beginners miss: the best time to use this card isn't during the biggest sale. It's during regular pricing periods when you can stack the card's member discount with a coupon code from the newsletter. A 20% off coupon plus the card's internal pricing can sometimes beat a 40% off sitewide sale that non-cardholders also get access to. I learned this the hard way when a customer complained she saved less on Black Friday using her card than she would have paid cash during an ordinary Tuesday with a well-timed coupon. She wasn't wrong. The main downside, and it's a big one, is that this card won't build your credit profile in any meaningful way beyond a single hard inquiry and a new account. It's a low-limit card — most people start at $200 to $500 — and while keeping the utilization low helps your score marginally, it doesn't carry the weight of a general-purpose rewards card. If building credit is your primary goal, a secured card or a beginner-friendly travel card makes more sense. The Lane Bryant card is a shopping tool first, not a credit-building instrument.
Another limitation worth noting: Comenity Bank has been tightening approval standards across its retail card portfolio. What worked for approval two years ago might not work today. Don't apply if you've had a recent hard inquiry from another credit card application — wait at least six months. And if you're already carrying high balances on other retail cards, adding another one will hurt your utilization ratio more than you'd expect. Bottom line: the Lane Bryant credit card is worth it if you shop there at least a few times a year, can pay the balance in full each month, and understand how deferred interest works. It's not worth it if you're applying just for a one-time discount you'll never use again. The certificate expires, the financing catches you if you're sloppy, and the rewards are locked into a single retailer. Plan accordingly.