Financing in accounting is one of those topics everyone glosses over until they have to deal with it
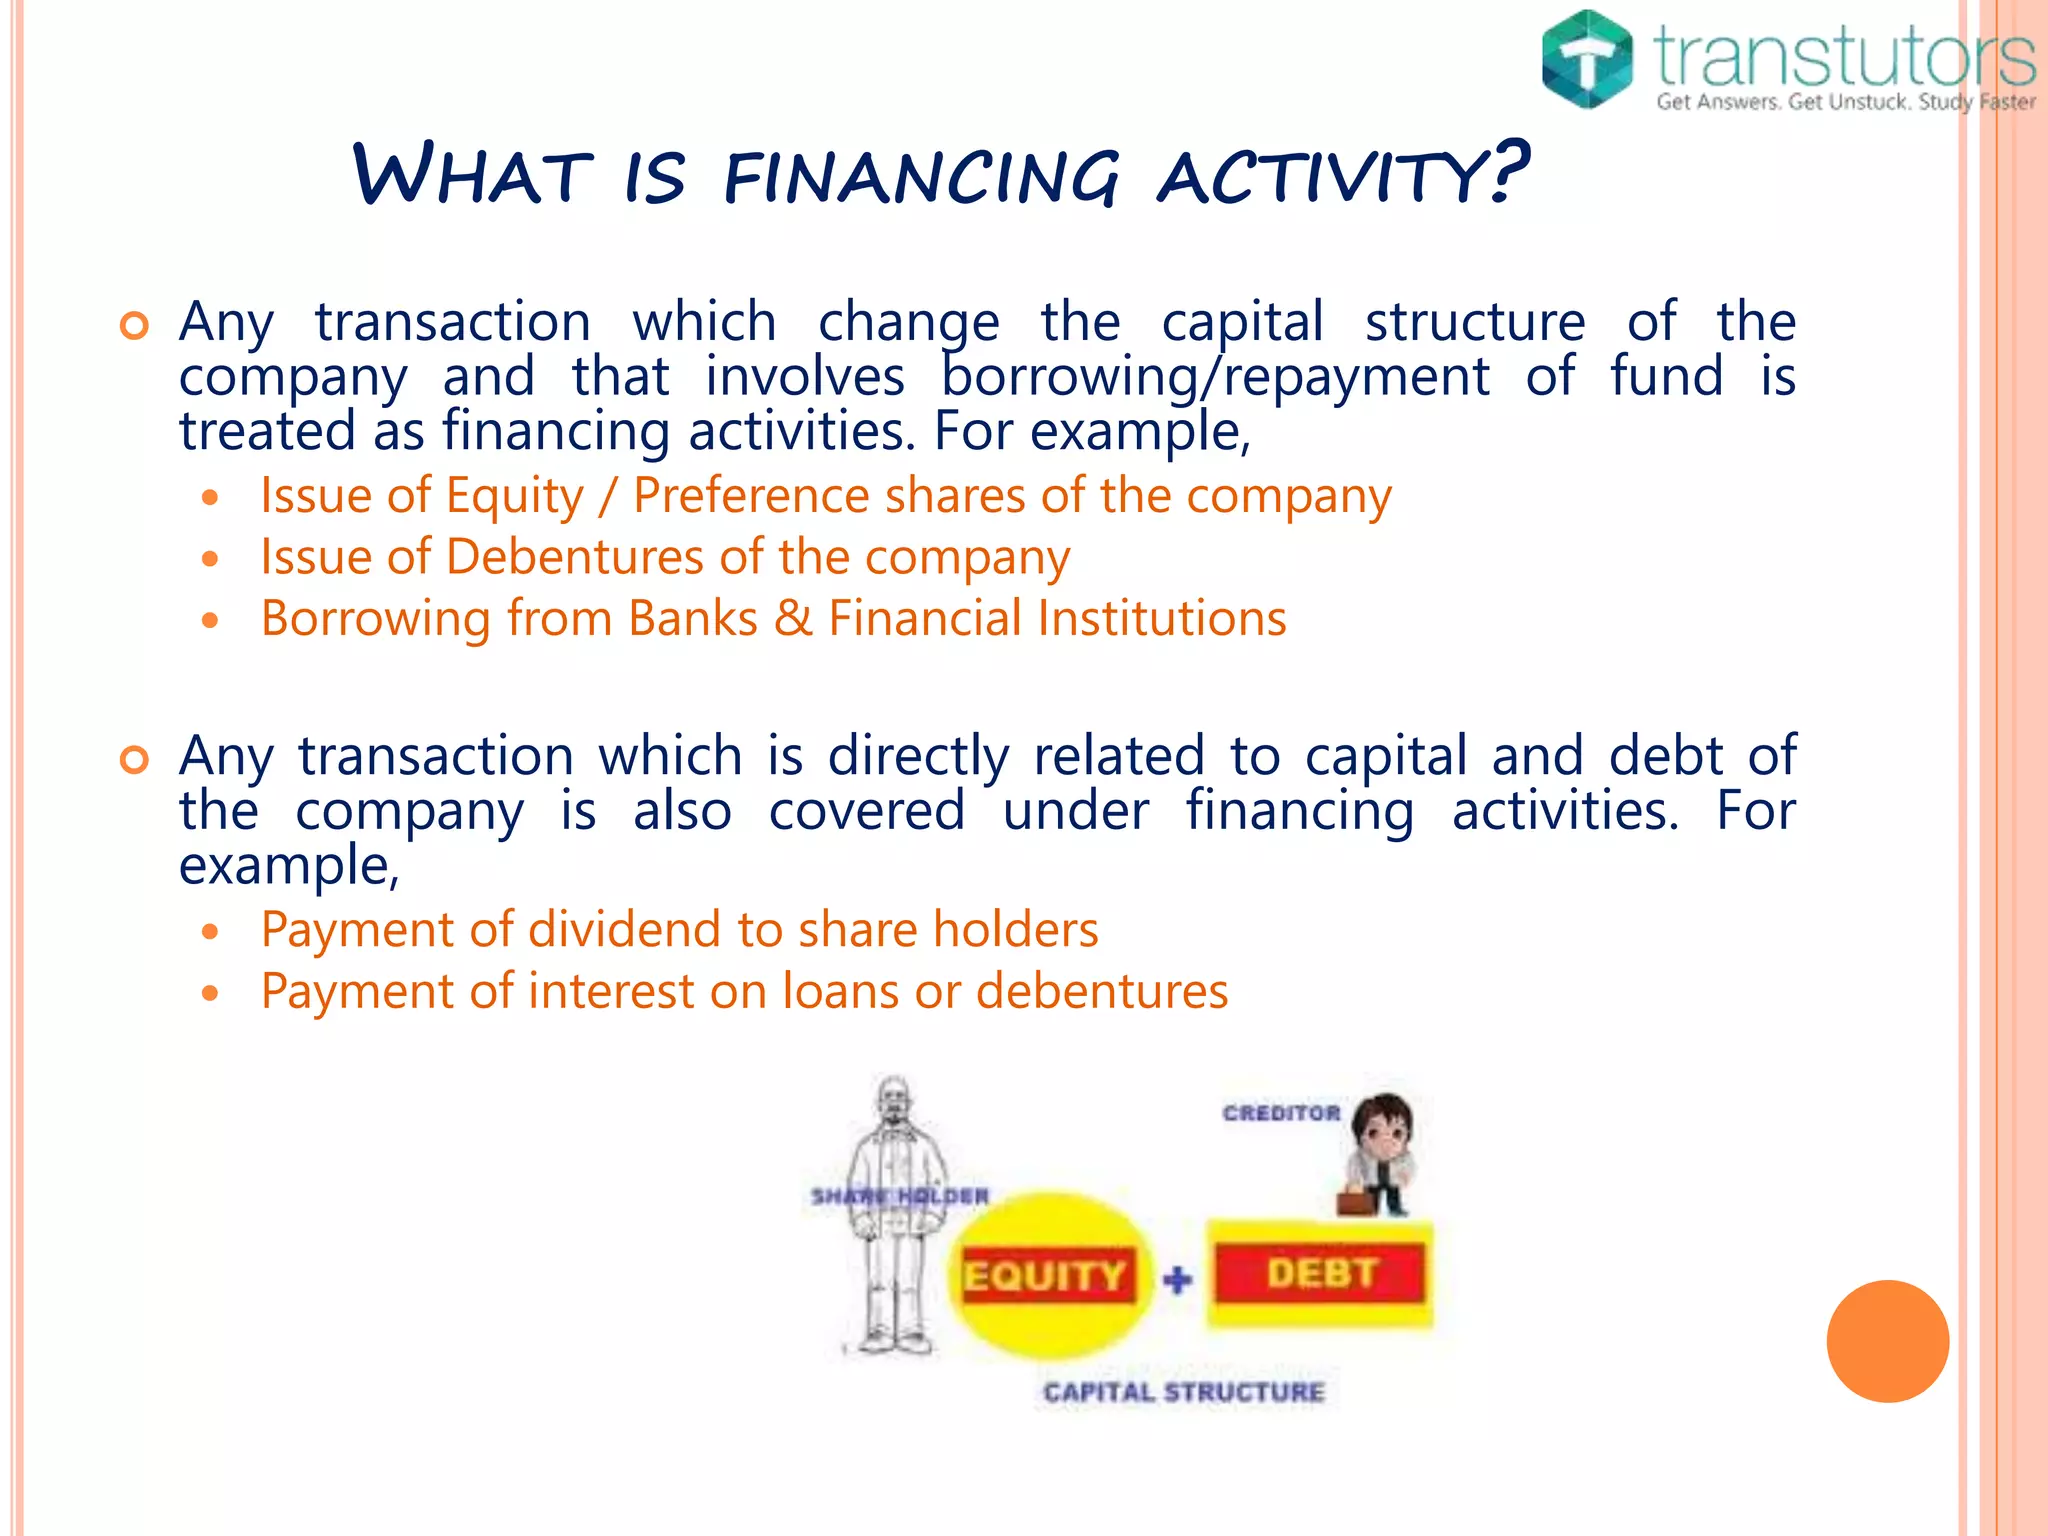
Most people think financing definitions are straightforward. Debt is debt, equity is equity, and you book them accordingly. In practice, the line between what counts as a financing activity versus an operating or investing activity gets surprisingly blurry, and that's where companies trip up. I'm going to walk through this the way I actually use it when I'm cleaning up a messy set of financials, not the way a textbook lays it out. At its core, financing in accounting refers to the methods a company uses to raise capital to fund its operations and growth. This includes taking on debt, issuing equity, and managing relationships with lenders and investors. On the balance sheet, you'll see this reflected in long-term debt, short-term borrowings, bonds payable, common stock, additional paid-in capital, and retained earnings. The cash flow statement is where it gets interesting, because financing activities show the actual movement of cash from these sources, and that statement is usually where I start when someone asks me to figure out what's really going on with a company's capital structure. The standard categories under financing activities are pretty straightforward: proceeds from issuing debt, repayments of debt principal, proceeds from issuing stock, repurchases of stock, and dividend payments. That's the basic framework. But the real world doesn't always fit neatly into those boxes, and that's where my patience for this topic really gets tested.
One thing beginners consistently get wrong is how lease obligations are treated. Under the old rules before ASC 842, operating leases were basically invisible on the balance sheet, and the lease payments showed up entirely as operating cash flow. After the standard changed, nearly all leases above a certain threshold now sit on the balance sheet as right-of-use assets and lease liabilities, and the principal portion of lease payments reclassified to financing activities while the interest component stays in operating. I've had clients come to me after an audit with cash flow statements that looked completely broken because their finance team didn't understand the reclassification, and fixing it took us about three days of reworking the schedule line by line. The workaround I use now is to run a lease liability rollforward first, then split the payment schedule into principal and interest before touching the cash flow statement. It takes fifteen minutes if your lease data is clean, which unfortunately it rarely is. Another area that causes real confusion is convertible debt. Is it a liability or equity? The answer depends on whether it has a cash settlement feature, whether it's indexed to the company's own stock, and whether the conversion option meets the derivative scope exception. If you're dealing with convertible notes issued in a raise, the accounting treatment can shift the instrument entirely out of liabilities and into equity, which dramatically changes your debt-to-equity ratio and your financing activity presentation on the cash flow statement. I had a startup client who issued $2 million in convertible notes thinking they were clean equity-classified instruments. They weren't. The embedded conversion feature failed the derivative exception because the settlement wasn't purely in shares. We ended up having to reclassify the entire instrument as a liability, which triggered covenant breaches on their existing credit facility and required an amendment that cost them an additional 125 basis points on their interest rate. That story alone should make you careful about how you structure these deals. When I teach this to junior analysts, I always push them to look at the financing definition through a practical lens rather than a theoretical one. Ask yourself: does this transaction change the company's capital structure? If the answer is yes, it's almost certainly a financing activity. Does it involve borrowing or equity issuance? Financing. Does it involve returning capital to investors? Also financing. The operating section of the cash flow statement should never be the catch-all for things that clearly belong in financing, even though I see companies do this constantly, particularly with things like deferred financing costs or debt issuance fees that get buried in operating expenses instead of being netted against the debt line item.
Here's a nuance most guides won't tell you: intercompany loans. When a parent company lends money to a subsidiary, that's a financing activity on both sides of the consolidation, but it completely disappears in the consolidated cash flow statement. I've seen analysts miss this because they were only looking at the consolidated view, not the individual entity statements. If you're doing due diligence on a company with a complex subsidiary structure, you need to look at the entity-level cash flows, not just the consolidated ones, or you'll miss significant internal financing that could mask liquidity problems at the subsidiary level. The financing definition in accounting also intersects heavily with disclosure requirements, and this is where the process gets tedious. You need to disclose maturity schedules for debt, interest rates, covenants, collateral, and any defaults or waivers. I usually build a debt schedule in Excel that tracks each facility separately with columns for original amount, current balance, interest rate, maturity date, covenant headroom, and next reporting requirement. It's not glamorous, but it's the single most useful document I have when preparing financial statements or responding to auditor questions. A well-maintained debt schedule saves probably two hours per reporting cycle compared to digging through loan agreements every time you need a number. There's also the question of what happens when you refinance debt. If you issue new debt to pay off old debt, that's a financing outflow and a financing inflow of equal amounts, so it nets to zero on the cash flow statement, but both amounts still need to be disclosed separately if they're material. I've seen people skip the disclosure because the net effect was zero, and that's a red flag that auditors will flag every time. The disclosure requirement exists precisely because the gross amounts matter for understanding rolling exposure and refinancing risk, even if the cash position doesn't change.
Get the Full Details

For companies that lease equipment or vehicles, I recommend maintaining a separate lease ledger alongside your main debt schedule. The reason is simple: lease modifications happen constantly, and it's easy to lose track of which payments have reclassified from operating to financing under the new standards. I keep a monthly reconciliation that compares the lease liability balance from the general ledger against the amortization schedule, and if there's a variance greater than fifty dollars, I dig into it immediately. Waiting until quarter-end to notice a four-month drift is how mistakes become material misstatements. One more thing that trips people up: treasury stock transactions. When a company buys back its own shares, that's a financing cash outflow. When it reissues those shares later, that's a financing cash inflow. The difference between the purchase price and the reissue price hits additional paid-in capital, not the income statement. I've seen controllers try to record the spread as a gain or loss, which is just wrong and will come back to haunt you in an audit. Treasury stock transactions are equity transactions, period. They don't affect net income at all. Financing activities also include things like debt issuance costs, which used to be amortized as operating expenses but are now presented as a direct deduction from the corresponding debt liability on the balance sheet under the current standards. That means you're amortizing the discount or deferred charge over the life of the debt using the effective interest method, and the amortization hits interest expense, not operating expense. This is a change that still catches people off guard, especially if you're working with financials prepared under different standard versions.
If you're trying to calculate free cash flow to equity, the financing definition becomes even more critical because FCFE starts with cash flow from operations and then adjusts for net borrowing and stock transactions. Miss a single financing line item and your FCFE number is wrong, which cascades into incorrect valuation multiples and misleading comparables. I've corrected three separate models in the past year where the analyst had misclassified lease principal payments as operating rather than financing, and each time the FCFE was overstated by roughly eight to twelve percent depending on the company's leverage profile. That's enough to swing a deal from pass to fail or vice versa. The bottom line is that financing in accounting is not a static definition you memorize and move on from. It's a moving target that shifts with every new standard, every lease modification, every refinancing, and every equity transaction. The practical approach is to build robust tracking systems, maintain clear schedules, and always verify the classification by asking whether the transaction changes the capital structure. If it does, it belongs in financing, plain and simple.